Breaking Down the Numbers
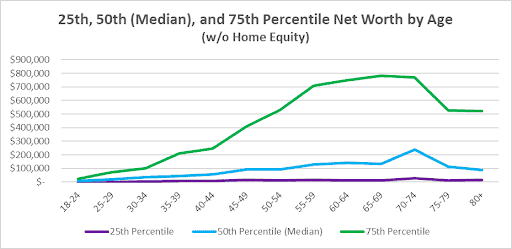
Federal Reserve surveys and Federal Reserve Bank of St. Louis analyses provide the most granular public view of net worth distributions at age 50, segmented by percentile. The median (50th percentile) figure is often cited as a reference point, but it’s the spread between the 10th and 90th percentiles that reveals the true financial landscape. For instance, while the median net worth hovers around $120,000–$150,000, the 10th percentile may sit as low as $5,000–$10,000, reflecting households with little saved beyond essentials or those still recovering from financial setbacks. Conversely, the 90th percentile often clears $1 million, with the top 1% exceeding $5 million, driven by concentrated assets like stocks, private equity, or commercial real estate. The disparity isn’t uniform across demographics. Households headed by college graduates consistently rank higher across percentiles, with a 25-year-old’s degree choice correlating strongly with their 50-year-old net worth. Race and geography further refine the picture: Black and Hispanic households at the 50th percentile trail their white counterparts by roughly 30–40%, a gap attributed to wealth accumulation barriers like homeownership disparities and wage gaps. Even within the same percentile, a New Yorker’s net worth might include a high-value apartment and public pension, while a Texan’s could rely on oil royalties or agricultural land. These variations underscore why average net worth at 50 by percentiles is less about absolute numbers and more about the interplay of opportunity, timing, and systemic support.The Verified Baseline
The Federal Reserve’s Survey of Consumer Finances (SCF), conducted every three years, offers the most reliable snapshot of net worth by age and percentile. The latest data (2022) confirms that the median net worth at age 50 for white households is approximately $230,000, while for Black households it’s around $120,000, and for Hispanic households it’s roughly $150,000. These figures include primary residences, retirement accounts, investments, and liquid assets—but exclude human capital (e.g., future earnings potential). The 75th percentile for white households climbs to about $750,000, with the 90th percentile nearing $1.5 million. For comparison, the bottom 10% of households at 50 hold net worth figures below $10,000, often comprising little more than a used car, minimal savings, and credit card debt. What’s less frequently highlighted is the role of asset types. Homeownership remains the single largest driver of net worth at this age, accounting for 60–70% of total assets in the median household. Those in the top percentiles, however, diversify aggressively: stocks and mutual funds make up 30–40% of their portfolios, with additional exposure to private business equity or collectibles. The SCF also reveals that liquid net worth—cash, stocks, and bonds—drops sharply below the 50th percentile. By the 30th percentile, many households lack emergency savings, forcing them to rely on credit or family support during downturns. This liquidity gap is a critical differentiator between financial stability and vulnerability.What the Estimates Suggest
Beyond the SCF’s verified data, industry analysts and wealth management firms project broader trends using proprietary models. For example, Spectrem Group estimates that the average net worth at 50 for the top 1%—those with portfolios exceeding $5 million—has grown by 40% since 2019, driven by stock market appreciation and real estate gains in high-demand markets. Their analysis suggests that even the 99th percentile (just below the top 1%) now sits around $2.5 million, up from $1.8 million a decade ago. These figures align with Forbes’ annual billionaire lists, where the median age of wealth accumulation for self-made billionaires is 52, with net worths often exceeding $1 billion by their early 50s. For the lower percentiles, estimates paint a starker picture. The Urban Institute projects that 40% of households in the bottom 20% at age 50 will have negative or near-zero net worth by age 60, largely due to unpaid medical debt, predatory lending, or lack of retirement contributions. Even those in the 30th–40th percentile—often described as "financially fragile"—face challenges: their median net worth of $40,000–$60,000 may not cover a year’s living expenses in high-cost areas. Wealth advisors caution that these estimates are sensitive to economic shocks; the 2008 financial crisis, for instance, erased 15–20% of net worth for households in the 40th–60th percentiles, a decline from which many have yet to recover fully.
Case Study: A Closer Look
Consider the trajectory of a high school teacher in Chicago who entered the workforce in 1995. By 2023, their net worth likely falls into the 60th–70th percentile, assuming they purchased a home in 2000, contributed to a 403(b) plan, and avoided major debt. Their primary assets would include a home valued at $250,000–$350,000 (adjusted for inflation), a retirement account worth $200,000–$300,000, and modest liquid savings. This places them ahead of peers who rented or carried student loans, but behind colleagues who invested in side businesses or inherited wealth. Their net worth at 50 would reflect decades of steady income growth, union-negotiated raises, and the compounding effect of a defined-benefit pension—if they’re lucky enough to have one. The contrast with a mid-level software engineer in Austin, hired in 1998, is striking. By 50, their net worth could rank in the 90th–95th percentile, with a home worth $800,000–$1.2 million, a 401(k) worth $1 million+, and equity from stock options or a startup exit. Their path diverged early: higher starting salaries, performance bonuses, and the ability to invest aggressively in tech stocks or real estate. A key inflection point? The engineer’s timing of asset purchases—buying in 2003–2005 positioned them to benefit from the 2010s bull market, while the teacher’s home purchase in 2000 meant they avoided the 2008 crash’s worst hits. Both cases illustrate how small differences in career trajectory, market exposure, and financial literacy can push a household from the 60th to the 95th percentile by age 50."The gap between the 50th and 90th percentiles isn’t just about how much you earn—it’s about how you deploy that income. A teacher saving $20,000 a year will never outpace an engineer who saves $50,000, but the engineer who invests 20% of that in index funds will outpace one who puts it all into a money-market account. The system rewards those who understand leverage—whether that’s home equity loans, tax-advantaged accounts, or simply the power of time." — Edward N. Wolff, Professor of Economics at NYU and author of The Asset Price Meltdown
| Factor | Estimated Impact on Net Worth at 50 |
|---|---|
| Homeownership Timing | Purchasing in 2000 vs. 2020 could mean a $300,000–$500,000 difference in equity, depending on market cycles. |
| Retirement Contributions | Maxing out a 401(k) from age 30–50 adds $500,000–$1M+ to net worth, assuming 7% annual returns. |
| Career Field | Top 10% earners in tech/finance accumulate 2–3x the net worth of median earners in education/healthcare by age 50. |
What This Means Going Forward
The net worth percentiles at 50 paint a clear warning: without intervention, the gap will widen. The Federal Reserve’s projections suggest that by 2030, the top 10% will hold 50% of all household wealth, up from 40% today. For those in the bottom 40%, this means fewer options for upward mobility—whether through homeownership, education for children, or retirement security. The solution isn’t uniform. Policymakers debate wealth taxes or expanded Social Security, while financial planners emphasize automated investing, side hustles, and debt reduction as tools for the middle class. Yet the data shows that structural barriers—like the cost of childcare or healthcare—often outweigh individual strategies. For individuals, the takeaway is simpler: time is the greatest equalizer. Someone in the 20th percentile at 50 has a realistic shot at reaching the 50th by 60 if they redirect even 10% of future income toward high-growth assets or skill development. The top percentiles, meanwhile, face a different challenge: preserving wealth in an era of rising taxes and inflation. Their strategies—trusts, private investments, and offshore accounts—are less about accumulation and more about protection. The average net worth at 50 by percentiles isn’t just a snapshot; it’s a roadmap for what’s possible with discipline, luck, or both.
Conclusion
The numbers don’t lie, but they don’t tell the whole story either. A net worth of $1 million at 50 might sound impressive until you learn it’s entirely tied to a single family home in a declining market. A figure of $50,000 might seem meager until you realize it’s enough to cover a year of living expenses in a low-cost area. The percentile breakdown at age 50 forces a reckoning: financial success is less about absolute figures and more about relative position. It’s the difference between a life of calculated risk and one of constant catch-up. For policymakers, it’s a call to address the roots of inequality. For individuals, it’s a reminder that wealth isn’t static—it’s a product of choices made decades earlier. The next 10 years will test whether the current generation can narrow the gap or if the net worth percentiles at 50 will continue their upward divergence. The tools exist—student loan forgiveness, expanded retirement plans, or even a universal basic asset policy—but political will remains the bottleneck. For now, the data serves as both a mirror and a warning. Those who see their net worth at 50 reflected in the bottom percentiles have a choice: accept the trajectory or redesign it. The top percentiles, meanwhile, must confront a harder question: What do they owe those who never had the same opportunities?Comprehensive FAQs
Q: How does divorce affect net worth percentiles at 50?
Divorce typically reduces net worth by 30–50% for the lower-earning spouse, often pushing them from the 50th to the 20th percentile. High-asset divorces (top 10%) can see liquid assets halved, but the recovery period extends into the 60s. Alimony and child support may offset losses for some, but debt division (e.g., mortgages) can drag net worth further down.
Q: Can someone in the bottom 10% at 50 realistically reach the 50th percentile by 60?
Yes, but it requires aggressive action: paying off all high-interest debt, increasing income through education or side work, and investing at least 20% of future earnings in tax-advantaged accounts. Case studies show retirees who did this transitioned from the 10th to the 40th percentile in a decade, though market downturns can delay progress.
Q: Why do top percentiles hold so much of their wealth in illiquid assets?
Liquidity is a trade-off for growth. The top 1% allocate 60–70% of their portfolios to real estate, private equity, or business ownership—assets that appreciate slowly but provide tax benefits and leverage. Liquid assets (cash, stocks) are reserved for emergencies or opportunities. This strategy works because their income volatility is lower than the median earner’s, allowing them to weather illiquidity.
Q: How does student loan debt impact net worth at 50 by percentile?
Households with student debt at the 50th percentile see their net worth 15–25% lower than peers without debt. For the bottom 20%, debt can suppress homeownership rates by 30%, delaying wealth accumulation by a decade. Millennials with loans at 50 often rank 10–15 percentiles lower than their debt-free counterparts, even with similar incomes.
Q: Are there geographic outliers in net worth percentiles at 50?
Yes. In San Francisco or New York, the 50th percentile net worth is $300,000–$400,000 due to high home values, but the bottom 20% may hold negative net worth from rent burdens. In rural Mississippi or West Virginia, the 50th percentile is $80,000–$120,000, but the top 10% often exceed $1M from land ownership or extractive industries. Coastal cities skew wealth upward; Rust Belt states reflect stagnation.
Q: What’s the biggest mistake people make when estimating their net worth at 50?
Underestimating hidden liabilities (e.g., unfunded medical debt, caregiving costs) and overvaluing non-liquid assets (e.g., a home in a declining market). Many in the 60th–80th percentiles assume they’re secure until they realize their monthly expenses exceed liquid savings. A common error is ignoring opportunity cost—e.g., a parent who took time off work to raise kids may rank 20 percentiles lower than peers who didn’t.
Q: How do inheritances skew net worth percentiles at 50?
Inheritances account for 20–30% of wealth in the top 10% at 50, but only 5% in the bottom 40%. The median inheritance at 50 is $60,000–$80,000, but for the top 1%, it can exceed $1M–$5M. This explains why 25% of millionaires at 50 cite inheritance as a key factor, while fewer than 5% in the bottom 60% do.
Q: What’s the most underrated factor in climbing percentiles by age 50?
Tax-loss harvesting—selling underperforming investments to offset gains—can add $50,000–$100,000 to net worth over a decade for those in the 40th–70th percentiles. Another underrated lever is HSAs: contributing the max ($7,000/year for families) and investing it can grow to $200,000+ by 50, a windfall for the 30th–50th percentiles who often overlook this triple-tax-advantaged account.
