
The Short Answers
- The median net worth 2021 percentile for U.S. households was ~$120,000, placing most Americans in the 50th percentile or below.
- Top 1% households in 2021 had net worths exceeding $10 million, a threshold that pushed them into the 99th+ percentile.
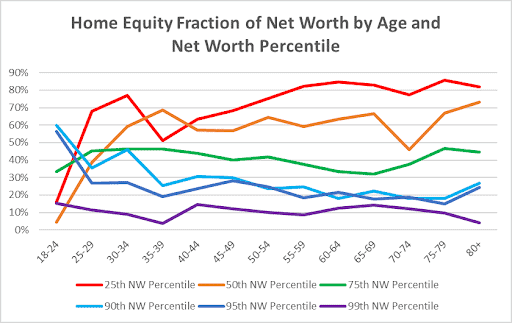
- Homeownership was the single biggest driver of percentile jumps—renters saw their net worth 2021 percentile stagnate or decline.
- Black and Hispanic households had median net worths half or less of white households, widening percentile gaps.
- Stock market gains in 2021 inflated percentiles for investors, but 40% of Americans had no investable assets at all.
- Percentile rankings vary wildly by state—Massachusetts households in the 90th percentile often had less wealth than Texas households in the 80th.
Deep Dive: The Full Picture
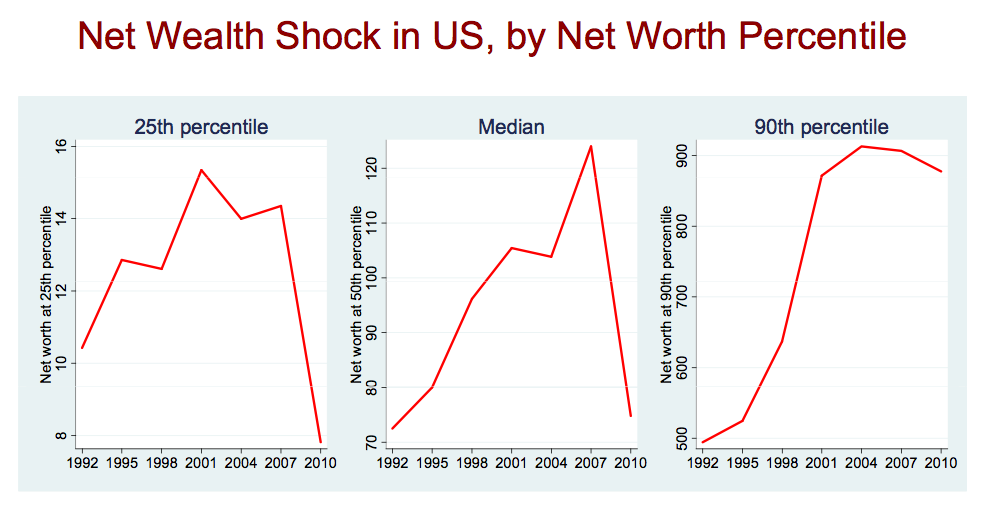
The net worth 2021 percentile isn’t just a reflection of individual savings habits; it’s a product of systemic forces. The pandemic accelerated existing trends: the rich got richer through asset appreciation, while the middle class saw wage growth outpaced by inflation. When the Fed’s Survey of Consumer Finances released its 2021 data, it confirmed what economists had predicted—the K-shaped recovery had left percentiles as a proxy for economic survival. A household in the 75th percentile in 2019 might have dropped to the 65th by 2021, not because they spent more, but because the baseline wealth of others had surged. The percentile became a lagging indicator of inequality. What’s often overlooked is how percentiles distort perception. A family earning $150,000 annually might feel "middle class," but their net worth 2021 percentile could place them in the top 20% if they own a home and have retirement savings. Conversely, a couple earning $200,000 but living paycheck-to-paycheck might rank in the 40th percentile. The disconnect between income and wealth percentiles explains why so many Americans feel financially insecure despite strong GDP growth. The percentile isn’t just about dollars—it’s about access to generational wealth.The Context You Need
Understanding the net worth 2021 percentile requires acknowledging two critical factors: asset concentration and liquidity traps. The top 1% controlled roughly 35% of all investable assets, but their percentile wasn’t just about dollar amounts—it was about control. Private equity, real estate, and stock holdings allowed them to weather downturns, while the bottom 50% lacked similar buffers. The percentile gap between homeowners and renters was stark: the former saw their net worth 2021 percentile rise by 15% on average, while the latter stagnated. The second layer is regional. A household in San Francisco with a $1.5 million net worth might rank in the 92nd percentile nationally, but locally, that same figure could place them in the 70th percentile due to sky-high housing costs. The net worth 2021 percentile is a national average, not a universal truth. Even within states, disparities exist—urban vs. rural, coastal vs. inland. Ignoring these nuances turns percentiles into a misleading benchmark.The Mechanics
Percentiles are calculated by ranking all households by net worth and dividing them into 100 equal groups. The 50th percentile is the median—the point where half the population has more, half has less. In 2021, the median net worth for a U.S. household was $120,000, but for a family of four, it dropped to $255,000. The mechanics are simple, but the implications are not. A percentile jump from the 60th to the 70th might feel significant, but if your absolute net worth only increased by $20,000, the real gain was minimal. The Fed’s data also reveals that percentiles are not static. A 30-year-old in the 80th percentile in 2021 might drop to the 60th by 2030 if they don’t inherit wealth or invest aggressively. Conversely, someone in the 50th percentile at 30 could climb to the 85th by 50 if they benefit from compounding and home appreciation. The net worth 2021 percentile is a snapshot, not a forecast—but it’s the best proxy we have for predicting future mobility.Details That Change the Picture
The net worth 2021 percentile ignores one critical variable: debt. A household with $500,000 in assets but $400,000 in mortgage debt might rank in the 85th percentile, but their liquid net worth could place them in the 50th. The percentile doesn’t distinguish between leverage and true wealth. Similarly, student loan debt—now exceeding $1.7 trillion—dragged millions of young households into lower percentiles, even if their incomes were rising. The system treats all debt as equal, but in reality, a mortgage can build equity while student loans often don’t. Another blind spot is non-financial wealth. A family with a paid-off home, a thriving small business, or inherited land might have a net worth 2021 percentile in the 90th range, but traditional surveys miss these assets. The percentile favors liquidity over substance, which is why so many Americans feel wealthy on paper but struggle in practice. The data also obscures intergenerational transfers. Those who inherit wealth see their percentiles spike overnight, while those who don’t are left chasing the same benchmarks with no head start."Wealth percentiles are like a funhouse mirror—they reflect reality, but distorted. A $1 million net worth in Detroit doesn’t carry the same weight as $1 million in Silicon Valley. The system treats them as equal, but life doesn’t." — Edward N. Wolff, Professor of Economics at NYU
| Percentile Range | Estimated Net Worth Threshold (U.S., 2021) |
|---|---|
| 25th Percentile (Below Median) | $45,000 (Single) / $90,000 (Family of 4) |
| 75th Percentile (Above Median) | $280,000 (Single) / $600,000 (Family of 4) |
| 90th Percentile (Top 10%) | $1.4M+ (Single) / $2.5M+ (Family of 4) |
Conclusion
The net worth 2021 percentile is more than a number—it’s a conversation starter about economic mobility, policy failures, and personal resilience. While the data shows clear divides, it also reveals opportunities: geographic arbitrage, strategic debt management, and early investing can shift percentiles over time. But the system is rigged. Those who enter adulthood with inherited wealth or family connections have an unfair advantage in percentile climbing. The question isn’t just where you stand in 2021, but why you’re there—and what it will take to move. For most Americans, the percentile isn’t a measure of success; it’s a warning sign. If your net worth 2021 percentile is stagnant while the median rises, it’s not a personal failure—it’s a structural one. The data doesn’t lie, but it doesn’t tell the whole story either. The real work begins when you ask: What can I control? And more importantly, what does society owe those left behind?Comprehensive FAQs
Q: How does the net worth 2021 percentile compare to pre-pandemic years?
The median net worth 2021 percentile was higher than 2019 for homeowners due to housing market gains, but lower for renters when adjusted for inflation. The top 10% saw their percentiles rise sharply, while the bottom 40% experienced little to no growth. The pandemic widened the gap between those with assets and those without.
Q: Can I improve my net worth percentile without earning more?
Yes, but it requires strategic leverage. Paying down high-interest debt, investing in index funds, or refinancing a mortgage can boost your percentile faster than a salary increase. Homeownership is the most reliable percentile accelerator for most Americans, followed by inherited wealth or windfalls (e.g., tax refunds, bonuses). However, without income growth, the gains are often temporary.
Q: Why do Black and Hispanic households have lower net worth percentiles?
Systemic barriers explain the gap: redlining history, lower homeownership rates, wage disparities, and limited access to inheritance. A 2021 study found Black households had a median net worth $24,100 vs. $188,200 for white households—placing most in the bottom 30th percentile even if incomes were comparable. Policy changes (e.g., student debt relief, wealth-building programs) could shift these percentiles over decades.
Q: Does a high net worth percentile mean I’m financially secure?
Not necessarily. A high percentile (e.g., 90th+) often correlates with liquidity, but not always with emergency funds or debt-free status. Ultra-high percentiles (99th+) may include families with illiquid assets (e.g., private businesses, art) that can’t be converted to cash quickly. True security requires diversified, liquid wealth—not just a high percentile ranking.
Q: How often should I check my net worth percentile?
Annually is sufficient for most people, but major life events (marriage, inheritance, job changes) warrant a review. The percentile isn’t a daily metric—it’s a long-term trend indicator. Obsessing over quarterly shifts can lead to poor decisions (e.g., selling investments during volatility). Focus on absolute growth first, then compare to percentiles.
Q: Can the government change net worth percentiles?
Indirectly, yes. Policies like student debt forgiveness, expanded child tax credits, or wealth-building programs (e.g., baby bonds) could lift percentiles for lower-income groups. However, structural changes—like tax reforms or housing policy—take decades to impact percentiles. The 2021 data shows that without intervention, the top percentiles will continue to pull away.
