
The Short Answers
- The percentage of net worth in primary residence typically ranges from 30% to 70%, but can exceed 80% in high-cost markets or for older homeowners.
- Younger households (under 35) often hold under 20% of net worth in their home, while those 65+ may see 50%+ tied to property.
- Renters rarely allocate more than 5% to 10% to future home purchases in their net worth calculations, assuming liquidity elsewhere.
- Home equity lines of credit (HELOCs) can temporarily inflate the apparent share of net worth in real estate, but debt reduces true ownership stake.
- Divorces, inheritance, or sudden job relocations can disrupt the balance, forcing rapid adjustments to the home’s role in net worth.
- Financial advisors recommend keeping the primary residence below 40% of net worth to maintain liquidity and diversification.
Deep Dive: The Full Picture
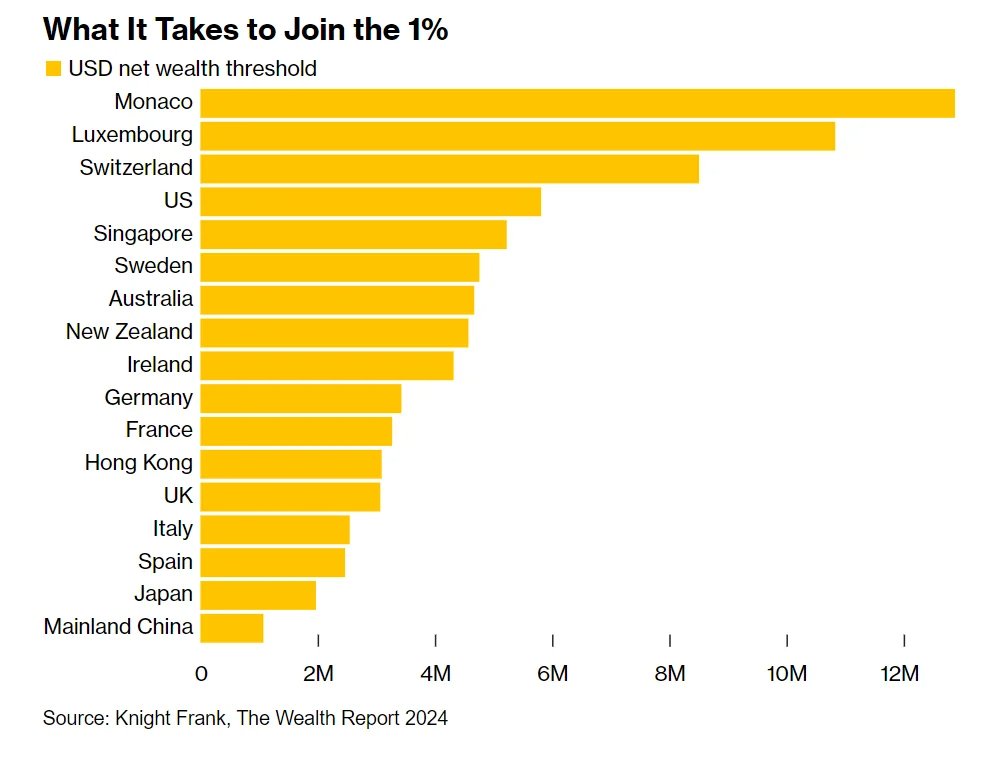
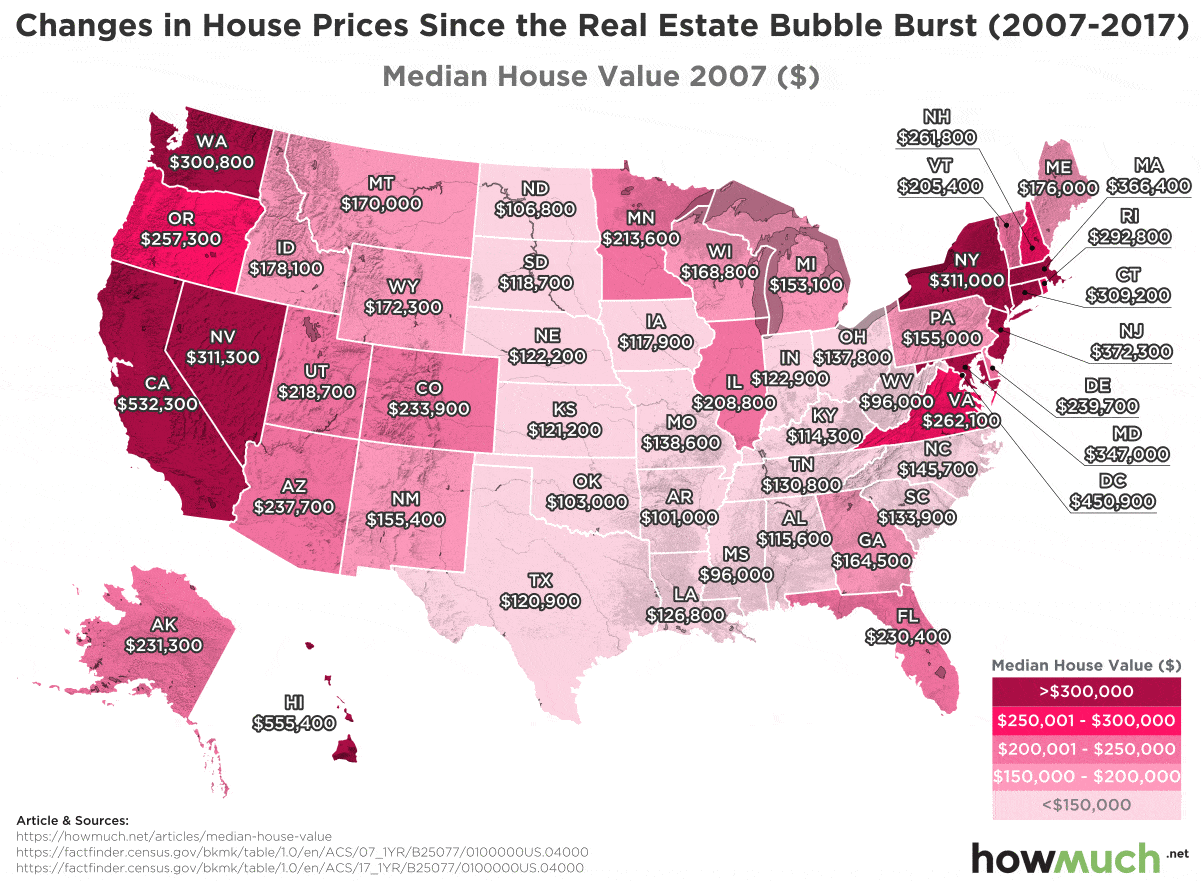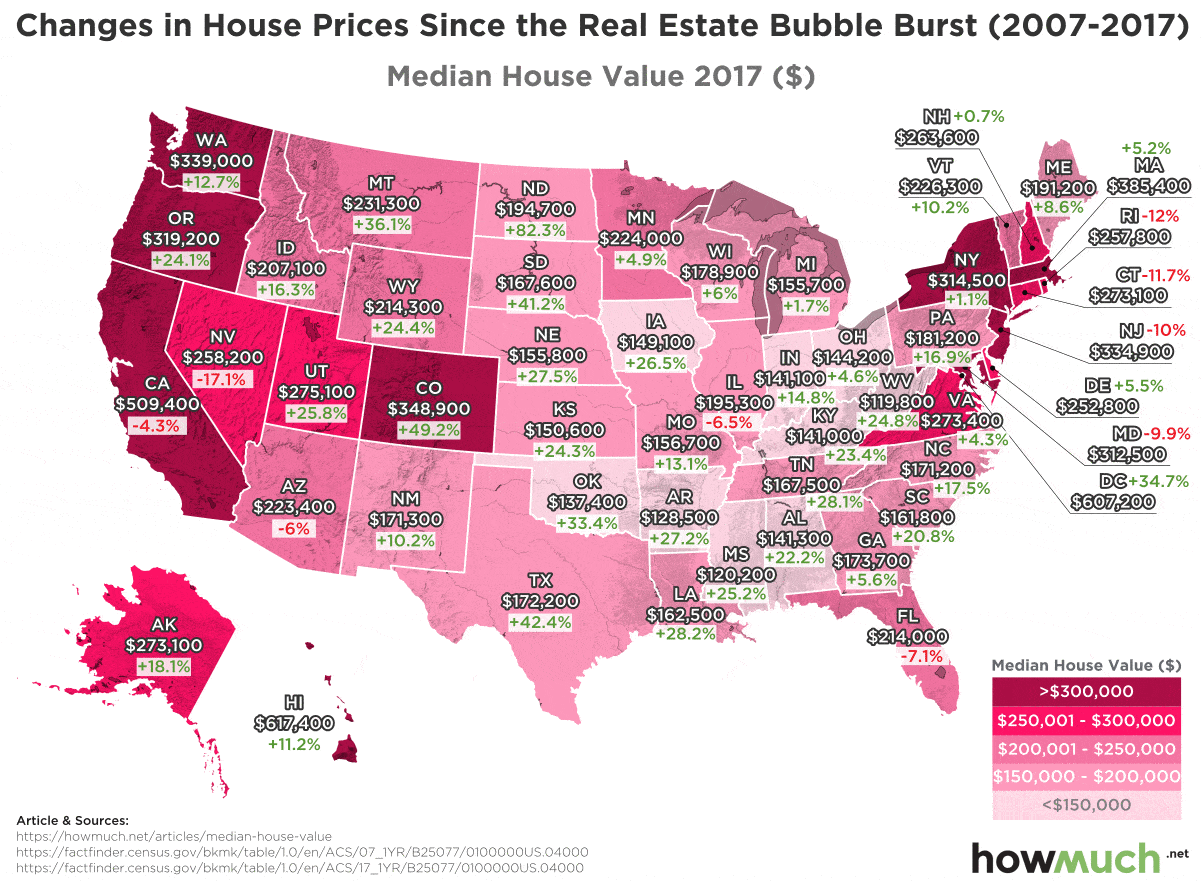
The percentage of net worth in primary residence serves as a litmus test for economic health. In the U.S., Federal Reserve data shows that for homeowners aged 35–44, the median home accounts for roughly 45% of net worth, while for those 65 and older, that figure climbs to 60% or higher. The pattern mirrors life stages: early-career buyers leverage mortgages to keep the home’s share low, while retirees—with paid-off properties—see their residence dominate assets. Yet this snapshot masks regional extremes. In San Francisco or New York, where median home prices exceed $1.5 million, the share of net worth in real estate for middle-class owners can approach 80%, leaving little cushion for healthcare or long-term care. Conversely, in rural Midwest markets, a $200,000 home might represent just 25% of net worth for a household with diversified investments. The concentration effect isn’t just a U.S. phenomenon. In Canada, where housing costs have surged 150% since 2000, the average primary residence now holds 55% of homeowners’ net worth, according to the Bank of Canada. In Australia, where foreign investment has inflated prices, the top 20% of wealth holders allocate 70%+ of assets to property, while the bottom 40% see their homes account for less than 15%. These disparities highlight how housing policy—zoning laws, tax incentives, or rental regulations—directly shapes the distribution of net worth across asset classes. The result? A society where homeownership isn’t just a personal choice but a wealth amplifier or a debt trap, depending on timing and location.The Context You Need
Understanding the percentage of net worth in primary residence requires parsing three layers: market cycles, demographic trends, and behavioral biases. During housing booms, like the 2000s or the pandemic-era surge, the home’s share of net worth ballooned as prices outpaced wage growth. Yet when bubbles burst—as in 2008 or the early 1990s—the same homes suddenly represented a larger proportion of shrinking net worth, forcing distress sales. Demographically, millennials entering homeownership today start with a disadvantage: student debt and stagnant wages mean their first homes often contribute less than 10% of net worth at purchase, compared to 20%+ for Gen Xers at the same age. Behavioral economics plays a role too. Studies show homeowners overestimate their home’s future value by 15% to 20%, leading to over-leveraging and misallocated savings. The liquidity trap of home equity is another critical factor. Unlike stocks or bonds, selling a primary residence isn’t a quick fix—it requires moving, incurring transaction costs, and navigating emotional attachments. This illiquidity explains why financial planners urge clients to keep the home’s share below 40% of net worth. When that threshold is crossed, a single event—a job loss, divorce, or medical emergency—can force a fire sale at an inopportune time. The percentage of net worth in real estate thus becomes a stress test for financial resilience. For retirees, where the home may represent 50% to 60% of assets, this concentration can delay or derail retirement plans if they’re forced to downsize unexpectedly.The Mechanics
The mechanics of how the primary residence’s share of net worth evolves depend on three variables: mortgage paydown, appreciation, and additional savings. For a young buyer taking a 30-year mortgage, the home’s net worth contribution starts near zero (since equity is minimal) but grows as principal is paid. By year 10, with 20% equity and assuming 3% annual appreciation, the home might represent 15% to 20% of net worth. By retirement, if the mortgage is paid off and the home has appreciated 2% above inflation, the share of net worth in real estate could exceed 50%. However, this trajectory assumes no major market downturns or personal financial shocks. The mortgage amortization curve is the primary lever here. Early payments are mostly interest, so equity builds slowly. Only after 10 to 15 years does the home’s net worth percentage accelerate. This is why financial advisors often recommend paying down mortgages aggressively in the first decade of ownership—even if it means forgoing higher-yield investments. The trade-off? Liquidity vs. security. A paid-off home offers 100% equity, but selling it to access cash requires exiting the housing market entirely. For retirees, this becomes a double-edged sword: the home may be their largest asset, but converting it to cash can disrupt lifestyle plans. The percentage of net worth in primary residence thus reflects a deliberate choice between flexibility and stability.Details That Change the Picture
The percentage of net worth in primary residence isn’t just a static number—it’s a dynamic ratio influenced by external shocks and personal strategies. For example, during the 2020 housing boom, home prices in the U.S. rose 15% annually in some markets, temporarily inflating the home’s share of net worth for sellers. Yet for buyers entering the market then, that same home now represents a larger proportion of their net worth due to higher entry costs. Similarly, rising interest rates in 2022–2023 reduced homebuying power, causing first-time buyers to allocate a higher percentage of their net worth to down payments, leaving less for investments. These swings highlight how policy and macroeconomic forces can distort the real estate-to-net-worth ratio within a single generation. Another critical factor is inherited wealth. When a primary residence is passed down, the heir’s percentage of net worth in real estate can spike overnight—especially if they lack other assets. A $800,000 inherited home for a 30-year-old with $50,000 in savings suddenly means 94% of their net worth is tied to one illiquid asset. This explains why trusts and estate planning often include provisions to diversify inherited real estate before transfer. Conversely, divorce settlements can force one spouse to sell the home, abruptly reducing the home’s share of net worth while creating a liquidity gap. These life events underscore why financial planners treat the primary residence’s net worth percentage as a living metric, not a fixed benchmark."The biggest mistake homeowners make isn’t underestimating market risks—it’s assuming their home’s value will always outpace inflation. When you’ve allocated 50% or more of your net worth to one asset, you’re not investing; you’re betting the farm." — Jane Bryant Quinn, personal finance columnist and author of How to Make Your Money Last
| Demographic Group | Typical % of Net Worth in Primary Residence |
|---|---|
| Young homeowners (under 35) | 10%–25% (mortgage-heavy, low equity) |
| Mid-career (35–54) | 30%–50% (equity building, but still diversifying) |
| Pre-retirees (55–64) | 40%–60% (mortgage paid down, but savings lagging) |
| Retirees (65+) | 50%–70%+ (home often the largest asset) |
Conclusion
The percentage of net worth in primary residence is more than a household balance sheet entry—it’s a barometer of economic vulnerability and opportunity. For younger generations, where the home’s share is often under 20%, the focus shifts to building liquid assets before committing to real estate. For older cohorts, where the home’s net worth percentage can exceed 50%, the challenge is preserving equity without sacrificing lifestyle. The data reveals a generational wealth transfer where homeownership is both a legacy asset and a financial anchor. Yet the risks are clear: overconcentration in real estate reduces resilience to market shocks, job instability, or health crises. The optimal share of net worth in a primary residence isn’t a one-size-fits-all number—it’s a personal risk tolerance equation, balancing security against the need for flexibility. The lesson for individuals and policymakers alike is this: housing wealth isn’t wealth until it’s liquid. A $1 million home on paper may feel like financial security, but if it represents 60% of net worth, a 10% market correction suddenly turns paper gains into a liquidity crisis. Smart strategies—whether accelerated mortgage paydown, rental income diversification, or trust structures for inherited property—can mitigate the risks. But the first step is recognizing that the percentage of net worth in your primary residence isn’t just about home values. It’s about how you’ll live—and survive—when the market turns.Comprehensive FAQs
Q: How does the percentage of net worth in primary residence differ between urban and rural homeowners?
The gap is stark. In high-cost urban areas, the median home may account for 50% to 70% of net worth due to inflated prices and lower alternative investment opportunities. In rural or low-cost regions, the home’s share often falls between 20% and 40%, allowing for greater diversification in stocks, farmland, or small businesses. The disparity reflects both housing affordability and local economic structures—urban homeowners are more likely to rely on real estate as their primary wealth store.
Q: Can a home equity line of credit (HELOC) artificially inflate the apparent share of net worth in real estate?
Yes, but it’s a misleading metric. A HELOC increases the stated value of your home on paper, but the debt offsets true equity. For example, a $1 million home with a $500,000 HELOC may show as 100% of net worth in a snapshot, but the actual ownership stake is only 50%. Financial planners warn that leveraging home equity to fund lifestyle expenses can distort the real percentage of net worth in liquid assets, increasing financial fragility.
Q: Why do retirees often have a higher percentage of net worth in their primary residence than working-age homeowners?
Three factors dominate: paid-off mortgages, slower income growth, and reduced investment diversification. Retirees typically enter this phase with little to no mortgage debt, meaning their home’s full value is part of net worth. Meanwhile, Social Security and pension income often don’t keep pace with inflation, leaving real estate as the most stable asset. Finally, many retirees shift from stocks to bonds, reducing their non-real-estate asset base and further concentrating wealth in the home.
Q: Does the percentage of net worth in primary residence vary by cultural or national housing norms?
Absolutely. In Japan, where homeownership rates are high but mortgages are rare (due to cultural aversion to debt), the home’s share of net worth can exceed 80% for older households. In Germany, where renting is more socially acceptable, the median home’s net worth percentage hovers around 30% to 40%, even for long-term owners. Meanwhile, in Latin America, where informal housing markets dominate, the home’s value may not be formally recorded, making the percentage of net worth in real estate harder to quantify but often higher due to lack of alternative assets.
Q: How can divorce or inheritance affect the share of net worth in a primary residence?
Both events can disrupt the balance dramatically. In a divorce, if one spouse keeps the home, their percentage of net worth in real estate may double overnight if they lacked other assets. Inheriting a primary residence can have the opposite effect: if the heir has no other wealth, the home may suddenly represent 90%+ of net worth, forcing them to sell or refinance aggressively. Financial planners often recommend selling inherited property within 1–2 years to rebalance the net worth ratio and avoid overconcentration.
Q: Are there tax strategies to reduce the effective percentage of net worth in a primary residence?
Indirectly, yes. Strategies like home equity loans for investment purposes (not personal expenses) or renting out a portion of the home can shift taxable income away from the primary residence’s value. For high-net-worth individuals, transferring the home to a trust or selling to a family member at a discounted rate (with proper valuation) can reduce estate tax liabilities, indirectly lowering the home’s share of net worth for heirs. However, these tactics require careful legal and financial planning to avoid capital gains triggers or gift tax issues.
Q: What’s the optimal percentage of net worth in a primary residence for financial stability?
Most advisors cap it at 30% to 40% to maintain liquidity. Below 20%, you may be underutilizing leverage (if you have a mortgage) or missing out on wealth-building potential. Above 50%, you risk illiquidity and market exposure—a single downturn could force a fire sale. The sweet spot varies by age: younger households can afford higher percentages (due to mortgages), while retirees should aim for under 40% to preserve options. The key is regularly reassessing the ratio as markets and life stages change.
Q: How does the percentage of net worth in primary residence change during economic recessions?
It spikes for owners and plunges for would-be buyers. During recessions, home prices often drop 10% to 20%, but for homeowners with paid-off mortgages, the home’s share of net worth may temporarily increase as other assets (like stocks) decline faster. Meanwhile, first-time buyers entering the market post-recession often allocate a larger percentage of net worth to down payments due to higher prices, leaving them less diversified. The 2008 financial crisis is a case study: homeowners saw their real estate net worth percentage jump as stock portfolios cratered, while younger generations were priced out entirely, delaying homeownership and keeping their home-related net worth near zero for years.
