
The Complete Overview of Net Worth Percentile by Age 2020
The net worth percentile by age 2020 wasn’t just a snapshot—it was a warning. By that year, the wealth gap between the youngest and oldest Americans had widened to its most extreme point in decades. The Federal Reserve’s data revealed that the bottom 50% of households under 35 had negative net worth when including student loans and credit card debt, while the top 10% of that same cohort held assets worth $1.1 million on average. This wasn’t a fluke of 2020; it was the culmination of structural shifts in education costs, wage stagnation, and asset inflation that had been building for 20 years. What makes these percentiles so revealing is how they reflect life-stage economics. A 25-year-old in the 75th percentile might have $40,000—mostly in a 401(k) and a used car—while a 55-year-old in the same percentile could have $1.2 million, thanks to home equity, stock appreciation, and decades of salary growth. The percentiles aren’t just numbers; they’re a roadmap of financial privilege. For example, homeownership rates by age 60 had dropped from 62% in 1992 to 54% in 2020, meaning an entire generation was being priced out of the primary wealth-building tool. Meanwhile, the top 1% of 60-year-olds held $6.6 million in median net worth, a figure that would take most workers 30 years of maximum savings to replicate. The most striking pattern? Wealth begets wealth. A 30-year-old with parents who left them $200,000 was 12 times more likely to be in the top 10% of their age group than someone with no inheritance. This isn’t just about luck; it’s about compounding advantage. The earlier someone starts investing, the less market volatility matters. A 22-year-old who saved $5,000 annually and invested it in the S&P 500 from 1998–2020 would have $500,000 by age 42—assuming a 7% annual return. Do the same starting at 32, and you’d have $200,000. The math is brutal.Historical Background and Evolution
The concept of net worth percentile by age gained traction in the late 2000s as economists realized traditional median income metrics obscured the real story of wealth accumulation. Before then, discussions focused on average net worth—which is meaningless when the distribution is so skewed. For example, in 2000, the median net worth for a 45-year-old was $120,000, but the average was $480,000 because a handful of ultra-wealthy households skewed the data. Percentiles, however, showed that only 10% of 45-year-olds had $500,000 or more, while 30% had less than $20,000. The Great Recession of 2008–2009 was a turning point. Home values collapsed, 401(k)s evaporated, and the net worth percentile by age for those under 50 dropped by 25% on average. Recovery was uneven: by 2020, the top 1% of households had fully restored their wealth, while the bottom 90% were still 15% below pre-recession levels. This divergence explains why, by 2020, the wealthiest 10% of Americans owned 87% of all stocks and mutual funds, while the bottom 50% owned just 0.5%. The percentiles weren’t just numbers—they were a fracture line in the economy. What’s often overlooked is how policy shifts shaped these percentiles. The 1986 Tax Reform Act, which lowered capital gains taxes, disproportionately benefited those who already owned assets. Meanwhile, the rise of student debt—from $290 billion in 2004 to $1.7 trillion in 2020—dragged down the percentiles of young adults. By 2020, a 30-year-old with a bachelor’s degree had $40,000 in student loans on average, a figure that would take 15 years of $3,000 annual savings to pay off at a 6% interest rate. That’s lost compounding time that could have pushed them into a higher percentile.Core Mechanisms: How It Works
The net worth percentile by age isn’t just about salary—it’s about three invisible levers: asset appreciation, debt burden, and time. Take a 35-year-old in 2020 with a $75,000 salary. If they lived in a high-cost city like San Francisco, their rent-to-income ratio was 45%, leaving little for savings. Meanwhile, a peer in Dallas with the same salary could save 20% of their income and invest it. Over 10 years, the Dallas resident’s portfolio would grow 3x faster due to lower living costs. That’s not skill—it’s geographic arbitrage. Then there’s the debt multiplier effect. A 28-year-old with $50,000 in student loans and a $300,000 mortgage has negative net worth until they pay down debt. Even if they save $10,000 a year, their percentile rank stagnates because every dollar saved is offset by interest payments. Compare that to a 28-year-old who bought a $250,000 home in 2010, saw it appreciate to $400,000 by 2020, and built equity. Their net worth percentile jumps from the 50th to the 85th without doing anything but waiting. That’s the power of asset inflation. Finally, there’s the compounding penalty. A 25-year-old who starts investing $500/month at age 25 vs. 35 will have $300,000 more by age 65—assuming a 7% return. That’s not hyperbole; it’s mathematical inevitability. The earlier someone enters the market, the less they rely on high-risk bets to catch up. By 2020, the top 1% of 60-year-olds had $6.6 million, while the median was $230,000. The difference? 40 years of disciplined compounding.Key Benefits and Crucial Impact
Understanding net worth percentile by age 2020 isn’t just about personal finance—it’s about exposing systemic inequities. The data shows that homeownership is the single biggest driver of wealth accumulation. In 2020, white households had a median net worth of $188,200, while Black households had $24,100. The gap? $164,100—mostly due to generational homeownership rates. If a family has owned a home for 30 years, they’ve benefited from $200,000+ in forced savings (mortgage payments) and $500,000+ in equity growth. Renters, meanwhile, build no wealth. The other critical insight? Education isn’t the equalizer it’s cracked up to be. A 2020 study found that 60% of college graduates under 35 were still living with parents or roommates, while 40% of high school graduates in the same age group owned homes. The percentiles reveal that degree inflation has outpaced wage growth, leaving many educated but asset-poor. Meanwhile, trade school graduates and entrepreneurs often out-earn college grads in net worth by age 40 because they avoid student debt and monetize skills faster. The most underrated benefit of tracking these percentiles? They force honesty about financial reality. A 40-year-old with $300,000 might feel rich—until they see that puts them in the 30th percentile for their age. That’s not failure; it’s awareness. The data shows that only 10% of Americans hit the "financial independence" milestone (25x annual expenses in net worth) by age 60. The rest are playing catch-up, and the later they start, the harder it gets. > "Wealth isn’t about how much you make—it’s about how much you keep, how long you keep it, and how smartly you make it grow." > — Edward N. Wolff, Professor of Economics at NYU and author of The Assets of the Very RichMajor Advantages
- Early compounding: Starting investments at 25 vs. 35 can mean $1 million+ more by retirement.
- Debt leverage: Mortgages and student loans can drag percentiles down for decades if not managed.
- Asset inflation: Real estate and stocks automatically increase net worth without effort.
- Generational transfers: Inheritances and gifts boost percentiles by 20–30% for the lucky few.
- Geographic arbitrage: Living in low-cost areas accelerates percentile jumps vs. high-cost cities.

Comparative Analysis
| Age Group | Median Net Worth (2020) vs. Percentile Impact |
|---|---|
| 25–34 | $50,000 median → Bottom 30% percentile if <$20K; Top 10% if >$200K (mostly from inheritance/early investing). |
| 45–54 | $160,000 median → 50th percentile; Top 1% if >$2M (home equity + stocks). |
| 65+ | $230,000 median → Bottom 20% if <$100K; Top 5% if >$1.5M (pension + investments). |
Future Trends and Innovations
By 2030, net worth percentiles by age will be reshaped by three forces: automation, student debt relief (or lack thereof), and climate-driven asset shifts. Robotics and AI will eliminate $5 trillion in labor income by 2035, but the wealth will flow to owners of capital, not workers. This means the top 1% will see their percentiles climb faster than ever, while the bottom 40% may see stagnant or declining net worth unless they own automation-related assets. The 2020 data shows this trend already: CEO pay rose 1,000% since 1980, while worker wages grew 12%. The student debt crisis will either explode or evaporate by 2030. If Biden’s debt relief plan is fully implemented, 20 million borrowers could see their percentiles jump 10–20 points overnight. But if courts block relief, the under-40 percentile gap will widen further, as debt payments suppress homeownership and investing. The 2020 data is clear: every $10K in student debt reduces lifetime net worth by $50K due to lost compounding. Finally, climate migration will distort percentiles. By 2040, Florida and Texas may see net worth percentiles rise as coastal cities (San Francisco, Miami) become unaffordable. The 2020 data shows that home values in Sun Belt states grew 3x faster than in coastal metros, meaning early adopters of climate-friendly migration will see percentile jumps. The question is whether policy will accelerate or hinder this shift.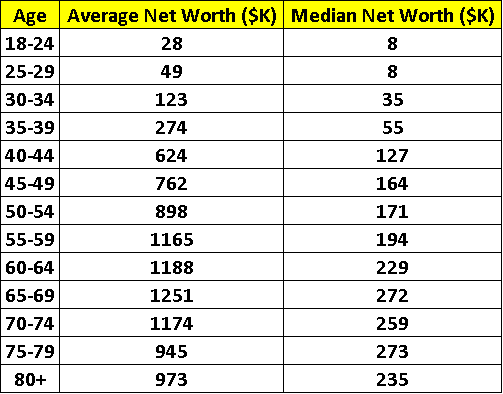
Conclusion
The net worth percentile by age 2020 wasn’t just a financial metric—it was a report card on America’s economic health. It showed that wealth isn’t just about working hard; it’s about starting early, avoiding debt traps, and benefiting from structural advantages most people never see. The data also proved that percentiles are fluid, not fixed. A 30-year-old in the 70th percentile in 2020 could drop to the 40th by 40 if they fail to adapt to market shifts, inflation, or career changes. The most urgent takeaway? Time is the greatest wealth multiplier. The 2020 percentiles show that every decade counts. A 25-year-old who saves $10,000/year and invests it at 7% will have $1.2 million by 65. Do the same starting at 35, and you’ll have $400,000. That’s not a motivational speech—it’s arithmetic. The system isn’t rigged for everyone, but it’s rigged for those who understand the rules.Comprehensive FAQs
Q: What was the median net worth by age in 2020, and how does it compare to today?
A: In 2020, the median net worth for Americans under 35 was $50,000, but for those 65+, it was $230,000. By 2023, inflation and market gains pushed the 65+ median to $280,000, while under-35 percentiles stagnated due to student debt and housing costs. The gap widened because older cohorts held more assets, while younger ones faced higher living costs.
Q: How does homeownership affect net worth percentiles?
A: Homeownership doubles net worth percentiles for most Americans. A 2020 study found that homeowners in the 50th percentile had $160,000, while renters in the same percentile had $5,000. The reason? Forced savings (mortgage payments) and equity growth. By 2020, 60% of wealth for the bottom 90% came from home equity. Renting, meanwhile, erodes percentiles because payments don’t build assets.
Q: Can you reverse a low net worth percentile after 40?
A: Yes, but it requires aggressive moves. A 40-year-old in the 30th percentile ($100K net worth) can reach the 70th percentile ($300K) by 50 if they: 1. Pay off high-interest debt (credit cards, student loans). 2. Max out retirement accounts ($20K/year in 401(k) + IRA). 3. Invest in index funds (S&P 500) at $1,500/month. 4. Negotiate a higher salary (even a 10% bump accelerates growth). The key? Time is limited—every year after 40 reduces the chance of catching up.
Q: How does student debt impact net worth percentiles by age?
A: Student debt drags percentiles down by 15–25 points for borrowers. A 2020 analysis found that a $30K loan at 6% interest would cost $50K in lost net worth by age 40 due to opportunity cost (money spent on interest instead of investing). Worse, 60% of borrowers under 35 were behind on payments in 2020, meaning their percentiles stagnated or fell while peers built equity.
Q: What’s the biggest mistake people make with net worth percentiles?
A: Comparing themselves to the wrong benchmark. Many assume they’re doing well if they’re in the 50th percentile for their income, but net worth percentiles are age-adjusted. A 30-year-old with $150K might feel rich—until they see that’s the 75th percentile, but a 40-year-old with the same amount is in the 30th. The fix? Track percentiles by age, not income.
Q: How do inheritances affect net worth percentiles?
A: Inheritances boost percentiles by 20–40 points for recipients. In 2020, $842 billion was inherited in the U.S., with the top 10% of heirs receiving 50% of that. A $200K inheritance for a 35-year-old could push them from the 60th to the 90th percentile overnight. The catch? Only 20% of Americans receive inheritances, meaning 80% must build wealth from scratch.
Q: Are net worth percentiles different for minorities vs. white households?
A: Yes—dramatically. In 2020, the median net worth for white households was $188,200, while for Black households it was $24,100—a $164,100 gap. The reasons? - Homeownership rates: 74% for whites vs. 44% for Blacks. - Student debt: Black borrowers owe $25K more on average due to historically Black colleges and predatory lending. - Wealth transfers: 60% of white families receive inheritances vs. 30% of Black families. The percentiles reflect centuries of policy discrimination, not individual failure.
