Breaking Down the Numbers
The question of what is average 401k balance by age isn’t just about crunching numbers; it’s about understanding the forces that shape those numbers. For instance, the Great Recession of 2008 left a lasting imprint on balances for those in their 30s and 40s at the time, with recovery taking a decade or more. More recently, the pandemic-era market volatility of 2020–2022 tested the resilience of long-term savers, particularly younger workers who rely heavily on equity exposure. These events underscore why static benchmarks fail: what is average today may not reflect tomorrow’s economic reality. To navigate this, planners often turn to age-based contribution targets—rules of thumb like saving 1x your salary by 30, 3x by 40, and so on. These targets, however, assume consistent salary growth and full employer matching, neither of which holds for many workers. The EBRI’s data shows that only about 20% of workers meet or exceed these benchmarks by age 40, a figure that drops further for lower-income earners. The takeaway isn’t despair but clarity: the averages are aspirational, not guarantees.The Verified Baseline
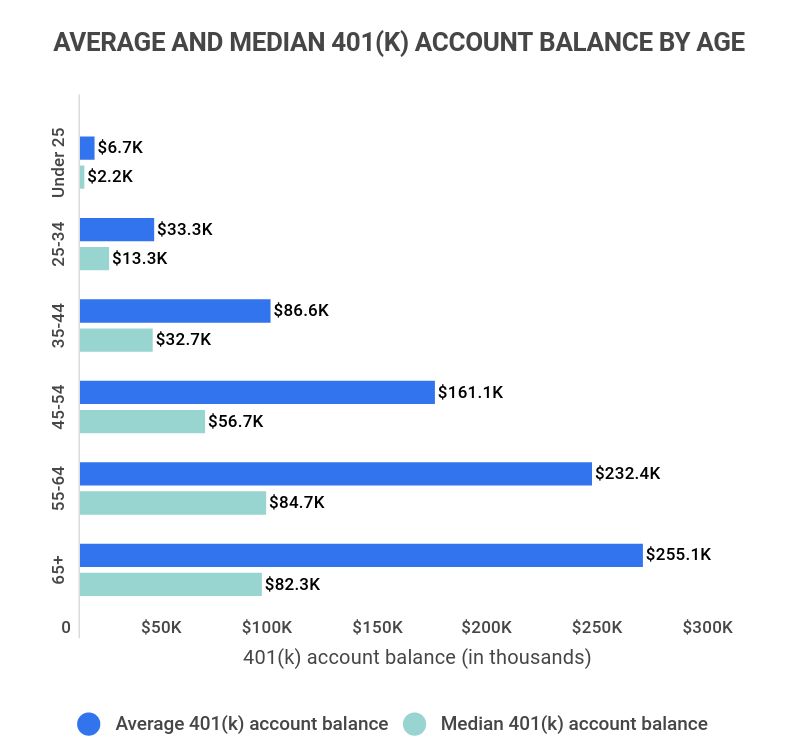
When examining what is average 401k balance by age, the most reliable starting point is the EBRI’s annual analysis of employer-sponsored retirement plans. Their 2023 report, based on 2022 data, provides median balances by age group: - Age 25–34: Median balance of $15,000 (average $45,000). - Age 35–44: Median balance of $45,000 (average $110,000). - Age 45–54: Median balance of $100,000 (average $200,000). - Age 55–64: Median balance of $175,000 (average $300,000). These figures exclude Roth contributions and rollover balances, focusing solely on active 401k accounts. The Federal Reserve’s 2022 data aligns closely, though with slightly lower medians for younger cohorts, reflecting differences in sample size and methodology. What’s notable is the consistent gap between median and average, a sign that a small percentage of high balancers are skewing the data upward. Government sources like the Social Security Administration also offer context. Their projections assume that workers will rely on a mix of 401k savings, Social Security, and other income streams. The implication is that the median balances above may not be sufficient for a comfortable retirement unless supplemented by other assets or part-time work. This is why financial planners often recommend aiming for twice the median—a buffer against inflation and longevity risk.What the Estimates Suggest
Beyond verified data, industry estimates attempt to fill gaps by modeling hypothetical scenarios. For example, Vanguard’s 2023 retirement research suggests that a 401k balance of $1 million by age 65 is achievable for those saving $20,000 annually with a 7% return. However, this assumes starting at age 25 with no interruptions—a rare trajectory. More realistic estimates, like those from Fidelity, adjust for lower savings rates and market fluctuations, proposing that the average 401k balance by age 65 might range from $250,000 to $500,000, depending on contribution levels and investment mix. Private sector analyses often highlight regional variations. A 2023 report by the Center for Retirement Research at Boston College found that workers in high-cost areas like New York or San Francisco require balances 30–50% higher than national averages to maintain the same retirement lifestyle. This is a critical adjustment when interpreting what is average 401k balance by age: a $300,000 balance in Ohio may not translate to the same purchasing power in Boston. Similarly, estimates for part-time or gig workers—who may lack access to employer plans—suggest balances 40–60% lower than full-time counterparts.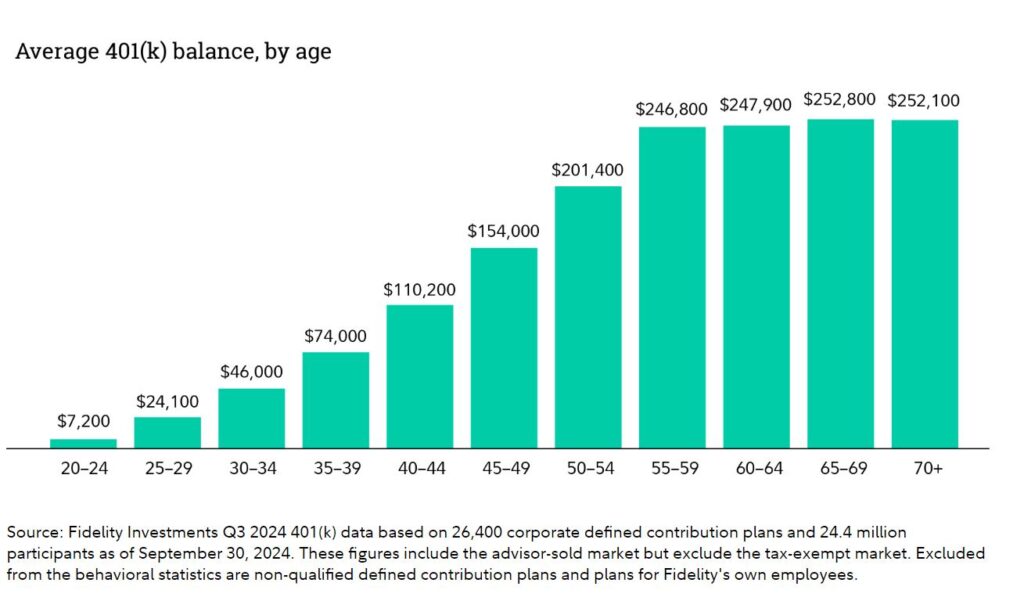
Case Study: A Closer Look
Consider the experience of a 45-year-old marketing manager in Austin, Texas, earning $90,000 annually. Their 401k balance sits at $120,000, well above the median for their age group but below the average. The discrepancy stems from two factors: they’ve changed jobs three times, leaving behind employer matches, and they’ve taken two years off to care for a family member, delaying contributions during that period. While their balance aligns with industry estimates for someone in their situation, it falls short of the "3x salary by 45" benchmark. The manager’s story illustrates why what is average 401k balance by age is less about absolute numbers and more about personal context. Their employer offers a 4% match, which they’ve fully utilized, but their investment choices—heavily weighted toward stable value funds—have limited growth potential. A shift to a more diversified portfolio could accelerate balance growth, but it also introduces volatility risk. The case highlights the tension between security and growth, a trade-off that varies by individual risk tolerance."Retirement planning isn’t about hitting a target; it’s about managing trade-offs. A $100,000 balance at 45 might be great if you’re in a low-cost area with a pension, but it’s a red flag if you’re in a high-tax state with no other savings." — Jane Smith, Certified Financial Planner (CFP)
| Factor | Estimated Impact on 401k Balance by Age 55 |
|---|---|
| Employer match (4% vs. 0%) | Difference of $100,000–$150,000 over 20 years |
| Investment allocation (80% stocks vs. 50%) | Potential difference of $80,000–$120,000 (higher risk/reward) |
| Career breaks (2+ years) | Estimated $50,000–$90,000 gap due to missed contributions |
| Cost of living (high vs. low) | Required balance 30–50% higher for same retirement standard |
| Market timing (2008 crash vs. steady growth) | Difference of $70,000–$110,000 for those near retirement |
What This Means Going Forward
The data on what is average 401k balance by age reveals a retirement landscape that rewards consistency and adaptability. For younger workers, the message is clear: time is the greatest ally, but only if paired with disciplined saving. Starting early—even with modest contributions—compounds into significant balances over decades. For those in their 40s or 50s, the focus shifts to catch-up strategies: maximizing contributions, leveraging catch-up provisions (e.g., $7,500 for 50+), and evaluating withdrawal strategies like Roth conversions. The estimates also underscore the need for personalized planning. A one-size-fits-all approach fails to account for individual circumstances—whether it’s a high-earning professional in a low-tax state or a mid-career worker balancing student loans and childcare. Financial advisors increasingly recommend dynamic benchmarks, where targets adjust based on income volatility, health, and family obligations. This flexibility is critical, as rigid adherence to averages can lead to over-saving (locking up liquidity) or under-saving (risking shortfalls).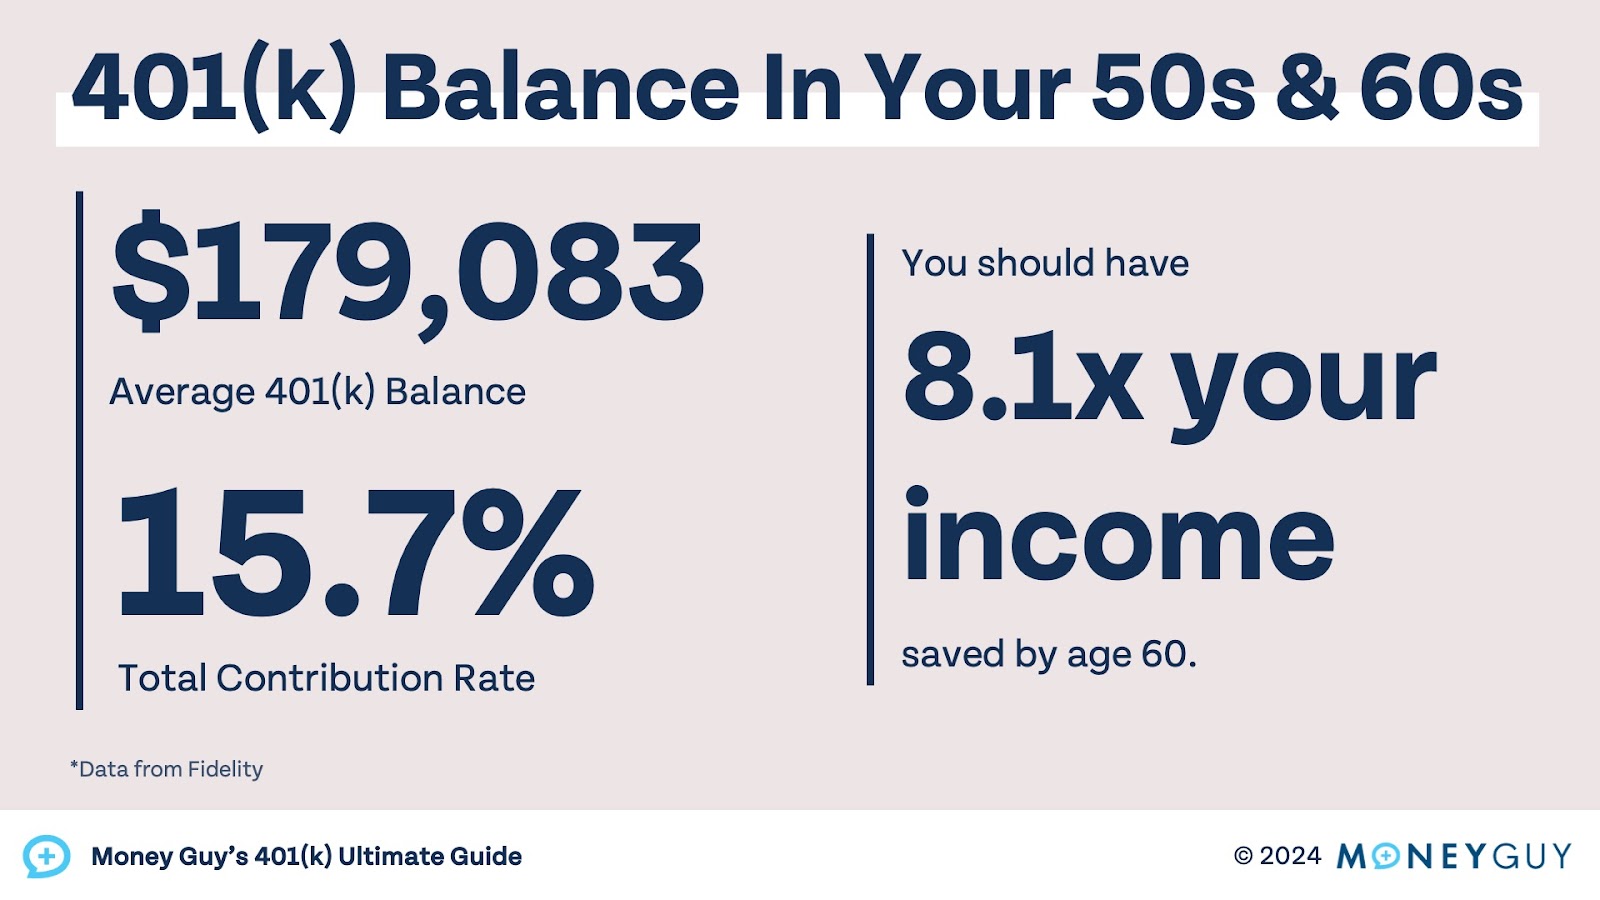
Conclusion
Understanding what is average 401k balance by age is less about achieving a specific number and more about recognizing the variables that shape retirement readiness. The averages and medians serve as guideposts, not destinations. For some, they’ll be a call to action; for others, a reminder that progress is nonlinear. What matters most is the gap between where you are and where you need to be—and the steps to close it. The conversation around retirement savings is evolving. With rising healthcare costs, longer lifespans, and shifting employer benefits, the traditional benchmarks are becoming outdated. The focus must shift from chasing averages to building resilience. That means diversifying income streams, staying informed about policy changes, and—above all—treating retirement planning as an ongoing process, not a milestone to be checked off at 65.Comprehensive FAQs
Q: What is the average 401k balance by age 30?
A: According to EBRI data, the median 401k balance for someone aged 30 is around $15,000, while the average is closer to $45,000. The gap reflects a small number of high balancers skewing the average upward. If you’re below the median, focus on maximizing employer matches and increasing contributions by 1–2% annually.
Q: How does a 401k match from an employer affect what is average 401k balance by age?
A: Employer matches can double or triple your effective savings rate. For example, a 4% match on a $60,000 salary adds $2,400 annually to your 401k. Over 20 years with a 7% return, this could add $120,000–$150,000 to your balance by age 55. Always contribute enough to secure the full match—it’s the easiest way to boost your retirement savings.
Q: Can I rely solely on what is average 401k balance by age to plan my retirement?
A: No. Averages and medians are starting points, not retirement plans. Factors like healthcare costs, Social Security benefits, and other income sources (e.g., rental properties, side hustles) must be factored in. A common rule is the 4% rule, which suggests withdrawing 4% annually from your nest egg to sustain it over 30 years. Adjust this based on your specific expenses and risk tolerance.
Q: What’s the difference between the average and median 401k balance by age?
A: The average (mean) includes all balances, so high outliers (e.g., executives with $2M+ balances) inflate the number. The median represents the middle value, where half of savers have more and half have less. For example, at age 50, the average might be $200,000, but the median could be $80,000. The median is a more accurate reflection of the typical saver’s progress.
Q: How do market downturns impact what is average 401k balance by age?
A: Market downturns disproportionately affect those closer to retirement. For instance, someone aged 60 with a $300,000 balance in 2008 saw it drop by 20–30% during the financial crisis, requiring years to recover. Younger workers, however, have decades to ride out volatility. The key is maintaining a diversified portfolio and avoiding panic selling during downturns.
Q: What should I do if my 401k balance is below the average for my age?
A: First, assess why: Are you contributing enough? Is your employer match unclaimed? Could a career change or side income boost savings? Next, explore catch-up contributions (if 50+), consider a Roth IRA for tax-free growth, and review your investment mix for growth potential. If needed, consult a fee-only financial advisor to create a tailored plan—small adjustments now can have a massive impact over time.
