The Complete Overview of Net Worth Adverse Selection
Net worth adverse selection isn’t a theoretical abstraction—it’s a live wire running through global finance. The term captures how markets, by design or default, favor participants with deep pockets while penalizing those with modest means. This isn’t about skill or opportunity; it’s about the raw asymmetry of capital. When a family office can commit $100 million to a startup’s Series B round, it doesn’t just dilute other investors—it alters the valuation multiples, the board composition, and the exit strategy. The result? A market where the richest players don’t just win—they reshape the game itself. The distortion extends beyond investment. In luxury real estate, for instance, the highest-end properties often require buyers to prove liquid net worth, not just borrowing capacity. This creates a feedback loop: the wealthiest buyers drive up prices, making it harder for new entrants to accumulate the same assets. The same logic applies to art auctions, where consignors with deep pockets set reserve prices that exclude all but the most affluent collectors. Even in philanthropy, the ultra-wealthy’s ability to move capital at scale allows them to dictate which causes receive funding—and which don’t.Historical Background and Evolution
The roots of net worth adverse selection trace back to the early 20th century, when regulatory frameworks began distinguishing between "accredited" and "non-accredited" investors. The Securities Act of 1933 introduced the concept of "sophisticated investors," a category that implicitly favored those with significant wealth. Over time, this evolved into a formalized exclusion: the $1 million net worth threshold (adjusted for inflation) that still governs access to private markets today. The logic was simple—wealthier investors were assumed to be more informed, less likely to panic, and better equipped to absorb risk. By the 1980s, the rise of private equity and venture capital accelerated the problem. Fund managers realized that the ability to deploy capital at scale gave them leverage—not just in negotiations, but in defining the terms of entire industries. The 1990s tech boom amplified this further, as Silicon Valley’s elite investors (many with net worths in the hundreds of millions) began structuring deals where their participation was a prerequisite for others. The result? A system where the ultra-wealthy didn’t just invest—they controlled the investment thesis itself.Core Mechanisms: How It Works
At its core, net worth adverse selection operates through three interlocking mechanisms: capital concentration, information asymmetry, and structural exclusion. Capital concentration occurs when a small group of high-net-worth individuals or institutions hold disproportionate stakes in an asset class. This isn’t just about ownership—it’s about influence. When a single family office commits $200 million to a sector, it doesn’t just move the market; it sets the narrative, the valuation benchmarks, and even the exit strategy. Information asymmetry compounds the effect. The ultra-wealthy have access to proprietary data, exclusive deal flow, and direct relationships with founders and regulators. This creates a feedback loop: because they have more information, they make better-informed decisions, which in turn reinforces their dominance. Meanwhile, retail investors—even those with deep expertise—are often shut out of the same opportunities due to regulatory or structural barriers. Structural exclusion is the final piece. From minimum investment thresholds to "key person" clauses in private placements, the system is designed to favor those who can deploy capital at scale. This isn’t accidental—it’s a feature. The higher the net worth requirement, the more the market skews toward the wealthy, creating a self-reinforcing cycle where the rich get richer, and everyone else is left behind.Key Benefits and Crucial Impact
For the ultra-wealthy, net worth adverse selection is a double-edged sword—it concentrates power, but it also creates vulnerabilities. On one hand, the ability to deploy capital at will allows them to dictate market trends, capture first-mover advantages, and shape entire industries. On the other, this dominance comes with risks: overconcentration can lead to systemic instability, as seen in the 2008 financial crisis, where the collapse of a few heavily leveraged institutions nearly brought down the global economy. The broader impact is more insidious. By tilting markets toward the wealthy, net worth adverse selection deepens inequality, reduces economic mobility, and distorts innovation. When capital allocation becomes a function of pre-existing wealth rather than merit or potential, the system rewards the wrong behaviors—hoarding, speculation, and short-termism over long-term value creation."Adverse selection isn’t just about who gets in—it’s about who gets to set the rules. And in finance, the rules are increasingly being written by those who already have the most to gain." — Economist and former SEC regulator, speaking on private market dynamics
Major Advantages
For those at the top of the wealth pyramid, the advantages are clear:- Leverage in negotiations: The ability to commit large sums allows high-net-worth investors to dictate terms, from valuation multiples to board seats.
- Access to exclusive opportunities: Private equity, venture capital, and luxury assets are often structured to favor those with deep pockets, creating a self-reinforcing cycle.
- Information dominance: Wealthier participants have superior access to data, deal flow, and industry insights, further entrenching their advantage.
- Regulatory arbitrage: The ultra-wealthy can navigate complex financial structures—from offshore entities to special purpose vehicles—with relative ease, while smaller players face higher compliance costs.
Comparative Analysis
| Aspect | Net Worth Adverse Selection | Traditional Adverse Selection |
|---|---|---|
| Primary Driver | Wealth concentration and capital deployment | Information asymmetry (e.g., used car buyers vs. sellers) |
| Market Impact | Structural exclusion of non-wealthy participants; skews asset allocation toward the ultra-rich | Individual transactions distorted by hidden information (e.g., lemon problem in used cars) |
| Regulatory Response | Accredited investor rules, minimum investment thresholds, private placement exemptions | Disclosure requirements, warranties, third-party certifications |
Future Trends and Innovations
The next decade will likely see net worth adverse selection evolve in two directions: further entrenchment and potential disruption. On one hand, the rise of alternative assets—from cryptocurrencies to private credit—will create new avenues for the ultra-wealthy to deploy capital, deepening the divide. On the other, technological innovations like blockchain-based fractional ownership and AI-driven investment platforms could democratize access—but only if regulators and market structures adapt to reduce barriers. One wild card is the growing backlash against wealth concentration. As public sentiment shifts toward economic fairness, we may see pressure on governments to reform accredited investor rules, lower minimum investment thresholds, or introduce new mechanisms to level the playing field. However, the inertia of the status quo is formidable—change will likely be incremental, not revolutionary.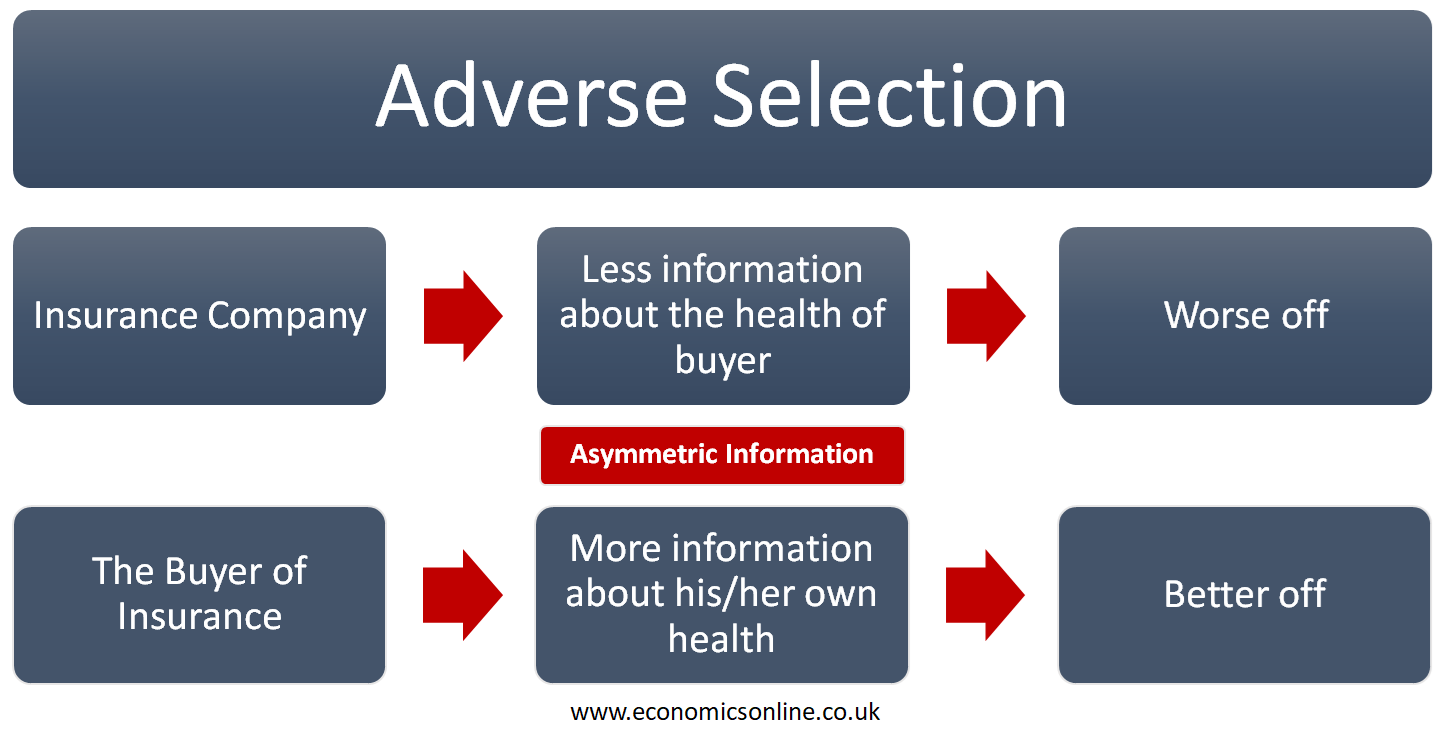
Conclusion
Net worth adverse selection isn’t a bug in the system—it’s a feature, hardwired into the DNA of modern finance. The ultra-wealthy don’t just benefit from it; they depend on it to maintain their dominance. For everyone else, the consequences are clear: reduced access, deeper inequality, and a financial system that rewards hoarding over creation. The question isn’t whether this dynamic will persist—it will. The real question is whether society will tolerate it, or whether the next generation of investors, regulators, and entrepreneurs will find ways to break the cycle. For now, the system remains rigged—but history suggests that no rigged system lasts forever.Comprehensive FAQs
Q: How does net worth adverse selection differ from traditional adverse selection?
Traditional adverse selection (e.g., the "lemon problem" in used car markets) stems from hidden information between buyers and sellers. Net worth adverse selection, however, is structural—it results from wealth-based exclusion in markets where participation itself is tied to capital deployment. While traditional adverse selection distorts individual transactions, net worth adverse selection skews entire asset classes toward the ultra-wealthy.
Q: Can retail investors mitigate the effects of net worth adverse selection?
Retail investors can reduce exposure by focusing on liquid, regulated markets (e.g., public equities, ETFs) and leveraging platforms that aggregate smaller investments (e.g., crowdfunding, fractional ownership). However, no strategy can fully offset the systemic bias—ultimately, the problem requires structural changes, such as lower minimum investment thresholds or reforms to accredited investor rules.
Q: Are there any industries where net worth adverse selection is less pronounced?
Industries with lower barriers to entry—such as public markets, certain types of real estate (e.g., residential rentals), or peer-to-peer lending—exhibit less extreme versions of the problem. However, even these sectors often have hidden wealth-based biases, such as credit scoring algorithms that favor those with higher net worth or institutional investors with superior liquidity.
Q: How do regulators address net worth adverse selection?
Regulators primarily use two tools: exemption frameworks (e.g., Rule 506 of Regulation D in the U.S., which allows private offerings to accredited investors) and disclosure requirements (e.g., mandating transparency in private placements). However, these measures often reinforce rather than reduce the problem, as they create legal pathways for wealth-based exclusion rather than challenging it.
Q: What role do fintech innovations play in combating net worth adverse selection?
Fintech has the potential to disrupt the status quo by lowering barriers to capital deployment—through fractional ownership, automated investing, or blockchain-based alternatives. However, many fintech solutions still rely on wealth-based filters (e.g., minimum deposit requirements) or are acquired by traditional players who perpetuate the same biases. True disruption would require a shift in business models, not just technology.
Q: Can net worth adverse selection lead to economic instability?
Yes. When capital becomes overly concentrated, it increases the risk of systemic shocks—whether through overleveraged institutions, speculative bubbles, or sudden withdrawals. The 2008 financial crisis, for instance, was exacerbated by the dominance of a few heavily interconnected players. While net worth adverse selection itself doesn’t cause instability, it amplifies the risks when combined with other factors like regulatory arbitrage or liquidity mismatches.
Q: Are there historical examples where net worth adverse selection backfired?
One notable case is the dot-com bubble of the late 1990s, where ultra-wealthy investors and institutional players drove valuations to unsustainable levels—partly because their participation created a false sense of legitimacy. When the bubble burst, many of these same players faced significant losses, demonstrating how overconcentration can lead to systemic fragility. Similarly, the 2021 SPAC frenzy saw wealthy backers and institutional investors dominate, often at the expense of retail participants who entered late and faced higher risks.
