Breaking Down the Numbers
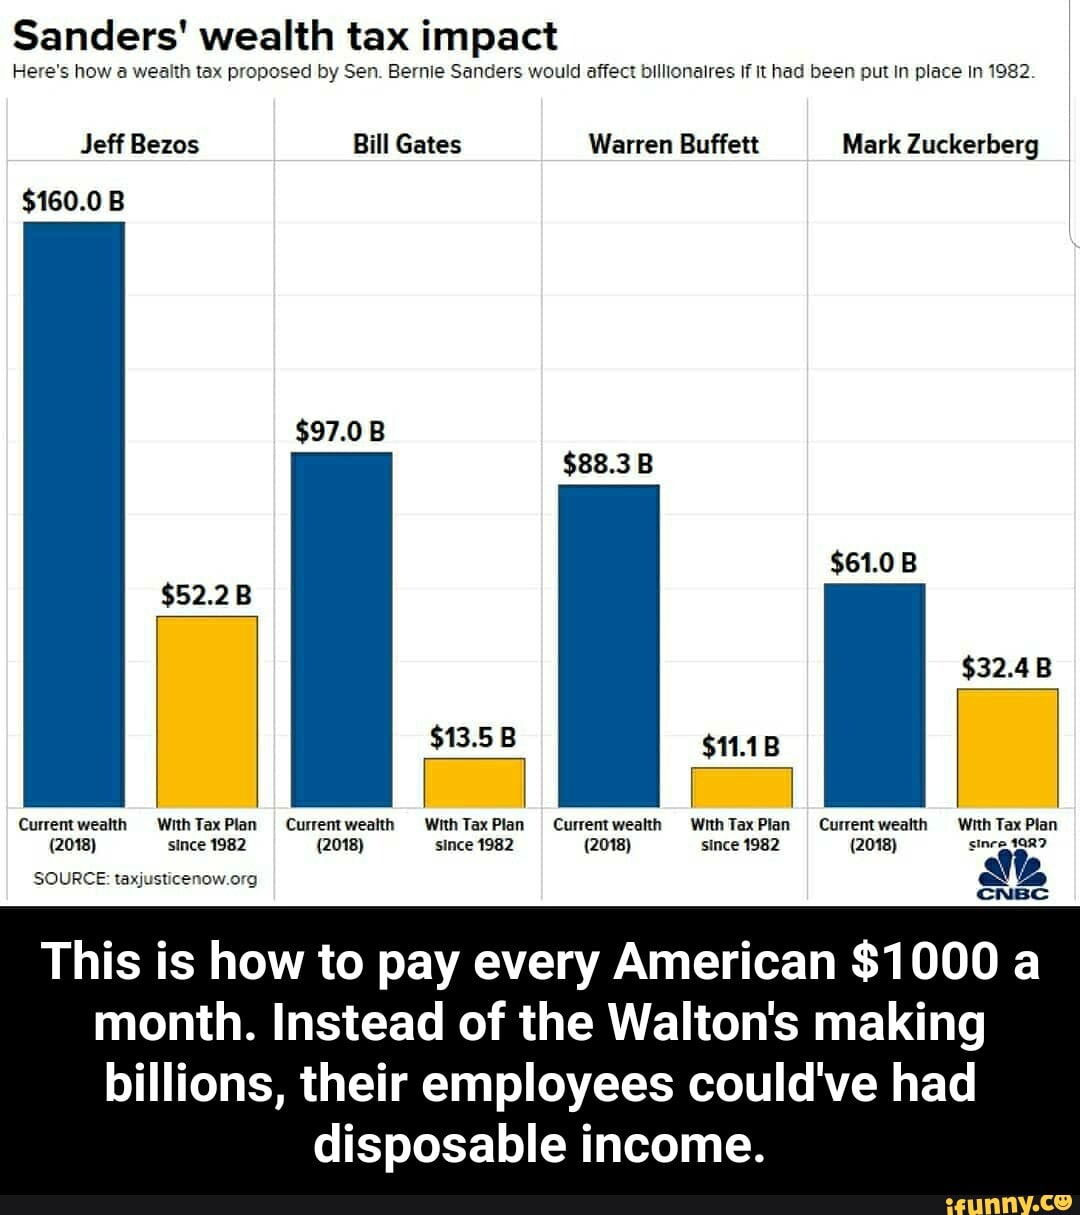
The core premise of taxes taken by net worth is straightforward: the more you own, the more the state expects in return. But the execution varies wildly. In countries like Spain or Switzerland, wealth taxes target liquid assets directly, while jurisdictions like the U.S. rely on capital gains and estate taxes—both of which kick in only after certain thresholds. The European Union’s 2021 proposal to harmonize a minimum corporate tax rate of 15% didn’t address personal wealth taxes, leaving national systems to clash with global capital flows. The disconnect lies in how net worth is defined. Income taxes focus on earnings; wealth taxes target assets. A tech CEO with $500 million in stock options may owe little in payroll taxes but face capital gains liabilities when selling. Meanwhile, a landowner with $10 million in undeveloped property might trigger property taxes or inheritance levies decades later. The system isn’t just regressive—it’s opaque. Without standardized reporting, taxes taken by net worth become a game of audits, declarations, and, increasingly, algorithmic risk assessments by tax authorities.The Verified Baseline
Public data confirms that taxes taken by net worth disproportionately affect the top 1%. In France, the impôt sur la fortune immobilière (IFI) applies to assets over €1.3 million, generating roughly €1.5 billion annually—peanuts compared to the country’s €2.2 trillion GDP, but a political lightning rod. The U.S. federal estate tax exempts the first $12.92 million per individual (2023), meaning only the top 0.2% of estates face levies. Even then, valuation disputes over art, private equity, or family businesses drag cases through courts for years. What’s verifiable is the scale of avoidance. The Panama Papers and Pandora Files revealed that wealth managers routinely structure holdings in tax havens to defer or eliminate taxes taken by net worth. A 2022 OECD report estimated that global tax revenues lost to offshore schemes exceed $483 billion annually—equivalent to the GDP of Sweden. The problem isn’t just evasion; it’s jurisdictional arbitrage. A Russian oligarch might park yachts in Monaco, a Silicon Valley founder in Singapore, and a European aristocrat in Liechtenstein, each move legally reducing exposure to taxes taken by net worth in their home countries.What the Estimates Suggest
Industry estimates paint a more nuanced picture. According to the Tax Justice Network, the world’s 500 richest individuals paid an effective tax rate of just 0.004% in 2020—far below the average worker’s burden. This isn’t due to loopholes alone but to asset class advantages. Real estate appreciates slowly (taxed at lower long-term rates), private equity is often deferred until exit, and family trusts shield intergenerational transfers. Even in progressive systems like Denmark, where top income taxes hit 55%, wealth taxes are capped at 2.5%—a fraction of the potential yield. The real outlier? Taxes taken by net worth in emerging markets. Brazil’s Imposto sobre Grandes Fortunas (IGF) was scrapped in 2022 after collecting a mere $1.2 billion in its final year—less than 0.1% of GDP. Meanwhile, China’s wealth taxes are rare, with local governments relying on property levies that hit urban homeowners harder than rural landowners. The pattern is clear: taxes taken by net worth are politically toxic unless they’re framed as "fairness for the many," but enforcement requires resources most governments lack.
Case Study: A Closer Look
Consider the case of a European tech founder who sold their company for €500 million in 2020. Under French law, capital gains on assets held over a year are taxed at 30% (12.8% income tax + 17.2% social charges), but the founder structured the sale through a Dutch holding company. The result? Only €100 million was repatriated to France, deferring taxes taken by net worth for a decade via treaty exemptions. Meanwhile, the founder’s private jet—purchased in Monaco—was leased back to the company, further reducing taxable income. The founder’s defense? "We’re optimizing, not evading." The distinction matters in court. A 2021 French court upheld a €200 million tax bill against a luxury goods heir who had moved assets to Luxembourg, ruling that the transfers lacked "economic substance." But the case dragged on for five years, costing the heir millions in legal fees—taxes taken by net worth, in this case, were paid in blood, sweat, and delay.| Factor | Estimated Impact on Taxes Taken by Net Worth |
|---|---|
| Asset Location (Monaco/Dutch Holding) | Deferred €150M+ in capital gains for 10+ years |
| Private Jet Leasing | Reduced taxable income by ~€5M annually |
| Family Trust Structures | Shielded €300M in intergenerational transfers |
| Legal Fees & Audits | €10M+ in indirect costs (opportunity + direct) |
What This Means Going Forward
The trend is clear: taxes taken by net worth are becoming more complex, not simpler. The EU’s 2023 proposal to tax billionaires’ unrealized gains is a step toward closing the gap, but it faces resistance from countries like Ireland and Luxembourg, which rely on low-tax regimes to attract capital. Meanwhile, the U.S. Inflation Reduction Act’s 15% corporate minimum tax won’t touch personal wealth—leaving the ultra-rich to exploit the same structures that have worked for decades. The real shift may come from data transparency. The OECD’s global minimum tax deal requires multinational firms to disclose profits by jurisdiction, but personal wealth remains a black box. If tax authorities could cross-reference bank accounts, property records, and crypto holdings in real time, taxes taken by net worth would become far harder to dodge. The question isn’t whether this will happen—it’s whether governments have the political will to enforce it.
Conclusion
Taxes taken by net worth aren’t just about money; they’re about power. The ultra-rich don’t just pay more—they shape the rules that determine how much they pay. From trusts to treaty shopping, the tools of avoidance are as sophisticated as the systems designed to catch them. The result is a two-tiered fiscal reality: the many pay predictably, while the few pay selectively, if at all. The coming decade will test whether democracy can outmaneuver capital. If current trends hold, taxes taken by net worth will remain a luxury good—accessible only to those who can afford to game the system. The alternative? A world where wealth taxes aren’t just about revenue but about reclaiming agency over who gets to keep what they’ve accumulated.Comprehensive FAQs
Q: Can I legally avoid taxes taken by net worth entirely?
A: No, but you can legally defer or reduce them through structures like trusts, offshore entities, or asset location. The line between optimization and evasion is often drawn in court—and enforcement varies by country. What’s legal in Monaco may trigger audits in Paris.
Q: How do wealth taxes differ from income taxes?
A: Income taxes target earnings (salaries, dividends), while taxes taken by net worth target assets (property, stocks, art). The former is annual; the latter can be triggered by sales, inheritance, or even unrealized appreciation in some jurisdictions. Wealth taxes also often exclude retirement accounts or primary residences.
Q: Are there countries with no taxes taken by net worth?
A: No country has zero wealth taxes, but some—like the UAE or Cayman Islands—have zero income tax and minimal capital gains levies. Others, like Switzerland, impose wealth taxes only on residents and at cantonal rates (as low as 0.1%). The trade-off? High living costs or residency requirements.
Q: What’s the most common mistake high-net-worth individuals make with taxes?
A: Assuming taxes taken by net worth are a static burden. Many underestimate the impact of asset class timing (e.g., selling stocks vs. holding real estate) or fail to account for jurisdictional creep—where a change in residency or a new tax treaty can retroactively trigger liabilities. Proactive structuring is key; reactive fixes are expensive.
Q: How might AI change taxes taken by net worth?
A: Tax authorities are already using AI to flag anomalies in taxes taken by net worth declarations—cross-referencing property records, bank transfers, and even social media data to detect discrepancies. On the other side, wealth managers use AI to predict audit triggers and optimize disclosures. The arms race isn’t just legal; it’s algorithmic.
