
The Short Answers
- A higher net worth buys time—the freedom to pursue passions without trading them for income.
- It expands options: better healthcare, education, and geographic mobility without compromise.
- Wealth reduces financial stress, letting you focus on relationships and long-term goals instead of survival.
- At scale, it creates leverage—access to networks, deals, and opportunities closed to those with less capital.
- The real advantage isn’t spending power, but the psychological shift from scarcity to possibility.

Deep Dive: The Full Picture
The benefits of a higher net worth aren’t just about what you can buy; they’re about what you can avoid. For most people, money is a series of trade-offs: cheaper rent means longer commutes, better schools mean smaller homes, and financial security often means sacrificing experiences. When net worth climbs, those trade-offs dissolve. The threshold isn’t fixed—what feels liberating to one person (a home in the suburbs) might be table stakes for another (a primary residence in a global city). But the pattern holds: wealth isn’t freedom until it outpaces your fixed obligations. The second layer is asymmetric access. A net worth of $1 million might get you a second opinion from a top doctor; $10 million might let you join a private equity fund. The difference isn’t just in the services you can afford, but in the doors that open automatically. High-net-worth individuals don’t just pay for things—they’re invited to tables where decisions are made. This isn’t about elitism; it’s about how capital functions as social currency in ways cash alone can’t replicate.The Context You Need
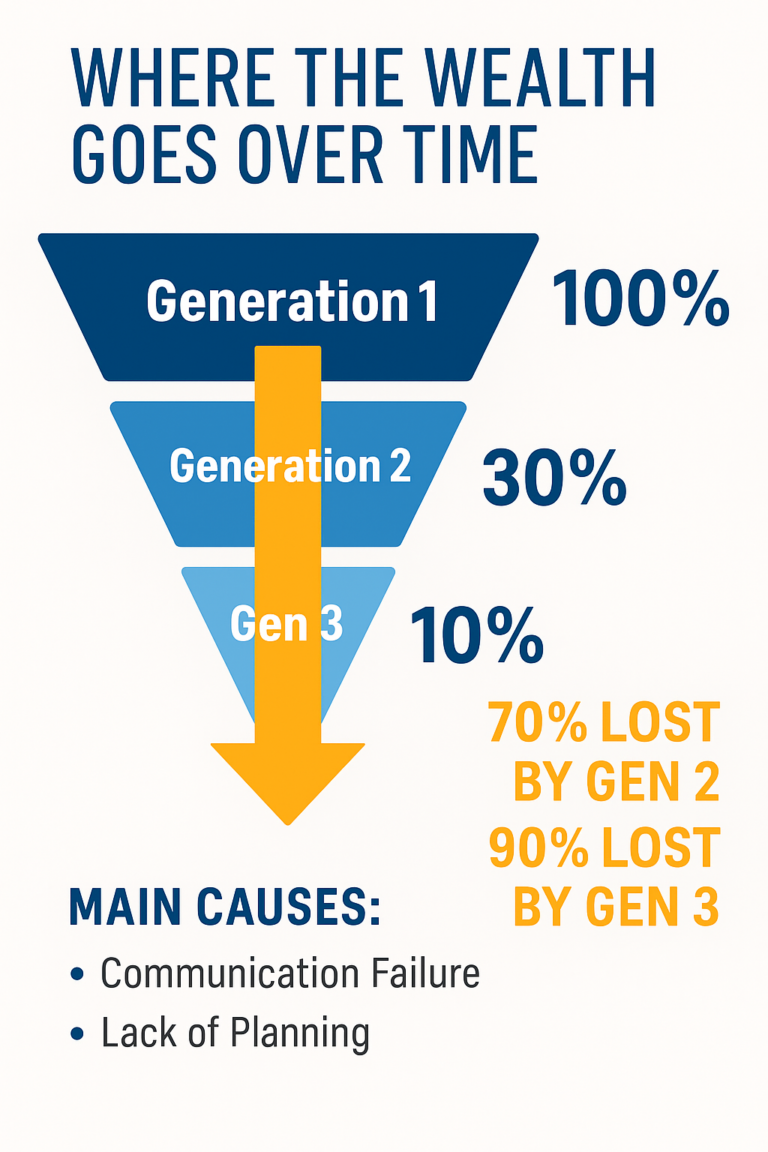
Wealth isn’t distributed evenly, and its benefits aren’t either. Studies show that the top 10% of earners in the U.S. hold roughly 70% of the country’s wealth, while the bottom 50% share less than 3%. The gap isn’t just statistical—it’s experiential. A family earning $150,000 annually might struggle to save for college; one with a net worth of $5 million can write checks for tuition without blinking. The benefits of a higher net worth aren’t just about larger numbers; they’re about structural advantages that accumulate over generations. Yet wealth’s impact varies by stage of life. In your 30s, it might mean avoiding student debt or buying a home without a 20-year mortgage. By 50, the same net worth could fund a sabbatical, a trust for grandchildren, or a pivot to a risky but fulfilling career. The flexibility compounds. A young professional with $200,000 in liquid assets can take a pay cut for a better role; someone with $2 million can afford to walk away from a toxic job entirely. The math changes, but the principle remains: money amplifies agency.The Mechanics
The first mechanical advantage is liquidity. A high net worth isn’t just about assets—it’s about how quickly you can convert them to cash. A tech executive with stock options might have a paper net worth of $50 million, but if those shares are locked up for years, the benefits are theoretical. True financial leverage comes from diversified, liquid holdings: cash reserves, low-cost investments, and assets that can be sold without penalty. This is why ultra-high-net-worth individuals often hold 10–30% of their portfolio in cash or equivalents—not for spending, but for opportunity. The second mechanism is tax efficiency. Wealth begets tax advantages that aren’t available to the middle class. High-net-worth individuals use trusts, private foundations, and offshore accounts (where legal) to minimize liabilities. They also benefit from preferential rates on capital gains, estate planning tools like dynasty trusts, and access to wealth managers who structure deals to avoid ordinary income tax. The IRS doesn’t treat a $10 million portfolio the same as a $100,000 one—and the benefits of a higher net worth include legal arbitrage that keeps more money working for you.Details That Change the Picture
The most underrated benefit of a higher net worth is psychological. Financial stress isn’t just about not having enough; it’s about the constant mental load of tracking bills, negotiating with creditors, or worrying about a single emergency derailing years of progress. Wealth eliminates that noise. A 2018 study by the University of Cambridge found that once basic needs are met, additional income beyond $75,000 annually (adjusted for inflation) contributes little to happiness—but security does. The ability to sleep through a stock market dip or a medical bill knowing you won’t face ruin is priceless. Then there’s the network effect. Wealth attracts like-minded people. High-net-worth individuals don’t just hire better lawyers or doctors—they move in different social circles. A real estate developer with a $50 million portfolio might rub shoulders with politicians, investors, and artists at private events. A mid-level manager with a $500,000 net worth can’t. The benefits of a higher net worth include access to information, deals, and relationships that aren’t available through public channels. This isn’t about nepotism; it’s about how capital magnifies influence."Money isn’t the root of all evil. It’s the lack of it that forces you to make bad trade-offs every single day." — A former Fortune 500 CFO, speaking anonymously to The Economist in 2022
| Net Worth Threshold | Key Benefit Unlocked |
|---|---|
| $500,000–$1M | Financial independence (FI) if passive income covers living expenses; ability to retire early (FIRE). |
| $2M–$5M | Access to private schools, healthcare concierge services, and real estate with minimal financing. |
| $10M–$50M | Tax optimization via trusts, estate planning, and offshore structures (where legal); entry into elite networks. |
| $50M–$100M | Philanthropic leverage (donor-advised funds, family foundations); ability to influence industries or policy. |
| $100M+ | Generational wealth transfer; access to sovereign wealth funds, private equity, and bespoke legal structures. |
Conclusion
The benefits of a higher net worth aren’t about luxury—they’re about control. It’s the difference between choosing a career you love and one that pays the bills, between aging in place or being forced to downsize, between raising kids in a safe neighborhood or one plagued by crime. Wealth doesn’t solve existential questions, but it removes the distractions that prevent people from asking them. The highest-net-worth individuals don’t spend their time counting money; they spend it on what matters to them. That said, wealth isn’t a panacea. It can insulate you from failure, but it doesn’t guarantee success. A higher net worth might let you take risks, but risks still carry consequences. The real advantage isn’t the money itself, but the mental framework it enables: the ability to think long-term, to prioritize experiences over things, and to build a life on your own terms. For most people, that’s the ultimate benefit—not the yacht in the harbor, but the peace of mind that comes from knowing you’re not one bad decision away from ruin.Comprehensive FAQs
Q: Is there a net worth threshold where the benefits really start to matter?
A: The inflection points vary by country and lifestyle, but $500,000–$1 million is often cited as the range where financial stress begins to lift for most households. Above $2 million, the benefits shift from security to asymmetric access—private healthcare, elite education, and tax advantages that weren’t available before. At $10 million+, the focus moves to generational wealth and influence rather than personal spending.
Q: Can you have a high net worth but still feel poor?
A: Absolutely. Illiquid assets (e.g., a $20 million art collection that can’t be sold quickly) or high fixed costs (e.g., a $5 million home with a $200,000 annual mortgage) can create cash-flow poverty despite a high net worth. Conversely, someone with $1 million in liquid assets and no debt might live more comfortably than someone with $5 million tied up in illiquid real estate. Net worth is a snapshot; cash flow is the reality.
Q: Does a higher net worth really give you more freedom, or is that just a myth?
A: It’s not a myth, but it’s context-dependent. Freedom comes from options, not just money. A net worth of $3 million might let you quit a soul-crushing job, but if you’re saddled with a $1 million mortgage and a $200,000 annual lifestyle, your "freedom" is limited. True financial freedom requires low fixed costs, diversified income, and liquidity. The ultra-wealthy (net worth >$50M) often report feeling more constrained by responsibility—managing trusts, philanthropy, and legacy—but they also have the ability to walk away from anything that doesn’t align with their goals.
Q: Are there downsides to a higher net worth that people rarely talk about?
A: Yes. Social friction is one—wealth can isolate you from people who once considered you a peer. Legal risks increase (e.g., lawsuits, IRS scrutiny). Decision paralysis sets in when you have too many options. And legacy pressure becomes real: Will your kids squander the fortune? Will your wealth create more problems than it solves? The benefits of a higher net worth are real, but they come with unspoken trade-offs that most people only discover after crossing certain financial thresholds.
Q: How does a higher net worth change relationships?
A: Dramatically. Romantic partnerships often shift from equality to power dynamics—money can become a silent partner in decisions. Friendships may thin out as some people feel uncomfortable around wealth, while others become opportunistic. Family dynamics can fracture: siblings may resent an uneven inheritance, or parents might struggle with how to teach their children about money. The benefits of a higher net worth include more opportunities, but they also amplify relational risks. Many ultra-wealthy individuals hire family offices or therapists specifically to manage these tensions.
Q: Is it possible to enjoy the benefits of a higher net worth without being wealthy?
A: Partially. Financial independence (FI)—where passive income covers living expenses—can mimic some benefits (e.g., geographic freedom, reduced stress) without a nine-figure net worth. Strategic debt reduction (e.g., paying off a mortgage early) or asset diversification (e.g., rental properties) can create leverage. However, true high-net-worth advantages—private healthcare, elite networks, tax optimization—require scale. The middle ground is relative wealth: earning enough to live well in your local context while avoiding the pitfalls of extreme inequality.
