
Where It All Began
The modern obsession with "average household net worth by city" traces back to the post-WWII era, when cities became engines of economic recovery. Governments realized that wealth wasn’t just about GDP—it was about where people lived. In the 1950s, New York’s Manhattan still dominated global wealth rankings, but the numbers were crude. A household’s net worth was often tied to a single asset: a brownstone or a factory. The first city-level wealth surveys in the 1960s revealed something unsettling: wealth wasn’t distributed evenly across a city’s geography. The financial district of Tokyo, for instance, showed net worth figures that dwarfed those in its outer wards, where most residents relied on wages alone. The turning point came in the 1980s, when deregulation and globalization forced cities to compete. London’s "Big Bang" financial overhaul in 1986 didn’t just reshape its skyline—it recalibrated the "average household net worth by city" metric. Overnight, the wealth of a small elite in Mayfair and the City of London skyrocketed, while working-class neighborhoods in East London stagnated. The same happened in Hong Kong, where property tycoons accumulated fortunes while public housing residents saw little growth in their net worth. For the first time, cities weren’t just economic hubs; they were wealth polarizers.The Early Signs
Before the 1990s, most wealth data was national or regional. But as cities became laboratories for economic experiments, local governments started tracking "average household net worth by city" to attract investment. The first comprehensive city-level reports came from Switzerland and Scandinavia, where transparency was already high. Zurich’s wealth numbers, for example, showed that by the late 1980s, the top 10% of households held nearly 50% of the city’s total net worth—a ratio that would only steepen in the decades to come. The early 1990s brought another shift: the rise of the "global city" concept. Cities like Singapore and Dubai began publishing wealth indices to lure expatriates and capital. Their "average household net worth by city" figures were eye-catching—Singapore’s, in particular, masked deep inequality, with financial sector employees earning multiples of what manufacturing workers took home. Meanwhile, in Latin America, cities like Buenos Aires and Mexico City saw wealth concentrate in a few affluent zones, while the rest of the population struggled with inflation and currency devaluations.The Turning Point
The 2008 financial crisis didn’t just crash markets—it exposed the fragility of city-level wealth metrics. Overnight, the "average household net worth by city" in places like Miami and Dublin plummeted as property bubbles burst. But the real revelation was how resilient some cities remained. Hong Kong’s wealth figures barely dipped because its elite had diversified assets. The crisis proved that "average household net worth by city" wasn’t just about income—it was about asset protection and generational wealth. By 2010, the conversation shifted from survival to opportunity. Cities like Berlin and Lisbon, which had been overlooked, suddenly saw their "average household net worth by city" climb as global capital fled traditional hubs. The data became a tool for urban policy: if a city’s wealth was concentrated in a few districts, planners could argue for infrastructure investments to spread prosperity. But the flip side was clear—wealth begets wealth, and cities that had historically excluded certain groups now faced the consequences of that exclusion in their net worth statistics."A city’s wealth map isn’t just about money—it’s a reflection of who gets to play in the game. If your net worth is tied to a single asset, like a home in a gentrifying neighborhood, you’re vulnerable. If it’s spread across stocks, real estate in multiple cities, and family trusts, you’re insulated. The crisis didn’t change that—it just made it obvious." — Economist at the OECD, 2012

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1990–2000 | Rise of tech hubs (e.g., Silicon Valley, Tel Aviv) boosts "average household net worth by city" via stock options and IPOs. Traditional financial centers (London, NYC) see wealth concentration in elite districts. |
| 2001–2007 | Globalization accelerates; cities like Shanghai and Mumbai see rapid wealth growth in export-driven sectors. The "average household net worth by city" in Dubai and Miami inflates due to speculative real estate. |
| 2008–2015 | Crisis reveals disparities: "average household net worth by city" drops in Southern Europe (Athens, Lisbon) but stabilizes in Asian financial hubs (Tokyo, Singapore) due to diversified portfolios. |
| 2016–Present | Digital nomadism and remote work blur city boundaries; "average household net worth by city" becomes harder to pin down. Wealth inequality widens in cities like New York and Sydney, where housing costs outpace wage growth. |
Lessons From the Journey
- Wealth isn’t static—it’s territorial. A city’s "average household net worth by city" is shaped by its history, from colonial-era land grabs to modern gentrification. Places like Cape Town or Barcelona show how wealth can be both a legacy and a liability.
- Asset classes matter more than income. In cities like Zurich or Geneva, "average household net worth by city" is propped up by private banking and cross-border investments—far more than salaries.
- Policy lags behind reality. Many cities only track "average household net worth by city" after a crisis, not as a preventive tool. The result? Wealth gaps become entrenched before anyone acts.
- Globalization has a zip code. The "average household net worth by city" in a financial district like Canary Wharf (London) bears little resemblance to that of its surrounding boroughs. The same goes for Manhattan vs. the Bronx.
Where Things Stand Today
Today, the "average household net worth by city worldwide" is a patchwork of extremes. In Monaco or Geneva, where banking secrecy and high-net-worth individuals (HNWIs) dominate, the figures are stratospheric—though the data is often opaque. Meanwhile, in Jakarta or Lagos, the "average household net worth by city" is skewed by informal economies, where assets like livestock or street vendor equipment aren’t always captured in surveys. The rise of cryptocurrency and digital assets has further complicated the picture: in cities like Buenos Aires or Istanbul, some households now hold wealth in volatile assets that don’t show up in traditional net worth calculations. What’s clear is that the "average household net worth by city" is no longer just a financial metric—it’s a political one. Cities like Amsterdam and Copenhagen have used wealth data to push for progressive taxation, while others, like Dubai or Shanghai, leverage it to attract global capital. The pandemic accelerated these trends: remote work made "average household net worth by city" less tied to physical location, but it also highlighted how wealth disparities play out in local housing markets. In short, the numbers aren’t just about money anymore—they’re about who controls the future of a city.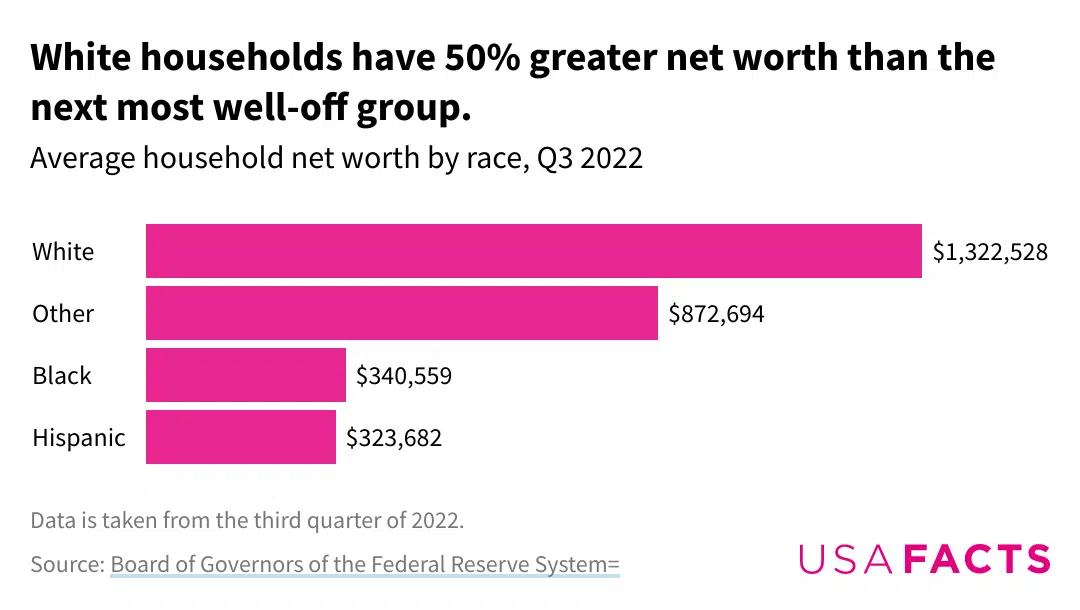
Conclusion
The story of "average household net worth by city worldwide" is one of uneven progress. It’s a tale of financial districts that outpace their own suburbs, of cities that become wealth magnets while others stagnate, and of households that either thrive or barely keep up. The data isn’t just cold numbers—it’s a mirror held up to urban inequality. And the reflection isn’t always flattering. Yet, for all its flaws, tracking "average household net worth by city" remains essential. It forces policymakers to confront hard questions: Should a city’s wealth be concentrated in a few hands, or should it be spread more evenly? Can technology bridge the gap, or will it widen it further? The answers aren’t just economic—they’re moral. And the cities that get them right will shape the next chapter of global wealth—not just for the elite, but for everyone.Comprehensive FAQs
Q: Which city has the highest average household net worth by city worldwide?
As of recent estimates, Zurich, Switzerland, and Geneva consistently rank at the top due to private banking, high salaries, and strong asset diversification. However, figures are often suppressed or estimated, as many wealthy households hold assets offshore. Monaco and Singapore also appear frequently in top rankings, though their data is less transparent.
Q: How does average household net worth by city differ from national averages?
National averages smooth out local disparities. For example, the U.S. national average masks the fact that San Francisco’s net worth per household is five times higher than in Detroit. Similarly, India’s national figure obscures Mumbai’s ultra-wealthy pockets alongside slums. City-level data reveals geographic wealth inequality that national statistics hide.
Q: Can average household net worth by city be manipulated by local governments?
Yes. Cities with strong financial sectors (e.g., London, Hong Kong) often see inflated figures due to asset concentration among a small elite. Meanwhile, cities with high housing costs (e.g., Vancouver, Sydney) may show lower net worth because homeownership is out of reach for many. Some governments also exclude certain assets (like agricultural land or informal businesses) to paint a rosier picture.
Q: What’s the biggest misconception about average household net worth by city?
The biggest myth is that it reflects living standards equally. A high net worth in a city like Dubai doesn’t mean most residents are prosperous—it often means a few ultra-wealthy families dominate the numbers. Conversely, a lower average in a city like Berlin might hide a diverse middle class with strong social safety nets. The metric is useful, but it’s not a measure of equity.
Q: How does average household net worth by city affect real estate markets?
Directly. In cities where net worth is concentrated (e.g., Manhattan, Central London), luxury real estate prices surge because wealthy buyers drive demand. In contrast, cities with stagnant net worth (e.g., Detroit, parts of Spain) see abandoned properties and depressed values. The correlation is so strong that some investors now use "average household net worth by city" as a predictor of future property trends.
Q: Are there cities where average household net worth by city is rising faster than others?
Yes. Tech hubs like Austin, Tel Aviv, and Bangalore have seen rapid growth due to high-paying jobs and stock options. Meanwhile, secondary cities in Asia (e.g., Ho Chi Minh City, Jakarta) are catching up as manufacturing and services expand. However, these gains are often uneven—wealth may grow in certain districts while others lag. The pandemic also accelerated shifts, with remote-friendly cities (e.g., Lisbon, Medellín) seeing unexpected surges.
