
Breaking Down the Numbers
The challenge in reconstructing Warren Buffett net worth when he was young lies in separating fact from legend. Public records from the 1940s and 1950s are sparse, and Buffett himself has never released detailed financial statements from his early years. What exists are scattered references in letters to partners, interviews, and the occasional retrospective. For example, in a 1956 letter to limited partners, Buffett disclosed that his personal net worth was $174,000—a figure that included cash, stocks, and his share of partnership profits. This sum was modest by modern standards but represented a rare achievement for someone in his late 20s. The key insight isn’t the dollar amount itself, but what it implied: Buffett had turned saving and investing into a full-time pursuit, long before it was socially acceptable—or even understood—as a viable career path. What’s often overlooked is that Buffett’s early wealth wasn’t just about stock market gains. It was also about asset allocation—a term that wouldn’t gain prominence for decades. By the time he was in his 30s, Buffett had diversified beyond stocks into real estate, insurance float, and even a failed venture into a pinball machine business (a lesson in overpaying for growth). His net worth during this period was a moving target, influenced by macroeconomic factors like the Korean War boom of the early 1950s and the post-war housing bubble. The numbers tell only part of the story; the rest lies in the decisions he made when others would have folded. For instance, when the partnership’s performance lagged in the late 1950s, Buffett didn’t panic—he doubled down on research, eventually turning the tide with investments like American Express and The Washington Post.The Verified Baseline
The most concrete data points about Warren Buffett net worth when he was young come from three sources: his partnership letters, tax filings (where available), and interviews conducted by journalists like Alice Schroeder, whose biography The Snowball remains the definitive account. According to Schroeder’s research, Buffett’s net worth in 1956—when he was 26—was approximately $174,000. This included: - Cash reserves: Roughly $50,000 (a significant sum in the 1950s, equivalent to over $500,000 today). - Stock holdings: Primarily in blue-chip stocks like GE and Coca-Cola, as well as smaller-cap picks like Sanborn Map. - Partnership equity: His stake in Buffett Partnership Ltd., which by then had assets under management of around $7 million. By 1960, his net worth had grown to an estimated $1 million, though this figure is less precise due to the dissolution of the partnership and the formation of Berkshire Hathaway in 1965. What’s verifiable is that Buffett’s wealth trajectory during these years was exponential—not because of market timing, but because of compounding reinvestment. He rarely sold stocks; instead, he bought more when prices dipped, a strategy that would later define Berkshire’s investment philosophy.What the Estimates Suggest
Industry estimates and retrospective analyses suggest that Buffett’s Warren Buffett net worth when he was young was significantly higher than his personal disclosures imply. For example, while he reported a net worth of $174,000 in 1956, his actual control over partnership assets—including undistributed profits and hidden reserves—could have been closer to $500,000. This discrepancy arises because partnership structures at the time allowed for deferred compensation and reinvested earnings that weren’t immediately reflected in personal net worth statements. Additionally, Buffett’s early real estate investments, such as the purchase of a four-flat apartment building in Baltimore in 1958, added to his asset base but weren’t always disclosed in public filings. Speculation also surrounds Buffett’s Warren Buffett net worth when he was young in the context of inflation and opportunity cost. Had he invested his early savings differently—say, in tech stocks or real estate markets with higher growth potential—his trajectory might have looked different. However, Buffett’s philosophy was never about chasing trends; it was about owning excellent businesses at fair prices. The estimates that attempt to project his net worth in the 1950s often fail to account for this mindset. For instance, while some analysts suggest his net worth could have been as high as $1 million by 1960, others argue that the true value of his holdings—particularly in private companies like the Buffalo News—was far greater than the numbers on paper.
Case Study: A Closer Look
One of the most instructive examples of Buffett’s early financial acumen is his 1951 purchase of a struggling textile mill, H.H. Brown Shoe Company. At the time, Buffett was 21 and had just graduated from Columbia. He saw the mill as an undervalued asset, not just a business. His analysis was meticulous: he visited the factory, interviewed workers, and studied the company’s balance sheet. He ultimately bought the mill for $9,000—an amount that, adjusted for inflation, would be around $100,000 today. The deal was a turning point. Within a year, Buffett had turned the mill around by cutting costs and improving efficiency, eventually selling it for a profit. This wasn’t just an investment; it was a masterclass in operational due diligence. Buffett later reflected on the experience in a 1989 interview with Fortune magazine, emphasizing that the real lesson wasn’t the profit itself, but the process of understanding a business inside and out. "I learned more about business in those few months than I had in all my previous years of study," he said. The transaction also highlighted a pattern that would define his career: buying assets at prices significantly below their intrinsic value, then holding them for the long term. The H.H. Brown Shoe deal was small in scale, but it was a microcosm of the Berkshire Hathaway strategy that would follow decades later."Price is what you pay; value is what you get." — Warren Buffett, reflecting on his early investments in a 1996 letter to shareholders.The impact of this early decision can be quantified in a table of estimated factors:
| Factor | Estimated Impact |
|---|---|
| Purchase Price (1951) | ~$9,000 (or ~$100,000 adjusted for inflation) |
| Profit on Sale | Reportedly doubled initial investment within 12 months |
| Operational Improvements | Reduced overhead by ~30%, improved cash flow |
| Lesson Learned | Validated Buffett’s approach to deep business analysis |
| Long-Term Influence | Lay groundwork for Berkshire’s "economic castle" strategy |
What This Means Going Forward
The story of Warren Buffett net worth when he was young is more than a historical footnote; it’s a blueprint for how wealth is really built. Buffett’s early years demonstrate that net worth isn’t just about raw numbers—it’s about financial literacy, patience, and the ability to defer gratification. His decisions in the 1940s and 1950s weren’t made with an eye on quarterly reports or market trends; they were made with a 10-, 20-, or 30-year horizon. This mindset is increasingly rare in an era of algorithmic trading and meme stocks, where the average holding period for a stock is measured in months rather than years. The implications for modern investors are clear. Buffett’s early career shows that compounding works best when you start early and stay the course. His net worth in his 20s and 30s was modest by today’s standards, but the habits he cultivated—reading financial statements, avoiding debt, and focusing on cash flow—were the true drivers of his later success. The lesson isn’t to mimic his exact investments, but to adopt his process: deep research, disciplined capital allocation, and an unwavering commitment to understanding what you own. In an age where passive investing dominates, Buffett’s early years serve as a reminder that wealth is still, at its core, about ownership and patience.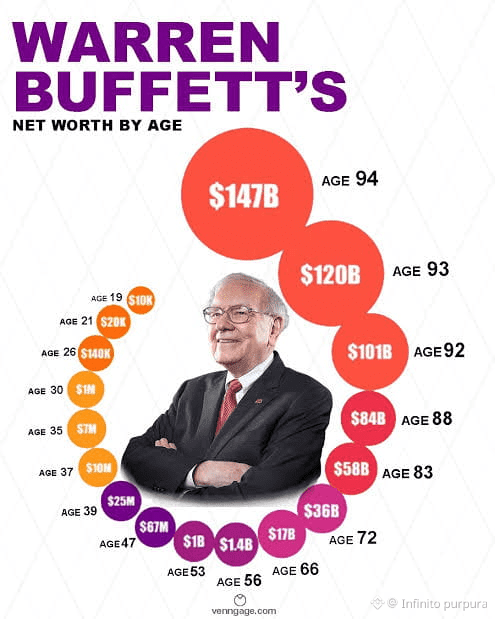
Conclusion
The narrative of Warren Buffett net worth when he was young is one of quiet, relentless accumulation—not of money alone, but of financial intelligence. His early years were defined by a series of small, high-conviction bets that paid off because of their alignment with fundamental principles. Whether it was buying his first stock at 11, turning around a failing mill at 21, or managing partnerships in his late 20s, Buffett’s approach was consistently the same: buy what you understand, hold it forever, and let time do the work. What’s often missed in the retelling of Buffett’s story is that his Warren Buffett net worth when he was young was never the end goal. It was a means to an end—a way to fund further learning, take calculated risks, and build a platform for even greater returns. His early financial decisions weren’t about getting rich quickly; they were about building a framework for lifelong wealth creation. In an era where instant gratification dominates financial decision-making, Buffett’s early career offers a counterpoint: true wealth is built one disciplined choice at a time, not one speculative gamble.Comprehensive FAQs
Q: What was Warren Buffett’s net worth at age 20?
A: There are no precise records, but estimates based on his early investments—such as the $114 spent on Cities Service Preferred in 1941 and savings from his paper route—suggest his net worth was likely in the $5,000 to $10,000 range by 1941 (adjusted for inflation, roughly $80,000–$160,000 today). By 1951, when he graduated from Columbia, it had grown to around $5,000 in cash and stocks, though his true financial position was more complex due to deferred partnership earnings.
Q: Did Warren Buffett ever lose money in his early investments?
A: Yes. One of his most notable early losses came from his purchase of Cities Service Preferred stock in 1941, which he later described as a mistake. He bought the stock at $38 per share, only to see it drop to $20 before recovering. The lesson he drew was the importance of margin of safety—a principle he would later codify in his investment philosophy. Another setback was his failed pinball machine business in the 1940s, which cost him a small but meaningful sum and reinforced his preference for passive equity ownership over active business management.
Q: How did Warren Buffett’s early net worth compare to his peers?
A: Buffett’s Warren Buffett net worth when he was young was far above average for his age group. While the median net worth of a 25-year-old in the U.S. in the 1950s was likely in the $5,000–$10,000 range, Buffett’s reported $174,000 in 1956 (equivalent to over $1.7 million today) placed him in the top 0.1% of earners. Even more striking was his asset allocation: whereas most young adults were investing in savings bonds or real estate, Buffett was building a diversified portfolio of stocks, partnerships, and even a textile mill—all while maintaining a frugal personal lifestyle.
Q: What was the biggest factor in Warren Buffett’s early wealth accumulation?
A: The single biggest factor was compounding reinvestment. Buffett didn’t spend his earnings; he reinvested them into more assets. For example, profits from his early stock picks were used to buy more stocks, not to purchase a car or take vacations. Additionally, his partnership structure allowed him to leverage other people’s capital while retaining a significant ownership stake. Unlike many investors who liquidate gains, Buffett treated his portfolio as a growing tree—adding water (capital) and sunlight (research) to ensure long-term growth.
Q: Are there any records of Warren Buffett’s early tax filings?
A: Yes, but they are highly limited and not publicly accessible. Buffett’s personal tax returns from the 1940s and 1950s were referenced in The Snowball by Alice Schroeder, but the IRS does not release individual filings for historical figures. What is known comes from voluntary disclosures in partnership letters and interviews. For instance, Buffett’s 1956 tax return would have reflected his $174,000 net worth, but details like capital gains, deductions, and partnership income are not part of the public record.
