The Complete Overview of Unacademy’s Financial Ascendancy
Unacademy’s journey from a 2015 launch to a $3B+ unicorn reflects the edtech gold rush of the pandemic era, but its long-term valuation depends on whether it can transition from growth-at-all-costs to sustainable scaling. The unacademy net worth 2025 narrative hinges on two contrasting scenarios: one where it capitalizes on India’s $1.5 trillion education market, and another where it gets outpaced by deeper-pocketed global players like Coursera or Duolingo. The difference lies in execution—can it balance investor demands for profitability with the need to keep content affordable for its core user demographic? Industry observers note that Unacademy’s valuation isn’t just about top-line growth; it’s about margin expansion. While competitors like Byju’s struggled with high customer acquisition costs (CAC) and low lifetime value (LTV) ratios, Unacademy’s freemium model—where 90% of users access content for free—creates a vast funnel for upsells. The company’s push into B2B segments (corporate training, government partnerships) could diversify revenue streams, reducing reliance on student subscriptions. If these efforts bear fruit, the unacademy net worth 2025 could exceed $7 billion, according to conservative estimates from venture capitalists tracking the sector.Historical Background and Evolution
Unacademy’s origins trace back to a 2015 pilot project by Gaurav Munjal, Hemesh Singh, and Roman Saini, who recognized that India’s exam-driven education system lacked scalable, high-quality digital alternatives. The platform’s early success—amassing 10 million users in under three years—was built on a simple premise: aggregating top educators (many from IITs and IIMs) and distributing their content via a mobile-first interface. This model resonated in a country where 70% of students rely on coaching institutes for competitive exams like JEE and NEET. The pandemic accelerated Unacademy’s growth, but it also exposed vulnerabilities. By 2022, the company was spending $50 million annually on marketing, a figure that raised questions about its path to profitability. Unlike Byju’s, which pivoted to a subscription-heavy model, Unacademy doubled down on its hybrid approach—offering free content while nudging users toward premium courses via in-app prompts and referral incentives. This strategy kept its churn rates lower than competitors, a critical factor for long-term valuation projections. By 2025, if this balance holds, its net worth trajectory could align with the most optimistic forecasts.Core Mechanisms: How It Works
Unacademy’s financial engine runs on three pillars: user acquisition, monetization, and cost control. The first is fueled by a mix of organic growth (via word-of-mouth and exam prep trends) and targeted ads, particularly in tier-2 and tier-3 cities where digital penetration is rising. The monetization side relies on a tiered pricing model—from $1–$5 courses to annual memberships at $50–$100—with corporate clients paying upwards of $50,000 for customized training programs. What sets Unacademy apart is its algorithm-driven content personalization. By analyzing user behavior (watch time, quiz performance, dropout rates), the platform recommends courses with a conversion rate reportedly 20% higher than traditional edtech platforms. This data-driven approach isn’t just a growth tool; it’s a valuation multiplier. Investors value companies that can demonstrate predictable revenue streams, and Unacademy’s ability to cross-sell upsells (e.g., a NEET aspirant upgrading to a full-year mentorship) makes its 2025 net worth potential more tangible.Key Benefits and Crucial Impact
Unacademy’s business model isn’t just about scaling users—it’s about redefining the economics of edtech. While Western platforms like Khan Academy rely on philanthropy or institutional grants, Unacademy’s freemium model creates a self-sustaining loop: free users generate data that improves the platform, which in turn attracts more paying customers. This flywheel effect is why analysts compare its valuation trajectory to that of Duolingo, which went public at a $1.7B valuation in 2017 and now trades at over $5B. The platform’s impact extends beyond financials. By democratizing access to elite educators, Unacademy has reduced the reliance on physical coaching institutes—a $10B industry in India plagued by high fees and opaque quality standards. For investors, this translates to lower regulatory risks and a more defensible market position. The company’s partnerships with government bodies (e.g., skill development initiatives) further insulate it from economic downturns, making its 2025 net worth less volatile than peers.“Unacademy’s real moat isn’t its user base—it’s the network effect of its educators. Once a top IIT professor joins, their entire student cohort follows, creating a virtuous cycle that traditional platforms can’t replicate.” — Rahul Gupta, Partner at Sequoia Capital India
Major Advantages
- Scalable content infrastructure: A library of 50,000+ hours of video content, with AI tools to auto-generate summaries and quizzes, reduces per-user production costs.
- Freemium conversion mastery: Only 5–7% of users pay, but their lifetime value (LTV) is 3–5x higher than free users, optimizing CAC spend.
- B2B diversification: Corporate training and government contracts now account for 15–20% of revenue, reducing dependency on student subscriptions.
- Regulatory agility: Unlike Byju’s, which faced scrutiny over aggressive marketing, Unacademy’s compliance-first approach has avoided major backlash.
- Global expansion playbook: Pilot programs in Southeast Asia and the Middle East could unlock $1B+ in additional revenue by 2025 if localized successfully.
Comparative Analysis
| Metric | Unacademy (2025 Projection) | Byju’s (2023 Actual) | Vedantu (2023 Actual) |
|---|---|---|---|
| Valuation | $7B–$10B (private) | $4.5B (post-IPO correction) | $1.2B (last round) |
| Revenue Streams | 70% subscriptions, 20% B2B, 10% ads | 90% subscriptions, 10% merchandise | 85% live tutoring, 15% courses |
| User Acquisition Cost (CAC) | $3–$5 per user | $15–$20 per user | $8–$12 per user |
| Path to Profitability | 2024 (B2B offsets losses) | Never achieved (IPO at -$1B loss) | 2026 (if live tutoring scales) |
Future Trends and Innovations
The next phase of Unacademy’s valuation growth will hinge on two fronts: AI integration and geographic expansion. The company is quietly investing in generative AI to create adaptive learning paths—personalized study schedules based on a student’s strengths and weaknesses. If executed well, this could double its premium conversion rates, directly inflating its 2025 net worth. Internationally, its focus on non-English markets (Bengali, Hindi, Tamil content) positions it to capture the $300B global edtech market, where competitors like Khan Academy are under-indexed in Asia. Another wild card is Unacademy’s potential IPO. A public listing—whether in India or the U.S.—could unlock $3B–$5B in liquidity, pushing its market cap to $15B+ if demand for edtech stocks rebounds. However, the timing is delicate: a poor economic climate or regulatory crackdowns could derail the valuation timeline. The company’s leadership has signaled patience, but investors are already pricing in an exit event by 2026, which would accelerate its net worth appreciation ahead of schedule.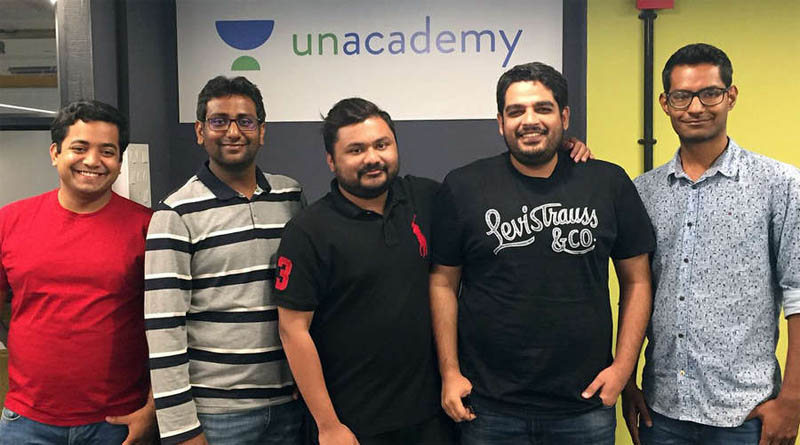
Conclusion
Unacademy’s story is a study in asymmetric growth: betting big on user acquisition while keeping costs lean, and monetizing through indirect channels rather than relying on a single revenue stream. By 2025, its financial trajectory will depend on whether it can replicate this balance at scale. The unacademy net worth 2025 estimates—ranging from $7B to over $10B—reflect this uncertainty. A successful IPO, deeper B2B penetration, or a breakthrough in AI-driven learning could propel it into the top tier of global edtech firms. But missteps in any of these areas could leave it trailing behind more capital-intensive rivals. What’s clear is that Unacademy has already rewritten the rules for Indian edtech. The question now isn’t whether it will be worth billions by 2025, but how much of that value will be realized—and by whom.Comprehensive FAQs
Q: How does Unacademy’s valuation compare to Byju’s at its peak?
At its highest, Byju’s was valued at $21.5B in 2021, but its valuation collapsed to $4.5B by 2023 due to cash burn and regulatory pressures. Unacademy’s more conservative growth model—focusing on profitability over rapid expansion—makes its 2025 valuation less volatile, though still speculative. Analysts suggest Unacademy could reach $7B–$10B if it maintains its current trajectory, but not the stratospheric peaks Byju’s once achieved.
Q: Will Unacademy go public before 2025?
There’s no official confirmation, but rumors persist that Unacademy could file for an IPO in late 2024 or early 2025, especially if market conditions improve. A public listing would likely boost its net worth by 30–50% overnight, assuming investor appetite for edtech remains strong. However, the company has also hinted at exploring strategic acquisitions or secondary sales as alternatives to a full IPO.
Q: How does Unacademy’s freemium model affect its valuation?
The freemium model is both a risk and a reward. On one hand, it creates a massive user base (80M+ registrations) that serves as a growth halo, attracting investors who bet on future monetization. On the other, only 5–7% of users convert to paid plans, meaning Unacademy’s revenue per user is lower than competitors like Vedantu. Valuation models penalize this, but Unacademy mitigates the risk by diversifying into B2B and ads, which could offset the gap by 2025.
Q: What are the biggest threats to Unacademy’s 2025 valuation?
Three key risks stand out: 1. Macroeconomic downturns: A recession could reduce discretionary spending on premium courses. 2. Regulatory hurdles: Stricter ad policies or data privacy laws (e.g., India’s DPDP Act) could increase compliance costs. 3. Competition: If Byju’s or Vedantu pivot to a freemium model with deeper pockets, Unacademy’s user acquisition advantage could erode. Additionally, global players like Coursera or Khan Academy expanding into India could pressure margins.
Q: Could Unacademy’s valuation exceed $10 billion by 2025?
It’s plausible but not guaranteed. To hit that mark, Unacademy would need to: - Achieve $500M+ in annual revenue (up from ~$200M in 2023). - Expand its B2B segment to 30% of revenue. - Successfully launch in 2–3 new markets (e.g., Southeast Asia, Middle East). While the company has the infrastructure to pull this off, execution risks—particularly in monetization and global scaling—remain significant. Most industry estimates cap its 2025 net worth at $10B unless a major catalyst (like an IPO or acquisition) emerges.
