
The Short Answers
- U.s. net worth percentiles are calculated by ranking households by total assets minus debts, then dividing them into 100 equal groups. The median (50th percentile) is often more revealing than the mean due to wealth concentration.
- The top 10% hold about 70% of all liquid assets, while the bottom 50% collectively own less than 3%. This gap has widened since the 2008 financial crisis.
- Homeownership is the single biggest driver of net worth—owning a home accounts for roughly 60% of the median household’s wealth.
- Student debt depresses net worth for younger cohorts, pushing many into the lower percentiles even with middle-class incomes.
- Racial wealth gaps persist: The median White household’s net worth is about 10 times that of the median Black household, largely due to historical discrimination in housing and lending.
- Percentiles vary dramatically by region—urban areas with high housing costs (e.g., San Francisco, New York) skew wealth distributions upward compared to rural or Southern states.

Deep Dive: The Full Picture
The Federal Reserve’s Survey of Consumer Finances (SCF) is the most authoritative source for u.s. net worth percentiles, but its methodology matters. The SCF samples about 6,000 households every three years, adjusting for income, age, and region to estimate national trends. Crucially, it defines net worth as the sum of all assets—cash, investments, home equity, retirement accounts—minus liabilities like mortgages or credit card debt. This differs from income, which is a flow measurement, not a stock. The result? A snapshot that reveals how wealth accumulates over time, not just how much money flows in and out each year. For example, a teacher with a $70,000 salary might rank in the 30th percentile for income but the 10th for net worth if they’ve paid off their mortgage and saved aggressively. What the percentiles don’t show is volatility. A single event—a job loss, medical emergency, or market downturn—can push a household from the 75th to the 25th percentile overnight. The SCF captures a moment in time, not a trajectory. This is why economists often look at longitudinal net worth data—tracking the same households over decades—to understand mobility. What they find is that wealth begets wealth. A child born into the top 20% of earners has a 42% chance of staying there as an adult; for those born in the bottom 20%, the odds drop to 8%. The percentiles aren’t just numbers; they’re a proxy for opportunity.The Context You Need
The modern era of u.s. net worth tracking began in the 1980s, when the Fed first published detailed breakdowns. Before that, wealth data was sparse, and what existed was often skewed by survey biases. The 1989 SCF, for instance, showed that the top 1% held 18.4% of wealth—a figure that would balloon to 32% by 2019. This wasn’t just growth; it was a shift in the distribution. The Great Recession of 2008 erased trillions in household wealth, but the recovery was uneven. By 2016, the top 1% had regained all their losses, while the bottom 90% were still below pre-crisis levels. The percentiles became a tool to measure not just inequality, but resilience. Regional disparities further complicate the picture. A household in Manhattan might need $5 million to rank in the 90th percentile, while in Mississippi, $300,000 could place them there. The Fed adjusts for cost of living, but local economies create their own wealth gradients. In Texas, oil booms can temporarily inflate percentiles, while Rust Belt cities see stagnation. Even within states, urban-rural divides matter: A farmer in Iowa with $2 million in land equity could be in the 95th percentile nationally, but a young professional in Chicago with the same net worth might feel financially insecure due to higher living costs.The Mechanics
The calculation of u.s. net worth percentiles follows a straightforward but nuanced process. First, the Fed’s survey collects data on assets (primary residence, investments, vehicles, business equity) and liabilities (mortgages, student loans, credit card debt). It then computes net worth for each household and ranks them from lowest to highest. The percentiles are derived by dividing this ranked list into 100 equal parts. For example, the 75th percentile (top quartile) represents the threshold below which 75% of households fall. However, because wealth is highly skewed—a few ultra-high-net-worth individuals can distort the mean—the median (50th percentile) is often a more reliable indicator of “typical” wealth. The challenge lies in interpreting these thresholds. A net worth of $1.2 million might place a household in the 90th percentile nationally, but in Silicon Valley, that same figure could rank them in the 60th percentile due to the concentration of billionaires. The SCF also excludes certain assets, like the value of human capital (skills, education) or public pensions, which can understate the wealth of younger or public-sector workers. Moreover, the survey’s three-year cycle means it lags behind real-time shifts, such as the 2020 stock market rally or the surge in home prices during the pandemic. Despite these limitations, the percentiles remain the best available tool for comparing wealth across demographics and over time.Details That Change the Picture
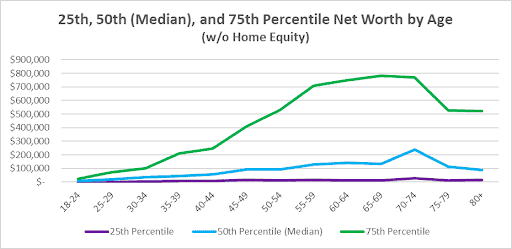
Age is the single most powerful predictor of where a household falls in u.s. net worth distributions. The median net worth of a 35-year-old is about $91,300, while a 65-year-old’s is $231,400—nearly 2.5 times higher. This reflects the power of compounding, but also the fact that younger households are more likely to carry student debt or rent rather than own homes. The gap narrows slightly for older cohorts, but even at 75, the median net worth drops to $176,200, as healthcare costs and longevity risks erode savings. This age-based stratification explains why discussions about wealth often focus on retirement security: the percentiles aren’t just about current standing, but future stability. Then there’s the question of what assets count. Home equity dominates net worth for most Americans—accounting for roughly 60% of the median household’s wealth. But this masks regional differences. In states with high property taxes or flood risks, homeownership can be a liability rather than an asset. Meanwhile, stock market exposure skews wealth upward for older generations who benefited from bull markets, while younger workers face lower 401(k) balances due to the 2008 crash and subsequent stagnant wages. The percentiles also ignore intangible assets like social networks or community resources, which can provide economic buffers not captured in financial statements.“Wealth isn’t just about money—it’s about access. If you’re born into a family that owns a home in a good school district, you’re already ahead of someone who isn’t. The percentiles show the outcome, but not always the cause.” —Darrick Hamilton, economist and professor at The New School
| Percentile | Approximate Net Worth Threshold (2022, national median) |
|---|---|
| 25th (bottom quartile) | $62,900 |
| 50th (median) | $176,500 |
| 75th (top quartile) | $638,400 |
| 90th | $1.2 million |
Conclusion
The data on u.s. net worth percentiles isn’t just dry statistics—it’s a mirror held up to America’s economic reality. The numbers confirm what many already suspect: wealth is concentrated at the top, and mobility is limited. But percentiles alone can’t explain why. They don’t account for the racial wealth gap, the generational divide, or the regional disparities that shape financial outcomes. To understand inequality, you need to look beyond the raw figures: at the policies that subsidize homeownership, the tax breaks that favor capital gains, and the cultural narratives that equate personal failure with poverty. The percentiles are a starting point, not an endpoint. What’s clear is that wealth accumulation is a long game, and the rules are stacked. A teacher saving for retirement will never build the same net worth as a hedge fund manager, not because of effort, but because the system rewards certain forms of capital over others. The challenge isn’t just to interpret the percentiles—it’s to ask what they imply about the future. Will the next generation see even greater inequality? Or will shifts in policy, education, and cultural attitudes finally narrow the gaps? The answer lies in the data, but the solutions require more than numbers.Comprehensive FAQs
Q: How often are u.s. net worth percentiles updated?
The Federal Reserve’s Survey of Consumer Finances (SCF) is conducted every three years, with the most recent full dataset covering 2022. However, the Fed releases preliminary estimates and regional breakdowns more frequently. For real-time tracking, some organizations (like the Brookings Institution) use modeling to project trends between SCF cycles.
Q: Does student debt significantly impact net worth percentiles?
Absolutely. Student loan debt depresses net worth for younger cohorts, pushing many into the lower percentiles even with middle-class incomes. For example, the median net worth of a 35-year-old with student debt is about 40% lower than someone without it. This effect is most pronounced for Black and Hispanic borrowers, who face higher default rates and longer repayment periods.
Q: Are u.s. net worth percentiles adjusted for inflation?
Yes, but with caveats. The Federal Reserve adjusts for inflation when comparing percentiles over time, but the methodology varies by asset class. Home values, for instance, are adjusted using regional price indices, while stock portfolios use broader market benchmarks. This can lead to slight discrepancies in long-term trend analysis.
Q: How do racial disparities affect net worth percentiles?
The racial wealth gap is stark: The median White household’s net worth is about 10 times that of the median Black household, and nearly 8 times that of the median Hispanic household. This gap is driven by historical factors like redlining, discriminatory lending practices, and the wealth-building advantages of homeownership—White families are far more likely to inherit property or receive intergenerational wealth transfers.
Q: Can you rank in a high net worth percentile but still feel poor?
Yes. Context matters. A household in a high-cost city (e.g., New York or San Francisco) might rank in the 90th percentile nationally with a $1.5 million net worth, yet struggle with childcare costs, healthcare premiums, or property taxes that would make them middle-class in a rural area. Percentiles are national averages—they don’t reflect local economic realities.
Q: What’s the difference between net worth percentiles and income percentiles?
Net worth measures accumulated wealth (assets minus debts), while income tracks annual earnings. A high earner might rank in the 95th percentile for income but the 70th for net worth if they’ve spent heavily or carry debt. Conversely, a frugal saver could rank in the 50th percentile for income but the 80th for net worth due to home equity or investments. The two metrics often diverge, especially as people age.
Q: How do u.s. net worth percentiles compare to other developed nations?
America’s wealth inequality, as measured by percentiles, is far more extreme than in most peer countries. The top 10% in the U.S. hold about 70% of liquid assets, compared to roughly 50% in Germany or Canada. This reflects deeper structural issues, including weaker social safety nets, higher healthcare costs, and a tax system that favors capital gains over labor income.
