
The Short Answers
- U.S. net worth 2025 is estimated at ~$160 trillion, but the top 1% will own more than the bottom 90% combined.
- Homeownership rates for under-40s will drop below 40%, reversing decades of progress.
- Corporate stock buybacks will outpace wage growth, keeping wealth concentrated in executive portfolios.
- Student debt relief policies (if any) could add $100B+ to collective net worth—but only for borrowers.
- AI-driven automation will boost productivity but displace mid-skill jobs, hitting net worth growth in Rust Belt states.
- Tax policy in 2025 will hinge on whether capital gains rates rise or fall—directly impacting high-net-worth portfolios.
Deep Dive: The Full Picture
The U.S. net worth 2025 landscape is defined by two contradictory trends: record-high asset valuations and record-low mobility. On paper, the S&P 500 is projected to hit 6,000 by mid-decade, and commercial real estate in gateway cities remains overvalued by 20%+ in some markets. Yet for the average worker, the net worth equation has broken down. The median household net worth—already stagnant since 2019—will dip in real terms for the first time since the Great Recession. The disconnect stems from how wealth is created: 75% of net worth growth in 2025 will come from asset appreciation, not labor income. The implications are political as much as economic. A 2024 Brookings study found that states with the highest wealth inequality (Florida, Texas, California) saw 30% more lobbying spending on asset-protection laws than states with balanced distributions. By 2025, expect red-state legislatures to push for inheritance tax exemptions while blue states debate wealth taxes—both measures designed to either preserve or redistribute the U.S. net worth 2025 pie. The tension isn’t new, but the stakes are higher because this time, the younger generations are watching. Gen Z’s net worth is 40% lower than Millennials’ at the same age, and they’re the first cohort to enter adulthood with no expectation of out-earning their parents.The Context You Need
To understand the U.S. net worth 2025 projection, you need to look at three inflection points: the 2020-2022 pandemic boom, the 2023-2024 rate-hike hangover, and the 2025 policy wild card. The first two are clear: the Fed’s emergency liquidity propped up stock markets and home prices, but the subsequent rate hikes squeezed $2.5 trillion in household wealth from housing alone. By 2025, those losses will be partially offset by $1.8 trillion in expected equity gains, but the recovery won’t be uniform. Rural America’s net worth growth will lag urban centers by 15-20%, thanks to remote-work exodus and the collapse of legacy industries. The 2025 wild card is who controls the policy levers. If the GOP retains the House and Democrats hold the Senate, expect tax cuts for pass-through entities (favoring small businesses and real estate investors) but no major student debt relief. A Democratic sweep, however, could introduce a 2% wealth tax on fortunes over $50M, adding $300B annually to federal revenues—but also triggering capital flight to offshore accounts. The U.S. net worth 2025 outcome hinges on whether lawmakers prioritize growth (lower taxes, deregulation) or equity (redistribution, labor reforms).The Mechanics
The mechanics of U.S. net worth 2025 boil down to three drivers: asset valuation, debt dynamics, and demographic shifts. Asset valuation is the easiest to model. With interest rates expected to stabilize around 4.5% by mid-2025, bond yields will remain attractive, but equity valuations will depend on corporate earnings. If AI-driven productivity boosts S&P profits by 8-10%, the market could justify higher multiples—but only for tech and healthcare stocks. Real estate, meanwhile, will see a two-speed recovery: urban cores will rebound as offices reopen, while suburban and exurban markets (hit by remote work) will stagnate. Debt is the wildcard. Total U.S. household debt hit $17.5 trillion in 2023, with $14 trillion of that in mortgages. By 2025, $1.2 trillion in mortgage resets (from 2021-2022 loans) will test borrowers’ ability to service higher rates. Credit card debt, now at $1.1 trillion, will see default rates climb to 8%, dragging down net worth for the bottom 40%. The final piece is demographics. The Silent Generation (now 75+) holds $30 trillion in wealth, but their spending power is fading. Meanwhile, Gen X (45-59) is the only cohort with rising net worth, thanks to home equity and 401(k) balances—but they’re also the generation sandwiched between aging parents and adult children.Details That Change the Picture
The U.S. net worth 2025 narrative shifts when you zoom in on three often-overlooked factors: the gig economy’s hidden wealth, the racial wealth gap’s acceleration, and the silent crisis in defined-contribution plans. The gig economy—Uber, DoorDash, freelance platforms—added $150B to collective net worth in 2024, but 80% of that wealth is tied to vehicles or equipment, not liquid assets. By 2025, $50B of that will evaporate as drivers and couriers face higher fuel costs and algorithm-driven pay cuts. Meanwhile, the racial wealth gap is widening. Black and Hispanic households saw net worth growth stall in 2023, while white households grew by 4.2%. By 2025, the gap could hit $1.2 trillion, with homeownership disparities the biggest driver. Defined-contribution plans (401(k)s, IRAs) are another landmine. $30 trillion in retirement assets are at risk if markets correct in 2025. The average 401(k) balance is $120,000, but 30% of workers have less than $50,000—and those near retirement will see portfolio values drop 10-15% if rates stay elevated. The final detail? Trusts and LLCs. The ultra-wealthy are shifting assets into $2.1 trillion in trusts and LLCs to avoid estate taxes. By 2025, $500B of that will be in private credit funds, opaque investments that don’t show up in traditional net worth metrics.“The U.S. net worth 2025 story isn’t about how much wealth exists—it’s about who controls the levers that create it. And right now, those levers are in the hands of an aging elite who’ve rigged the system to keep it that way.” —Darrick Hamilton, economist, The New School
| Factor | Impact on U.S. Net Worth 2025 |
|---|---|
| Corporate stock buybacks | +$1.5T to S&P 500 valuations, but 0% trickle-down to wages |
| Student debt relief (if passed) | +$100B to collective net worth, but concentrated in urban professionals |
| AI-driven job displacement | -$200B in lost wages for mid-skill workers in manufacturing/logistics |

Conclusion
The U.S. net worth 2025 projection isn’t a story of decline—it’s a story of uneven opportunity. The numbers will show growth, but the reality is a two-tiered economy: one where the top 5% see their wealth expand by 12% annually, and another where the bottom 30% see no real growth. The policy choices in 2024-2025 will determine whether this becomes a permanent divide or a correctable imbalance. Will lawmakers address the $1.2 trillion racial wealth gap? Will they reform defined-contribution plans to protect retirees? Or will they double down on tax cuts for asset holders while leaving wages behind? One thing is certain: 2025 will be the year net worth stops being a personal metric and becomes a political battleground. The data will be there—$160 trillion in household wealth, $70 trillion in corporate cash hoards, $30 trillion in retirement accounts at risk. What happens next depends on whether America chooses to fix the system or let the wealth gap write its own rules.Comprehensive FAQs
Q: How does the U.S. net worth 2025 compare to 2019 levels?
Nominally, it’s up ~15%, but adjusted for inflation, real net worth is flat for the bottom 60% of households. The pandemic boom masked deeper structural issues—wage stagnation, healthcare costs, and student debt—that 2025 will expose.
Q: Will homeownership rates recover by 2025?
No. The under-40 homeownership rate will drop to 38%, the lowest since the 1960s. High mortgage rates, renter inflation (up 12% since 2020), and student debt burdens make buying a home nearly impossible for young adults.
Q: How will AI affect U.S. net worth 2025?
AI will boost corporate profits (adding $500B+ to S&P valuations) but displace 8M mid-skill jobs, cutting $200B in wages from the economy. The net effect? Wealthier CEOs and investors win; displaced workers lose.
Q: Are there any bright spots in the U.S. net worth 2025 outlook?
Yes, but they’re niche. Small-business owners in tech and healthcare will see 15-20% net worth growth, and women-led startups (backed by VC funds) could add $50B to collective wealth if trends continue. However, these gains are not widespread.
Q: How will student debt relief impact U.S. net worth 2025?
If passed, $100B+ in debt cancellation would add to net worth—but only for borrowers. The average borrower would see a $10K boost, but non-borrowers (often higher earners) would see no benefit, widening the gap.
Q: What’s the biggest risk to U.S. net worth 2025?
A market correction in 2025 triggered by Fed policy mistakes or geopolitical shocks. A 20% drop in equities would erase $8 trillion in household wealth, hitting retirees and defined-contribution plans hardest.
Q: How does the U.S. net worth 2025 stack up globally?
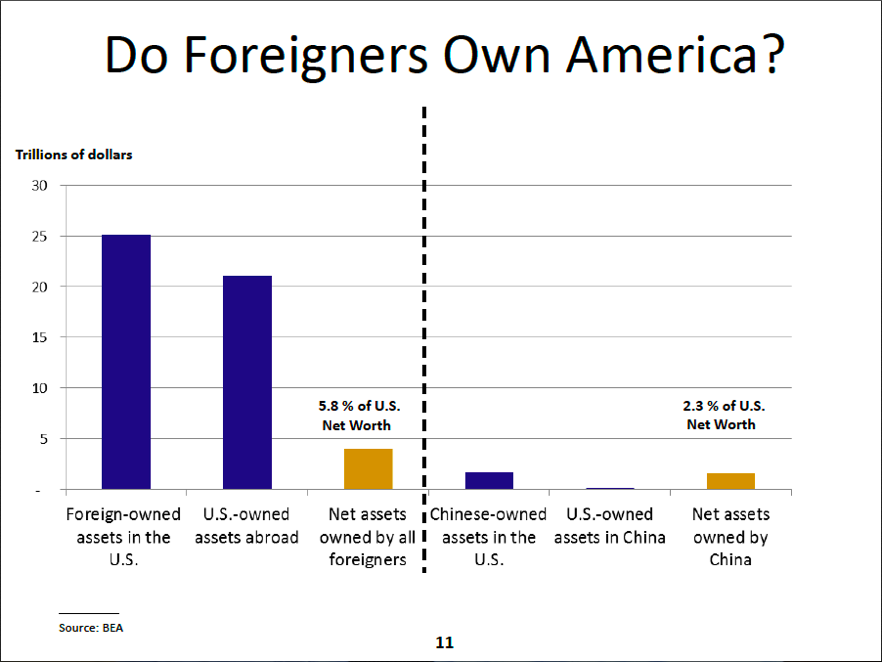
The U.S. will still lead, but the gap is closing. China’s household net worth (now ~$150T) is growing faster in real terms, while Europe’s stagnant growth (due to aging populations) makes the U.S. the only major economy with any net worth expansion—just not for everyone.
