Common Myths About How Transactions Affect Net Worth
The first misconception is that net worth is purely a function of income. High earners often assume their paychecks will translate directly into wealth, only to find their net worth stagnant after decades. The reality? Net worth growth depends on transactional efficiency—how much of each dollar retained actually compounds. A doctor earning $300,000 annually might see their net worth rise by $50,000 a year, while a software engineer on $150,000 could outpace them through lower living costs and smarter asset allocation. Another persistent myth is that liquidity equals security. People equate cash reserves with financial stability, but hoarding liquidity can be a wealth tax. Parking funds in low-yield accounts might feel safe, but it guarantees erosion over time. Meanwhile, illiquid assets like real estate or private equity can appreciate silently—if the holder avoids panic sales during downturns. The transactional trade-off here is clear: liquidity buys flexibility, but flexibility often comes at the cost of long-term growth.Myth 1: Selling an Asset Always Reduces Net Worth
The assumption that selling an asset—like a stock or property—automatically shrinks net worth ignores the role of transactional intent. Selling a losing investment to lock in a tax-loss harvest might increase net worth by creating a deduction that offsets future gains. Similarly, downsizing a home could free up cash for higher-yield investments, indirectly boosting net worth over time. The key variable isn’t the sale itself, but the strategic sequencing of transactions. What’s often overlooked is the opportunity cost of holding. A rental property might appreciate, but if its maintenance costs and vacancy rates drag down cash flow, its net worth contribution could be negative. The transactional calculus here isn’t just about the sale price, but the alternative uses of the capital freed by selling. A forced sale during a market crash might trigger a loss, but a planned sale at a peak could unlock liquidity for a higher-return opportunity.Myth 2: Debt Always Drags Down Net Worth
Low-interest debt—like a mortgage or student loans—can paradoxically increase net worth by leveraging appreciating assets. A homeowner with a $400,000 mortgage on a $600,000 property isn’t just a debtor; they’re a forced saver, with equity building over time. The transactional math shifts when debt serves as a tool rather than a burden. Even high-interest debt, like credit cards, can be reframed: paying it off aggressively might free up cash flow for investments that outpace the interest rate. The danger lies in transactional inertia—the tendency to treat all debt as uniformly destructive. A small business owner might take on high-interest loans to scale operations, knowing the revenue growth will outstrip the cost. Here, the transaction isn’t just a liability; it’s a bridge to higher-value assets. The net worth impact hinges on whether the debt accelerates or decelerates the underlying asset’s growth trajectory.Myth 3: Net Worth Only Changes with Large Transactions
The illusion of stability comes from focusing on headline events—a bonus, a bonus, a bonus. In truth, how transactions affect net worth is a compounding puzzle where small, repeated actions dominate. A daily $5 coffee habit over 20 years costs roughly $36,500—not from a single transaction, but from the aggregation of micro-decisions. Similarly, a $200 monthly subscription might seem trivial until it’s compounded against the potential returns of that capital invested elsewhere. The psychological trap is treating net worth as a snapshot rather than a process. A freelancer’s net worth might dip after a slow month, only to rebound when a client pays late. The volatility isn’t the problem; the lack of awareness around these fluctuations is. Most people don’t track the transactional velocity—how quickly money moves in and out of their control—which is why small leaks often sink even disciplined budgets.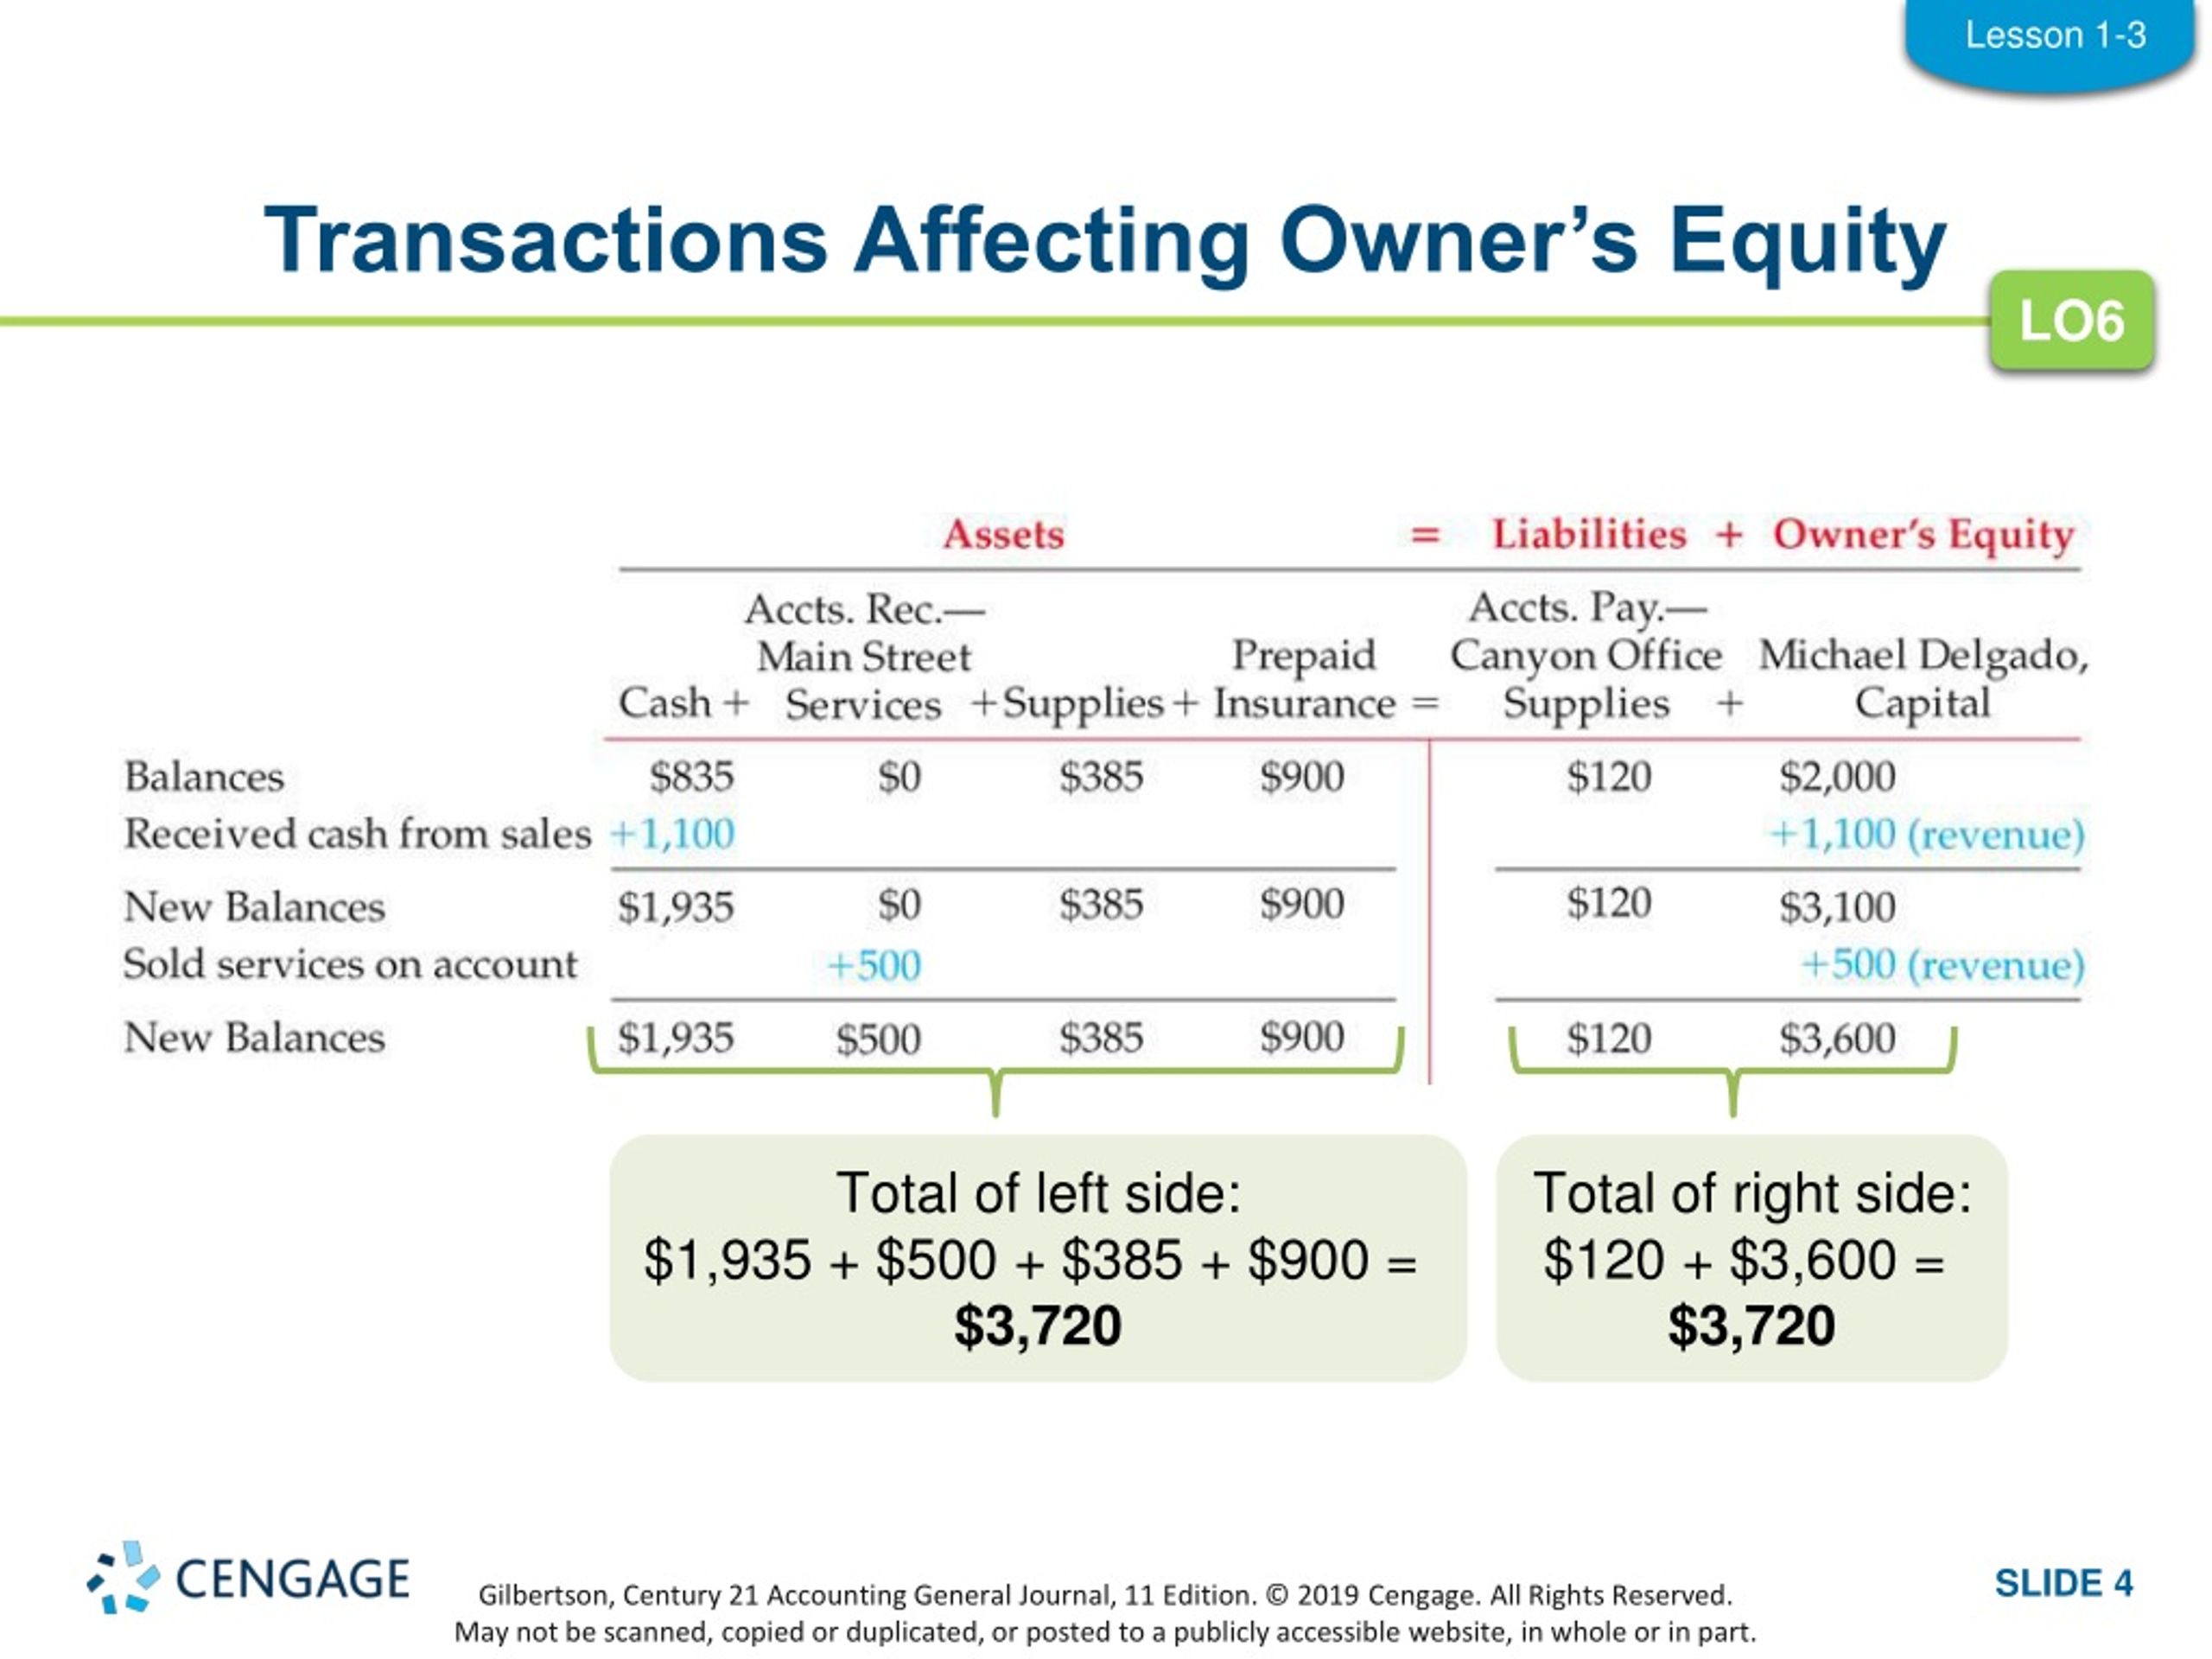
What Holds Up to Scrutiny
At its core, net worth is a measure of transactional equity—the difference between what you own and what you owe, adjusted for market realities. The verifiable principle is that how transactions affect net worth hinges on three variables: timing, leverage, and behavioral consistency. Timing matters because buying at a low and selling at a high isn’t luck; it’s a function of transactional discipline. Leverage amplifies both gains and losses, meaning debt must be deployed with precision. Behavioral consistency—avoiding emotional transactions—is the silent multiplier that separates steady growth from volatile cycles. The evidence points to a counterintuitive truth: the most reliable way to grow net worth isn’t maximizing income, but minimizing transactional drag. Fees, taxes, and inflation are the invisible taxes on wealth. A high-fee mutual fund might underperform a low-cost index fund by 1-2% annually, a gap that widens exponentially over time. The transactional cost of managing wealth isn’t just the explicit charges; it’s the opportunity cost of suboptimal decisions."Wealth isn’t about how much you earn; it’s about how much you retain after every transaction. The rich don’t think in terms of income—they think in terms of net flows." — *Morgan Housel, The Psychology of Money
| Common Belief | What the Evidence Says |
|---|---|
| Cutting expenses will directly boost net worth. | Reducing expenses can increase net worth, but only if the savings are reinvested in assets that outpace inflation. Simply saving more without deploying capital often leads to stagnation. |
| High-risk transactions (e.g., crypto, meme stocks) are the fastest way to grow net worth. | While high-risk transactions can yield outsized returns, the majority of participants lose money over time. The net worth impact is far more predictable with diversified, low-volatility strategies. |
| Real estate always appreciates, so buying property is a net worth multiplier. | Property values fluctuate with market cycles, and transaction costs (maintenance, taxes, agent fees) can erode returns. Location and timing are critical—many investors overestimate the "safe" nature of real estate. |
| Tax-loss harvesting only benefits the wealthy. | Tax-loss harvesting can offset gains for any investor, reducing taxable income. The net worth benefit scales with the size of the loss, but even small investors can use it to defer taxes. |
| Net worth is best measured annually. | Annual snapshots miss the transactional momentum—how small, repeated decisions compound. Tracking net worth monthly (or even weekly) reveals patterns that yearly reviews obscure. |
Why the Confusion Persists
The gap between perception and reality stems from two cognitive biases. First, recency bias: people overvalue recent transactions (a stock sale, a bonus) while underestimating the cumulative effect of smaller, routine ones (subscriptions, impulse buys). Second, outcome bias: we judge transactions by their end result (e.g., "I lost money on that crypto trade") rather than the process that led to it. This ignores that the same trade, executed at a different time or with different leverage, could have been profitable. Financial education often reinforces the confusion by treating net worth as a static target rather than a dynamic system. Schools teach budgeting but rarely explain how transactional sequencing matters—why paying off a mortgage early might reduce liquidity at a critical moment, or why holding an asset too long can trigger unintended tax liabilities. The result? People optimize for the wrong variables, chasing income while neglecting the friction that drains their wealth.
Conclusion
Understanding how transactions affect net worth isn’t about memorizing rules; it’s about recognizing the hidden mechanics of wealth flow. The most successful investors don’t just track assets—they audit the transactions that shape those assets. A $100,000 salary might look impressive, but if $50,000 of it is eaten by taxes, fees, and lifestyle inflation, the net worth impact is negligible. The difference between financial stagnation and growth often comes down to transactional intelligence—knowing when to hold, when to fold, and when to deploy capital strategically. The takeaway? Net worth isn’t a destination; it’s a byproduct of how you manage the ebb and flow of transactions. The best wealth builders don’t wait for windfalls—they optimize every dollar that moves through their hands. Whether it’s a $5 coffee or a $500,000 property sale, the question isn’t how much you’re spending or earning, but how those transactions align with your long-term equity.Comprehensive FAQs
Q: Does selling an asset always reduce my net worth?
A: Not necessarily. Selling an asset can increase net worth if it unlocks liquidity for higher-return investments, triggers tax benefits (like harvesting losses), or eliminates drag (e.g., selling a money-losing rental property). The key is whether the transaction improves your future cash flow or asset allocation.
Q: How do small, daily transactions (like subscriptions) impact net worth over time?
A: The effect is exponential. A $200 monthly subscription costs $2,400 annually, but over 20 years, that’s $48,000—enough to fund a down payment or invest in assets that could grow to $100,000+ with compounding. The net worth drain isn’t just the amount spent; it’s the opportunity cost of capital tied up in non-essential expenses.
Q: Can debt ever increase my net worth?
A: Yes, if the debt is used to acquire or improve an appreciating asset (e.g., a mortgage on a property in a growing market, or student loans for a high-earning career). The net worth boost comes from the asset’s growth outpacing the interest paid. However, this only works if the asset’s value rises and the debt is managed without triggering financial stress.
Q: Why does my net worth fluctuate even when my income is stable?
A: Net worth isn’t just about income—it’s about the net of all transactions. Market volatility (stocks, real estate), changes in debt levels (e.g., paying down a loan), and one-time expenses (car repairs, medical bills) can all cause swings. Even small, irregular cash flows (freelance income, bonuses) create variability. Tracking transactional velocity—how money moves in and out—reveals the real drivers.
Q: How often should I review my net worth to stay on track?
A: Monthly is ideal for most people, as it surfaces small leaks (subscriptions, impulse buys) and aligns with pay cycles. Quarterly works for those with irregular income, while annual reviews are too infrequent to catch drift. The goal isn’t perfection—it’s awareness. Even a 10-minute monthly check-in can reveal transactional patterns that derail long-term growth.
