The Complete Overview of the Calculate Net Worth Formula
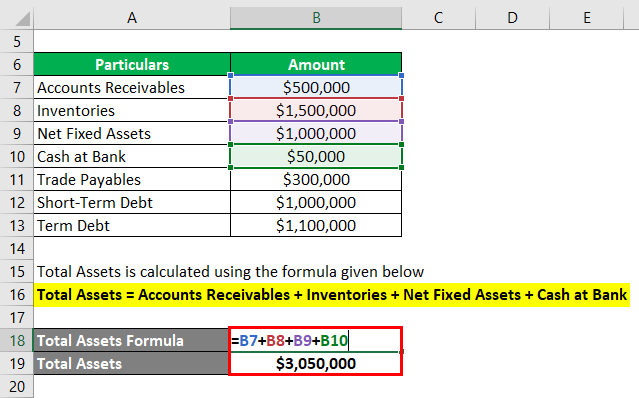
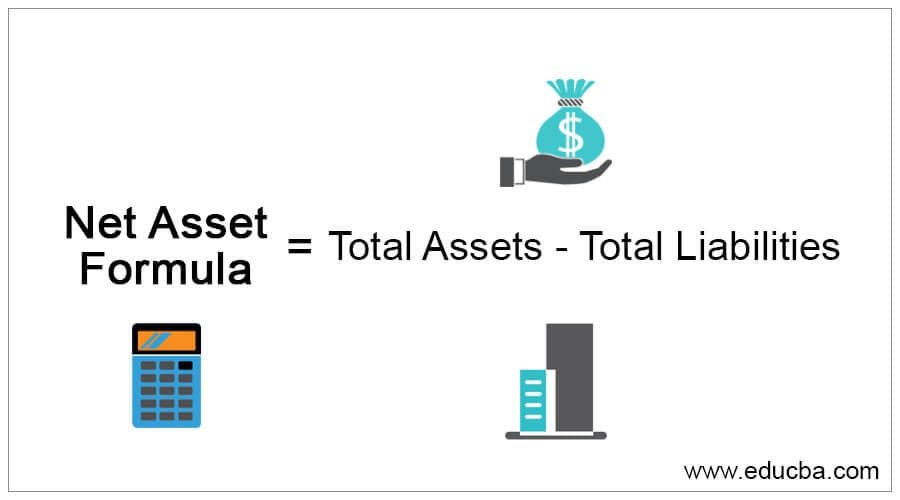
The calculate net worth formula boils down to this: Assets – Liabilities = Net Worth. Yet the devil lies in the definitions. Assets aren’t just cash or stocks; they include everything from a vintage car (if appraised properly) to the value of a side business. Liabilities, meanwhile, extend beyond mortgages to include future obligations like alimony or deferred compensation. The formula’s power lies in its simplicity, but its execution requires precision—especially when assets like real estate or private equity lack liquid market prices. What’s often overlooked is the timing of the calculation. A snapshot in January might show a net worth of £500,000, but by March, after selling a rental property at a loss and incurring legal fees, that figure could plummet. This volatility is why institutions like the Federal Reserve track household net worth quarterly: it’s not a static measure but a reflection of economic behavior. For individuals, the calculate net worth formula becomes a stress test—revealing not just wealth, but financial resilience.Historical Background and Evolution
The concept of net worth traces back to medieval merchant ledgers, where traders recorded assets (gold, spices) against debts to settle accounts. By the 19th century, industrialists like Andrew Carnegie used crude versions of the formula to justify expansions or liquidations. The modern iteration emerged in the early 20th century as accounting standards formalized balance sheets, separating personal from corporate finance. Post-WWII, the rise of consumer credit—mortgages, car loans—forced households to adopt systematic tracking, turning net worth from a business tool into a personal metric. The digital revolution transformed the calculate net worth formula into a real-time dashboard. Apps like Mint or YNAB automate asset-liability tracking, while robo-advisors integrate net worth calculations into portfolio management. Yet this convenience has a cost: algorithmic approximations often exclude illiquid assets (e.g., a family-owned vineyard) or overvalue speculative holdings (e.g., crypto). The formula’s evolution mirrors broader financial trends—from static ledgers to dynamic, data-driven assessments.Core Mechanisms: How It Works
At its core, the calculate net worth formula is a balance sheet. Assets are categorized as liquid (cash, stocks) or illiquid (property, collectibles), each requiring different valuation methods. Liabilities are split into secured (collateral-backed, like a mortgage) and unsecured (credit cards, medical debt), with the latter often carrying higher opportunity costs. The challenge isn’t the arithmetic but the subjectivity: How much is a rare first-edition book worth? Should a business’s goodwill be included if it’s not for sale? Professionals refine the formula further. For instance, financial planners may adjust for inflation or time horizons—acknowledging that a £1 million net worth at 30 looks vastly different at 60. Tax attorneys might exclude certain assets (e.g., a trust’s principal) to optimize estate planning. The formula’s flexibility is its strength, but without context, a raw net worth number is meaningless. It’s the difference between knowing your bank balance and understanding your financial health.Key Benefits and Crucial Impact
The calculate net worth formula isn’t just a vanity metric—it’s a decision-making framework. For a freelancer, it clarifies whether to take a risky new client or play it safe. For a retiree, it signals whether to downsize or tap into equity. The formula’s impact extends beyond personal finance: lenders use it to assess creditworthiness, and policymakers monitor aggregate net worth to gauge economic stability. Even philanthropists rely on it to structure donations without jeopardizing their own security. What’s often underestimated is its psychological role. Tracking net worth forces discipline—whether it’s resisting lifestyle inflation or diversifying assets. Studies show individuals who regularly compute their net worth are more likely to achieve long-term goals, not because the number itself is motivating, but because the process reveals blind spots. The formula doesn’t create wealth; it exposes the gaps where wealth can grow—or erode."Net worth is the residue of your life’s financial decisions. The formula is just the ledger—what matters is the story behind the numbers." — Jane Bryant Quinn, financial journalist and author of How to Make Your Money Last
Major Advantages
- Clarity in complexity: Distills a lifetime of financial activity into a single figure, making it easier to compare progress over time.
- Risk assessment: A declining net worth may signal overleveraging or poor investment choices before they become crises.
- Goal alignment: Helps prioritize spending (e.g., education vs. luxury) based on what net worth targets you’re chasing.
- Negotiation leverage: A high net worth can unlock better loan terms, insurance premiums, or even political influence in some contexts.
- Inheritance planning: Reveals whether assets are structured to pass efficiently to heirs or if trusts/estate tools are needed.
- Market timing insights: Sudden drops in net worth (e.g., after a stock market crash) can prompt strategic adjustments like increasing cash reserves.
Comparative Analysis
| Aspect | Calculate Net Worth Formula | Gross Income |
|---|---|---|
| Scope | Holistic (assets vs. liabilities) | Narrow (only revenue) |
| Time Sensitivity | Dynamic (fluctuates with market/liabilities) | Static (fixed to a pay period) |
| Use Case | Wealth management, risk assessment | Tax filings, budgeting |
| Limitations | Ignores non-financial factors (health, happiness) | Hides debt and asset quality |
Future Trends and Innovations
The calculate net worth formula is poised for disruption. Blockchain-based asset tracking could eliminate valuation disputes by recording ownership in real time, while AI might predict net worth trajectories based on spending patterns. For high-net-worth individuals, private equity and alternative assets (art, wine) will demand more sophisticated valuation models, possibly integrating machine learning to adjust for market sentiment. Regulatory shifts could also reshape the formula. Stricter data privacy laws might limit how institutions access asset-liability data, while central bank digital currencies could redefine what counts as "cash" in the equation. The biggest challenge? Balancing automation with human judgment—ensuring that algorithms don’t overvalue speculative assets or undercount illiquid ones.
Conclusion
The calculate net worth formula is more than arithmetic; it’s a lens through which to view your financial life. Its value lies not in the number itself but in the questions it provokes: Why is my net worth stagnant? Are my liabilities strategic or self-inflicted? The formula’s true power emerges when paired with narrative—understanding the why behind the what. For most people, the goal isn’t to chase a specific net worth target but to use the calculation as a compass, adjusting course as life’s variables shift. One thing is certain: ignoring the formula is riskier than mastering it. Whether you’re a first-time homebuyer or a seasoned investor, the discipline of regular computation—coupled with a nuanced understanding of its limitations—is the foundation of financial literacy. The numbers don’t lie, but they don’t tell the whole story either. That’s where the real work begins.Comprehensive FAQs
Q: Does the calculate net worth formula account for inflation?
A: Not automatically. The raw formula uses nominal values, so a £1 million net worth in 2010 may equate to £800,000 in 2023 terms if inflation averaged 2% annually. Adjusting for inflation requires recalculating assets/liabilities using historical price indices or a cost-of-living calculator.
Q: Should I include my pension in net worth calculations?
A: Yes, but with caveats. Defined-contribution pensions (e.g., 401(k)s) are straightforward—include the current balance. Defined-benefit pensions are trickier; estimate their present value using actuarial tables or employer projections. Never include future Social Security benefits unless you’ve secured them via a legal settlement.
Q: How often should I update my net worth?
A: At a minimum, quarterly. For volatile assets (stocks, crypto), monthly updates may be prudent. Major life events (marriage, inheritance, job loss) warrant immediate recalculations. Automated tools can simplify this, but manual reviews ensure accuracy—especially for illiquid assets.
Q: What’s the difference between net worth and liquid net worth?
A: Net worth includes all assets, even those hard to sell (e.g., a primary residence). Liquid net worth subtracts illiquid assets and adds only cash, stocks, or other quickly convertible holdings. The gap between the two reveals your financial flexibility—critical during emergencies or market downturns.
Q: Can negative net worth be useful?
A: Absolutely. A negative net worth (liabilities exceed assets) often signals opportunity. For entrepreneurs, it may reflect reinvested capital. For individuals, it can highlight areas to cut debt or build assets. The key is context: Is the negativity due to leverage (e.g., a mortgage) or mismanagement (e.g., credit card debt)?
Q: How do taxes affect the calculate net worth formula?
A: Indirectly but significantly. Tax liabilities reduce cash flow, which can delay asset accumulation. Capital gains taxes on sold assets shrink net worth upon realization. Some jurisdictions tax net worth directly (e.g., wealth taxes in Spain or Switzerland). Always compute net worth after projected tax obligations for accuracy.
Q: What’s the most common mistake people make when calculating net worth?
A: Overvaluing assets or undervaluing liabilities. Emotional attachments inflate home or car values, while ignoring future obligations (e.g., child support) distorts the picture. Another pitfall is excluding "soft" assets like professional licenses or brand equity, which can hold substantial value in the right context.
Q: Can I use the calculate net worth formula for business valuation?
A: Partially. For sole proprietorships, the formula works as-is. For corporations, you’d need to adjust for goodwill, intellectual property, and off-balance-sheet items. Accountants often use variations like EBITDA or discounted cash flow for deeper insights, but the core asset-liability principle remains foundational.
