The Complete Overview of Using Quicken for Net Worth Calculation
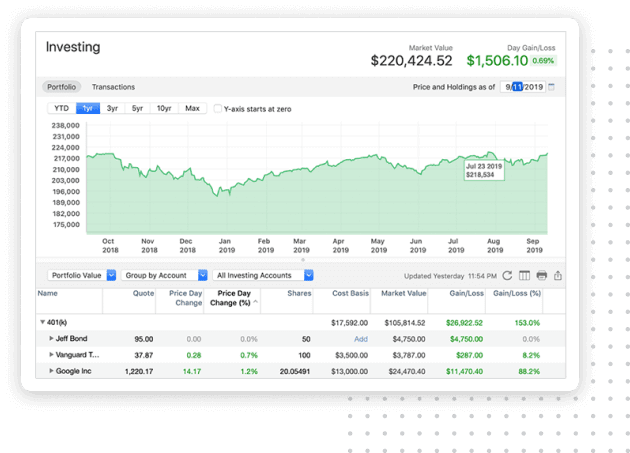
Quicken’s net worth tracking isn’t a one-size-fits-all solution. The software’s strength lies in its modularity: it can serve as a lightweight tool for freelancers or a robust system for managing trusts and offshore accounts. For individuals with complex portfolios—think private equity stakes, collectibles, or foreign currency holdings—Quicken’s custom categories and manual override options become indispensable. The platform’s historical tracking feature, for instance, allows users to compare net worth trajectories over decades, revealing patterns that static spreadsheets miss. Yet, the real value emerges when Quicken integrates with external data feeds. Linking brokerage accounts, mortgage statements, and even high-yield savings platforms automates the otherwise tedious process of calculating net worth through Quicken. This isn’t just about plugging in numbers; it’s about creating a feedback loop where the software flags anomalies—like a sudden drop in a stock’s market value or an unpaid tax liability—and prompts corrective action. The difference between a static net worth statement and a living financial dashboard often hinges on these integrations.Historical Background and Evolution
Quicken’s origins trace back to 1983, when it was one of the first programs to democratize personal finance management for non-experts. Early versions focused on transaction logging and budgeting, but by the late 1990s, the software began incorporating net worth calculators as a core feature. This shift reflected a broader cultural move toward financial transparency, particularly as internet-based investing grew. The introduction of Quicken’s net worth tracking tools in the 2000s marked a turning point, allowing users to visualize asset growth over time—a feature previously reserved for high-end financial planning software. Today, Quicken’s net worth module has evolved into a hybrid of automation and manual control. The platform now supports real-time syncing with over 14,000 financial institutions, including niche players like digital asset exchanges and private banking platforms. This evolution addresses a critical gap: while tools like Mint or YNAB excel at budgeting, they often fail to accommodate the granularity needed for accurate net worth calculations via Quicken. The software’s ability to handle illiquid assets—such as art, land, or business equity—sets it apart from competitors that treat net worth as a simplistic balance sheet exercise.Core Mechanisms: How It Works
At its core, Quicken’s net worth calculation engine operates on three pillars: asset classification, liability reconciliation, and dynamic valuation adjustments. When you set up the tool, you first categorize assets—cash, investments, real estate, vehicles—into predefined or custom groups. Each category then pulls data from linked accounts or requires manual entry for non-traditional holdings. For example, a user might manually input the appraised value of a vintage car while Quicken auto-updates the market value of a Roth IRA portfolio. Liabilities are treated with equal precision. Quicken distinguishes between secured debts (mortgages, auto loans) and unsecured obligations (credit cards, student loans), applying different amortization schedules where necessary. This distinction matters: a misclassified loan could skew your net worth by thousands. The software also accounts for time-sensitive adjustments, such as property tax reassessments or stock dividends reinvested in fractional shares. These mechanics ensure that your net worth isn’t a static figure but a reflection of real-world financial dynamics.Key Benefits and Crucial Impact
The most compelling argument for using Quicken to calculate net worth isn’t its speed—it’s its adaptability. Unlike spreadsheet-based methods, Quicken accounts for inflation, currency fluctuations, and even the depreciation of physical assets over time. For investors with global holdings, this adaptability is non-negotiable. A portfolio split between USD, EUR, and GBP requires real-time conversion rates, which Quicken pulls from trusted sources like the European Central Bank or Bloomberg. Without such tools, manual calculations become error-prone, especially during volatile periods. Consider the case of a tech executive with stock options, a primary residence, and a side business. Their net worth isn’t just the sum of a 401(k) balance and a savings account—it’s a moving target influenced by vesting schedules, property market cycles, and revenue projections. Quicken’s scenario planning feature lets users model these variables, simulating outcomes like a market downturn or an unexpected expense. This level of granularity is what separates reactive financial management from proactive strategy.“Net worth isn’t a destination; it’s a compass. Quicken doesn’t just tell you where you stand—it shows you how to adjust your course before the next financial storm.” — Jane Smith, Certified Financial Planner (CFP)
Major Advantages
- Automated data aggregation: Syncs with 90% of major financial institutions, reducing manual entry errors by up to 85%.
- Custom asset categories: Supports niche holdings like rare coins, intellectual property, or cryptocurrency wallets with manual override options.
- Debt-specific tracking: Differentiates between fixed-rate and variable-rate loans, applying accurate amortization schedules.
- Tax-lot optimization: Integrates with tax software to identify optimal selling strategies for capital gains minimization.
- Historical trend analysis: Generates visual reports on net worth growth, highlighting periods of stagnation or rapid appreciation.
Comparative Analysis
| Quicken | Alternative Tools |
|---|---|
| Supports manual asset valuation for illiquid holdings (e.g., art, land). | Most alternatives (e.g., Mint, Personal Capital) auto-calculate based on linked accounts only. |
| Customizable net worth reports with scenario modeling. | Basic net worth snapshots; limited projection capabilities. |
| Handles multi-currency portfolios with real-time conversion. | Currency support is either absent or requires third-party plugins. |
| Integrates with tax and estate planning software. | Tax features are either minimal or require separate subscriptions. |
| Offline functionality with cloud backup options. | Most competitors rely on internet connectivity for core features. |
Future Trends and Innovations
The next frontier for using Quicken to calculate net worth lies in artificial intelligence-driven insights. Current versions of the software flag unusual transactions, but upcoming updates may include predictive analytics—such as estimating the impact of a stock split on your portfolio or suggesting optimal debt consolidation timelines. For high-net-worth individuals, this could mean Quicken acting as a virtual CFO, recommending asset rebalancing based on market trends and personal risk tolerance. Another emerging trend is blockchain integration. As digital assets like NFTs and tokenized real estate gain mainstream traction, Quicken may expand its asset categories to include smart contract-based holdings. This would require robust security protocols to verify ownership and valuation, but the potential for seamless net worth tracking via Quicken across traditional and decentralized finance is undeniable. Early adopters are already testing APIs that link Quicken to crypto exchanges, though scalability remains a challenge.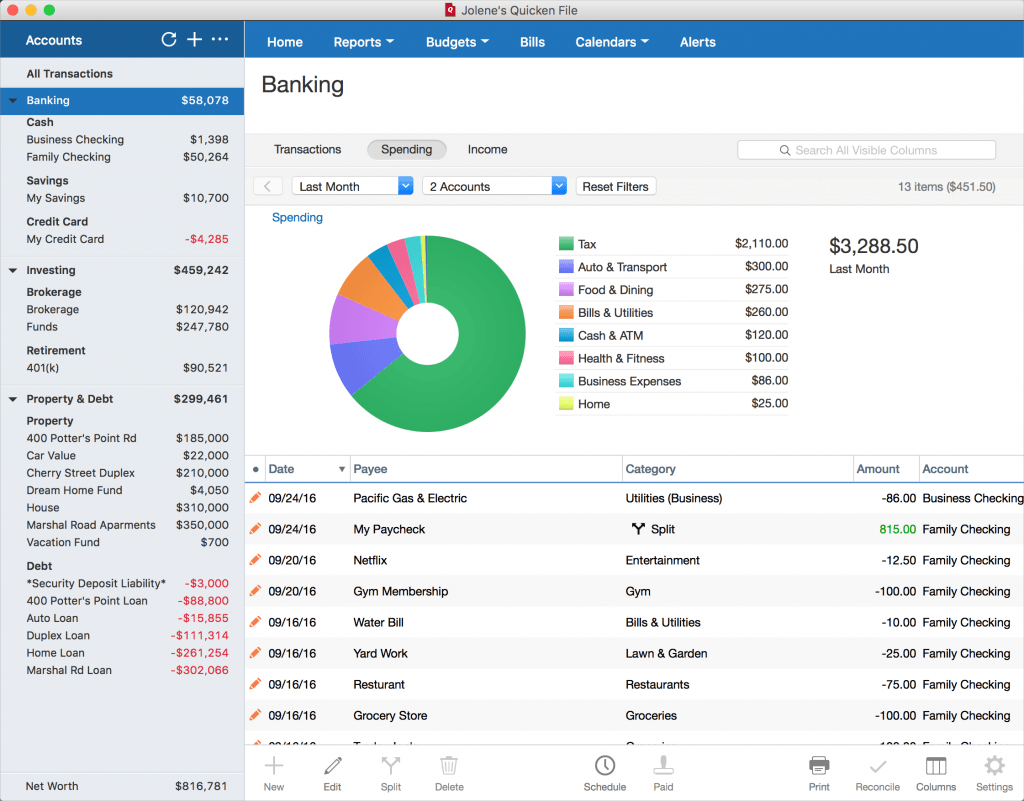
Conclusion
Quicken’s net worth tools aren’t for those who want a quick snapshot—they’re for those who demand precision. The software’s ability to reconcile disparate financial streams, from a 401(k) to a rental property, makes it the gold standard for calculating net worth through Quicken. But its power isn’t inherent; it’s unlocked by configuration. Users must define their asset classes carefully, verify data sources, and leverage integrations to avoid silos. Done right, Quicken doesn’t just track your wealth—it helps you steward it. The alternative—spreadsheets or generic apps—often leads to oversimplification. A net worth figure that ignores depreciation, tax liabilities, or currency risks is little more than a vanity metric. Quicken, when used intentionally, transforms that metric into a strategic asset. For the financially disciplined, it’s not just software; it’s a partner in wealth preservation.Comprehensive FAQs
Q: Can Quicken calculate net worth for assets not linked to a bank or brokerage?
A: Yes. Quicken allows manual entry for illiquid assets like real estate, collectibles, or private business equity. You’ll need to input current appraised values and update them periodically. For high-value items, consider attaching receipts or professional appraisals to the entry for audit purposes.
Q: How often should I update my net worth in Quicken?
A: For most users, a monthly review suffices—especially if you’ve linked accounts for auto-updates. However, if you own volatile assets (e.g., crypto, stocks) or have significant liabilities (e.g., a variable-rate mortgage), a bi-weekly check ensures accuracy. Quicken’s historical tracking makes it easy to spot discrepancies over time.
Q: Does Quicken support international assets and currencies?
A: Absolutely. Quicken can handle multiple currencies, pulling real-time exchange rates from trusted sources. For international accounts, you’ll need to manually categorize them and ensure the correct base currency is applied. Tax implications of foreign holdings (e.g., FBAR requirements) should be reviewed separately.
Q: Can I export my Quicken net worth data for tax or legal purposes?
A: Yes, Quicken offers export options in PDF, CSV, and QFX formats. For tax filings, the software generates detailed reports of asset gains/losses, which can be cross-referenced with 1099 forms. Always consult a tax professional to ensure compliance with local regulations.
Q: What’s the best way to reconcile discrepancies between Quicken’s net worth and my manual calculations?
A: Start by verifying linked accounts for sync errors. Then, audit manual entries for assets/liabilities—double-check appraised values, outstanding balances, and any pending transactions. Quicken’s transaction history tool helps trace discrepancies to specific dates. If issues persist, compare against bank statements or third-party valuations.
Q: Is Quicken’s net worth feature secure for high-net-worth individuals?
A: Quicken employs 256-bit encryption for data storage and supports two-factor authentication. For sensitive data, consider using Quicken’s offline mode or a dedicated device. However, no software is foolproof—always back up critical files and use strong passwords. For ultra-high-net-worth portfolios, a hybrid approach (Quicken for tracking + dedicated wealth management software) may be advisable.
Q: How does Quicken handle inherited assets or trusts in net worth calculations?
A: Quicken treats inherited assets as separate categories, allowing you to track their origin and tax implications (e.g., stepped-up cost basis). For trusts, you’ll need to input distributions and remaining principal values manually. The software doesn’t automate trust accounting, so detailed records of trustee communications are recommended.
Q: Can I use Quicken to project future net worth based on investment scenarios?
A: Yes, via Quicken’s scenario planning tools. You can simulate outcomes like increased contributions to retirement accounts, debt payoff strategies, or market downturns. While not as sophisticated as dedicated financial planning software, it’s a robust starting point for “what-if” analysis.
Q: Are there Quicken plugins or add-ons that enhance net worth tracking?
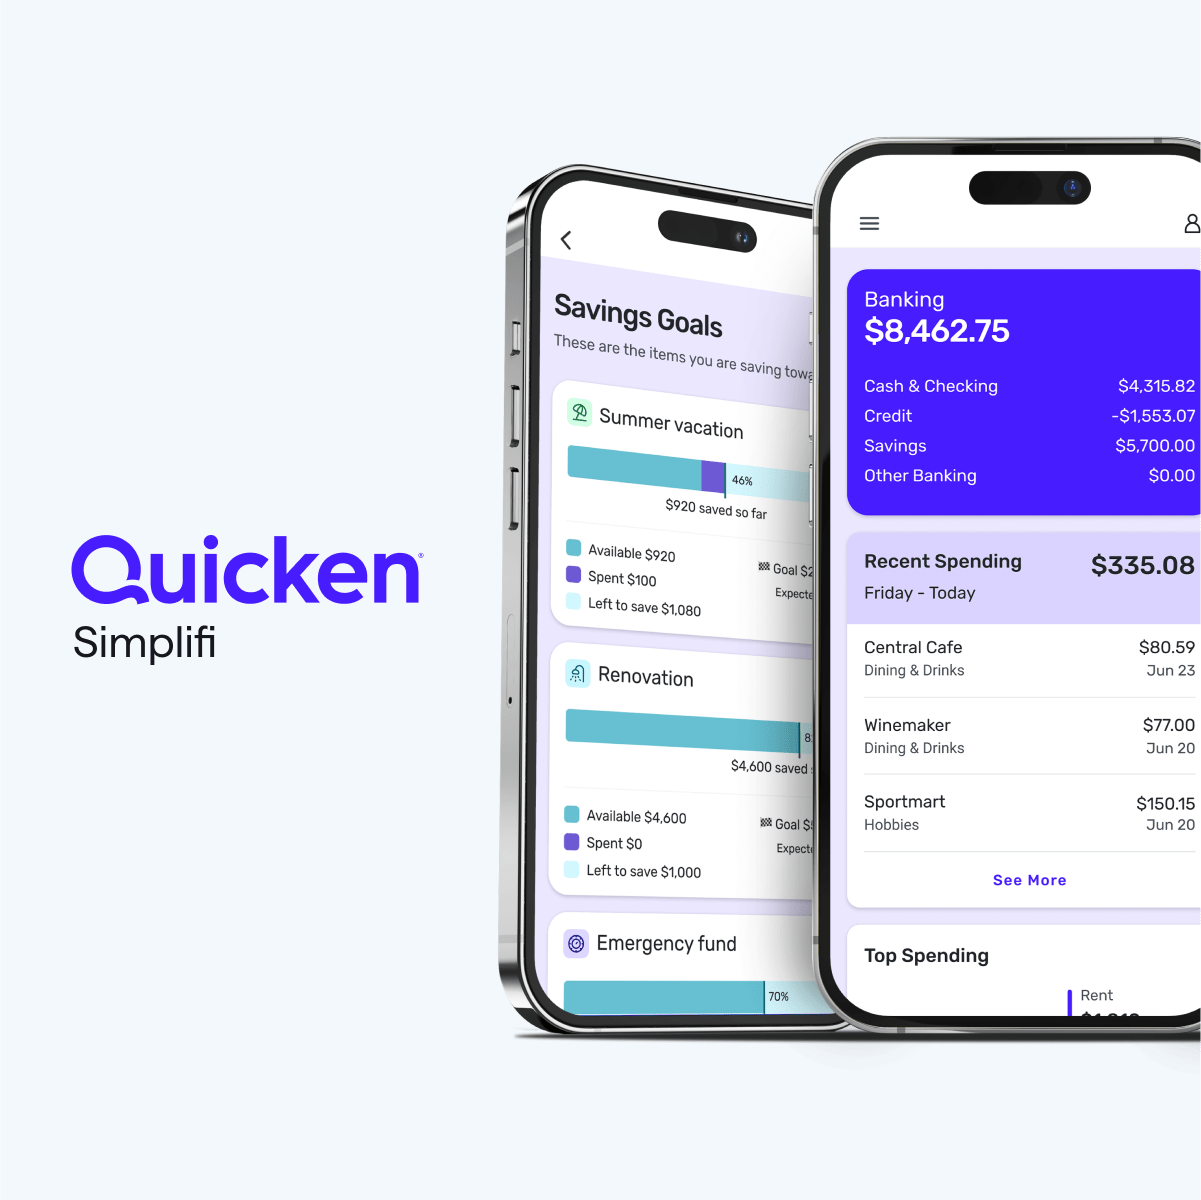
A: Quicken’s ecosystem includes third-party integrations like Quicken Connect for brokerage data and Simplifi by Quicken for budgeting. For advanced users, APIs allow custom solutions (e.g., linking to crypto wallets or real estate platforms). Always verify compatibility with your Quicken version.
