The Short Answers
- Your net worth on a personal balance sheet is simply assets minus liabilities—but the real value comes from categorizing each line item.
- Liquid assets (cash, investments) should be listed at fair market value; illiquid assets (real estate, art) require professional appraisals or conservative estimates.
- Debt is split into "good" (mortgage, student loans for income-generating degrees) and "bad" (consumer debt, leveraged speculation).
- Non-financial assets (skills, social capital) can’t be quantified but often drive long-term wealth more than balance sheet numbers.
- Updating your sheet quarterly—even roughly—catches trends before they become crises.
- Tools like YNAB or spreadsheets automate calculations, but manual review ensures accuracy for unique assets (e.g., a rental property’s true cash flow).

Deep Dive: The Full Picture
A personal balance sheet isn’t just a ledger; it’s a stress test for your financial assumptions. For example, a tech executive might list stock options as an asset, but their real value hinges on vesting schedules and company performance—factors absent from a static number. Meanwhile, a freelancer’s net worth might plummet if a key client vanishes, yet their sheet could still show "high" equity if they’ve overvalued their equipment. The sheet’s utility depends on how aggressively you challenge its numbers. A passive approach turns it into a vanity metric; an active one reveals leverage points. The sheet also exposes the hidden volatility in personal finance. A retiree’s net worth might appear stable on paper, but if their portfolio is heavy in low-yield bonds, inflation erodes purchasing power faster than the balance sheet suggests. Similarly, a homeowner’s equity can vanish overnight if property values correct—yet the sheet might still show a high figure if they haven’t adjusted for market conditions. The discipline of recalculating forces you to confront these gaps.The Context You Need
Historically, balance sheets were tools for merchants and landowners—people with tangible assets to protect. Today, the average net worth includes intangibles: digital assets (domain names, YouTube channels), human capital (a physician’s earning potential), and even social capital (networks that generate opportunities). The challenge is translating these into sheet-compatible figures. A musician’s "brand value" isn’t a line item, but their ability to monetize it through sponsorships or merch might offset the low valuation of their physical instruments. The rise of gig economies and alternative investments (crypto, NFTs) has further blurred the lines. A crypto holder’s net worth can swing 50% in a month, yet traditional balance sheets treat it like a stock—ignoring the speculative nature of the asset class. The solution isn’t to exclude these items but to flag them as "high-risk" or "illiquid" in the sheet’s notes section. Clarity requires honesty: If you’re holding Bitcoin as a speculative play, label it as such. If it’s part of your core portfolio, treat it like any other volatile asset.The Mechanics
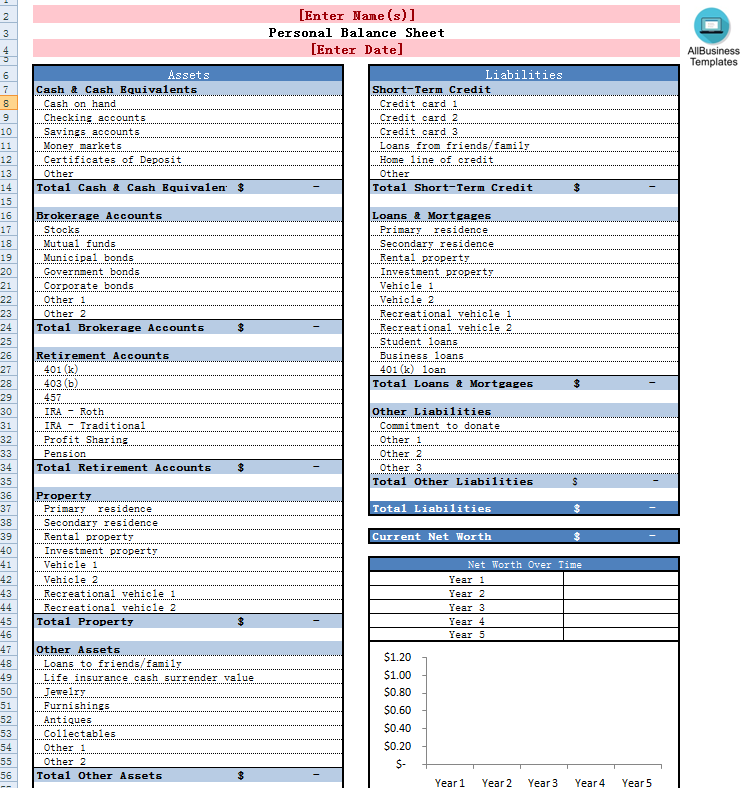
Start with three columns: assets, liabilities, and net worth. Assets are divided into: - Liquid: Cash, checking/savings, brokerage accounts, retirement funds (valued at current market prices). - Illiquid: Primary residence (valued via Zillow or appraisal), secondary properties, collectibles (appraised or insured value), and business equity (if applicable). - Non-financial: Skills, health, time—these don’t appear on the sheet but are critical to long-term wealth. Liabilities are split into: - Current: Credit card balances, medical debt, short-term loans. - Long-term: Mortgages, student loans, car loans (amortized over remaining terms). - Contingent: Legal judgments, co-signed debts, or guarantees you’ve issued. The net worth figure emerges from the difference, but the real work is in the footnotes. For example: - A rental property’s "value" might be listed at purchase price, but its true contribution is net operating income (NOI) minus expenses. - A side business’s equity could be overstated if it’s not generating revenue; adjust for burn rate or unsold inventory.Details That Change the Picture
Most people stop at the net worth number, but the asset allocation tells the story. A portfolio skewed toward a single employer’s stock (e.g., a Microsoft employee holding 90% in MSFT) is riskier than one diversified across asset classes. Similarly, a balance sheet heavy in home equity but low in liquid savings is vulnerable to market downturns or emergency needs. The sheet’s power lies in spotting these imbalances before they become crises. Taxes and inflation distort the sheet’s accuracy. A high net worth in nominal terms can shrink when adjusted for inflation—especially for retirees relying on fixed-income assets. Meanwhile, capital gains taxes might eat into realized profits, turning paper gains into after-tax losses. The solution is to run two versions of the sheet: one at market value (for planning) and one at "after-tax, after-inflation" value (for realism)."A balance sheet is like a medical exam: It only helps if you act on the results. Too many people look at their net worth and pat themselves on the back—then ignore the warning signs in the details." — Jane Bryant Quinn, financial journalist and author of How to Make Your Money Last
| Common Mistake | Correction |
|---|---|
| Valuing a business at purchase price (even if it’s a side hustle). | Estimate based on revenue multiples or replacement cost. For example, a freelance designer earning $100K/year might be worth 2–3x annual profit if the business is scalable. |
| Ignoring inflation in long-term liabilities (e.g., a 30-year mortgage). | Adjust the remaining balance for expected inflation—typically 2–3% annually—to reflect true debt burden. |
| Treating all debt equally (e.g., lumping a mortgage with credit card debt). | Separate "good debt" (mortgages, student loans for high-ROI fields) from "bad debt" (consumer loans, leveraged bets). |
| Overvaluing sentimental assets (e.g., a inherited watch or family heirloom). | Use insurance appraisals or liquidation values—not emotional attachment—as the basis for valuation. |

Conclusion
The most valuable balance sheets aren’t the ones with the highest net worth figures but those that force their owners to confront hard truths. A sheet that’s updated monthly—even roughly—reveals spending leaks, investment missteps, and opportunities to deploy capital more effectively. The key is to treat it as a dynamic tool, not a static report. For example, if your net worth stagnates for three years, the sheet might show why: Are you saving aggressively but earning stagnant income? Or are you spending down assets faster than you’re accumulating new ones? Ultimately, the sheet’s purpose isn’t to judge your worth but to clarify your options. A high net worth with no liquidity is like a vault full of gold bars you can’t access. A low net worth with high human capital (e.g., a young professional with a growing career) might be far more resilient. The sheet’s real value is in the questions it provokes: Where are my biggest risks? What assets are illiquid when I need them most? How does my partner’s financial picture interact with mine? Answering these turns numbers into strategy.Comprehensive FAQs
Q: Should I include my pension or 401(k) in my net worth on a personal balance sheet?
A: Yes, but clarify whether it’s the current market value (for planning) or the future payout value (for retirement projections). Most people list the account balance at fair market value, but if you’re near retirement, factor in withdrawal strategies and tax implications. For defined-benefit pensions, estimate the present value of future payments using a discount rate (typically 3–5%).
Q: How do I handle assets I co-own with a partner or family member?
A: Split the asset’s value proportionally if ownership is clear (e.g., 50/50 in a joint bank account). For complex situations (like inherited property with multiple heirs), note the undivided interest and consult an estate planner. If assets are held in a trust or LLC, list them at fair market value but document the legal structure in the sheet’s notes. Never assume "shared" means "equal"—clarify ownership percentages first.
Q: What’s the best way to track non-financial assets like skills or health?
A: These don’t appear on the balance sheet, but you can create a separate "human capital" ledger to track: - Income-generating skills (e.g., a coder’s ability to command higher salaries). - Health metrics (e.g., life expectancy adjustments for chronic conditions). - Network value (e.g., high-net-worth contacts or mentors). Use qualitative notes (e.g., "High earning potential in AI field") alongside quantitative proxies (e.g., "Salary growth rate: +8% annually"). The goal isn’t to assign dollar values but to identify risks (e.g., a skill becoming obsolete) and opportunities (e.g., a health scare prompting insurance reviews).
Q: How often should I update my net worth on a personal balance sheet?
A: Quarterly is ideal for most people, but adjust based on volatility: - High volatility: Monthly (e.g., if you hold crypto, trade stocks, or have variable income). - Stable: Bi-annually (e.g., if your assets are mostly real estate, bonds, or steady employment). - Retirement phase: Annually, with deeper dives before major decisions (e.g., downsizing a home). Automate updates for liquid assets (bank accounts, investments) but manually review illiquid ones (property appraisals, business valuations). The sheet’s accuracy depends on consistency, not perfection.
Q: Can I use my net worth on a personal balance sheet to qualify for loans or financial products?
A: No, not directly. Lenders care about liquid assets, income, and debt-to-income ratios, not your total net worth. However, a well-documented balance sheet can: - Strengthen your case for private loans or business credit by proving asset-backed collateral. - Help secure home equity lines of credit (HELOC) if your primary residence is a high-value asset. - Serve as a negotiation tool for better terms if you’re a high-net-worth individual (though banks often verify independently). For most consumer products (mortgages, credit cards), they’ll pull your credit report—not your personal balance sheet. Use the sheet internally to identify liquidity gaps before applying.
Q: What’s the difference between a personal balance sheet and a net worth statement?
A: Technically, they’re the same—both show assets minus liabilities. The difference lies in depth and purpose: - Net worth statement: A simplified version, often used for quick checks (e.g., "I’m at $500K"). It may lump categories (e.g., "Investments" without breaking down stocks vs. real estate). - Personal balance sheet: A detailed breakdown with: - Subcategories (e.g., "Taxable brokerage" vs. "Retirement accounts"). - Notes on valuation methods (e.g., "Primary home valued at $850K via Zillow Zestimate, pending appraisal"). - Contingent liabilities (e.g., "Guaranteed $20K student loan for niece"). Use the statement for high-level tracking and the sheet for strategic decisions (e.g., refinancing, estate planning).
Q: How do I handle assets in different currencies or countries?
A: Convert all values to your functional currency (the one you use for daily expenses) at the spot rate on the valuation date. For example: - A Swiss bank account in CHF should be converted to USD/EUR at the current exchange rate. - Foreign real estate should be appraised in local currency, then converted. Key considerations: - Tax implications: Some countries tax worldwide assets; others only local ones. Consult a cross-border tax advisor. - Political risk: Assets in unstable currencies or jurisdictions may need a liquidity discount (e.g., "Value adjusted for 15% estimated devaluation risk"). - Repatriation costs: Factor in fees for transferring funds (e.g., wire transfer costs, capital controls). Document the conversion method in your sheet’s notes to avoid disputes with tax authorities.
