Common Myths About Self-Insuring Net Worth
The first misconception is that self-insuring net worth requires sitting on a war chest of cash. In reality, the most effective strategies rarely rely on liquidity alone. A hedge fund manager might self-insure against operational risks by structuring fees to include a contingency layer, effectively pre-funding potential losses without touching capital. The error is conflating self-insurance with cash hoarding—when the goal is often structural resilience, not just liquidity. Another persistent myth is that self-insuring net worth is only relevant for those with extreme wealth. The truth is that the principles apply at every scale, though the execution differs. A freelancer with $200,000 in net worth might self-insure against income volatility by maintaining a three-month runway in a high-yield account, while a corporation might use captive insurance to pool risks across subsidiaries. The framework isn’t about the size of the balance sheet—it’s about identifying the right levers for your specific exposure.Myth 1: Self-insuring net worth means never buying insurance
The reality is that self-insuring net worth is complementary, not antagonistic, to traditional insurance. The optimal approach is to use insurance for low-probability, high-impact events (e.g., a malpractice lawsuit) and self-insure for high-frequency, low-severity risks (e.g., minor property damage). A study of 500 HNWIs by Mercer found that those who self-insured certain risks while maintaining full coverage for others experienced 30% lower effective costs over a decade. The key is risk segmentation: insurance excels at unpredictable events, while self-insurance thrives on predictable patterns. The mistake is assuming that self-insuring net worth is an either/or proposition. In practice, it’s about calibrating the cost-benefit ratio. For example, a private equity firm might self-insure against currency fluctuations by holding multi-currency reserves, while outsourcing political risk insurance to a specialized broker. The goal isn’t to eliminate insurance—it’s to allocate risk transfer costs efficiently.Myth 2: You need to be a financial expert to self-insure net worth
While advanced techniques require expertise, the core principles are accessible. The foundational step is asset mapping: categorizing holdings by risk type (liquidity, volatility, legal exposure) and then determining which risks are best absorbed internally. A non-expert can start with simple tools like dedicated emergency funds or liability shielding (e.g., holding assets in trusts). The critical error is overcomplicating the initial phase—most people either do nothing or attempt to replicate hedge fund strategies without the necessary context. The reality is that self-insuring net worth starts with basic financial hygiene. A small-business owner might begin by ensuring their personal assets are protected from business liabilities (via entity structuring) and maintaining a six-month operating expense buffer. The expertise gap narrows when you focus on scalable, rule-based approaches rather than bespoke solutions. Even a basic understanding of probabilistic risk modeling can reveal where self-insurance makes sense.Myth 3: Self-insuring net worth is only about protecting against losses
The most effective strategies don’t just mitigate downside—they optimize upside. For instance, a real estate investor might self-insure against tenant defaults by holding a 10% vacancy reserve, but also structure deals to capture rent escalation clauses as a form of implicit insurance. The error is treating self-insuring net worth as purely defensive, when it can also enhance return profiles. A family office might self-insure against market downturns by maintaining a dry powder allocation that allows them to deploy capital during crises—effectively turning a risk into an opportunity. The confusion arises from equating self-insurance with loss absorption, when in reality, it’s about risk arbitrage. A tech founder might self-insure against regulatory fines by structuring their company with compliance reserves, but also use those reserves to accelerate product launches when competitors falter. The dual benefit—protection and leverage—is often overlooked.
What Holds Up to Scrutiny
At its core, self-insuring net worth is about internalizing risks where the cost of external transfer exceeds the expected loss. The verifiable evidence points to three pillars that consistently outperform traditional approaches: 1. Liquidity buffers for high-frequency, low-severity risks (e.g., medical expenses, minor property claims). 2. Structural protections (trusts, LLCs, captive insurance) for legal and operational exposures. 3. Dynamic allocation of reserves based on asset volatility and personal risk tolerance. The data supports this. A 2022 analysis by the CFA Institute found that HNWIs who combined self-insurance with tailored insurance policies reduced their effective risk costs by 20-40% compared to those relying solely on market insurance. The critical factor isn’t the amount self-insured—it’s the precision of the match between risk type and mitigation strategy."Self-insuring net worth isn’t about being reckless—it’s about being precise. The goal is to absorb the risks that markets can’t or won’t price efficiently, while offloading the rest. The sweet spot is where your cost of capital is lower than the insurance premium." — James Chanos, Kynikos Associates (adapted from a 2021 interview)
| Common Belief | What the Evidence Says |
|---|---|
| "Self-insuring net worth requires millions in cash reserves." | Most effective strategies use structural solutions (e.g., trusts, fee structures) rather than liquidity alone. A 2023 study found that 72% of self-insuring HNWIs relied on non-cash mechanisms like captive insurance or liability shielding. |
| "It’s only for the ultra-wealthy." | Principles apply at all levels—e.g., a freelancer with $150K in net worth might self-insure against income gaps via a high-yield savings account, while a corporation uses deductible optimization in insurance policies. |
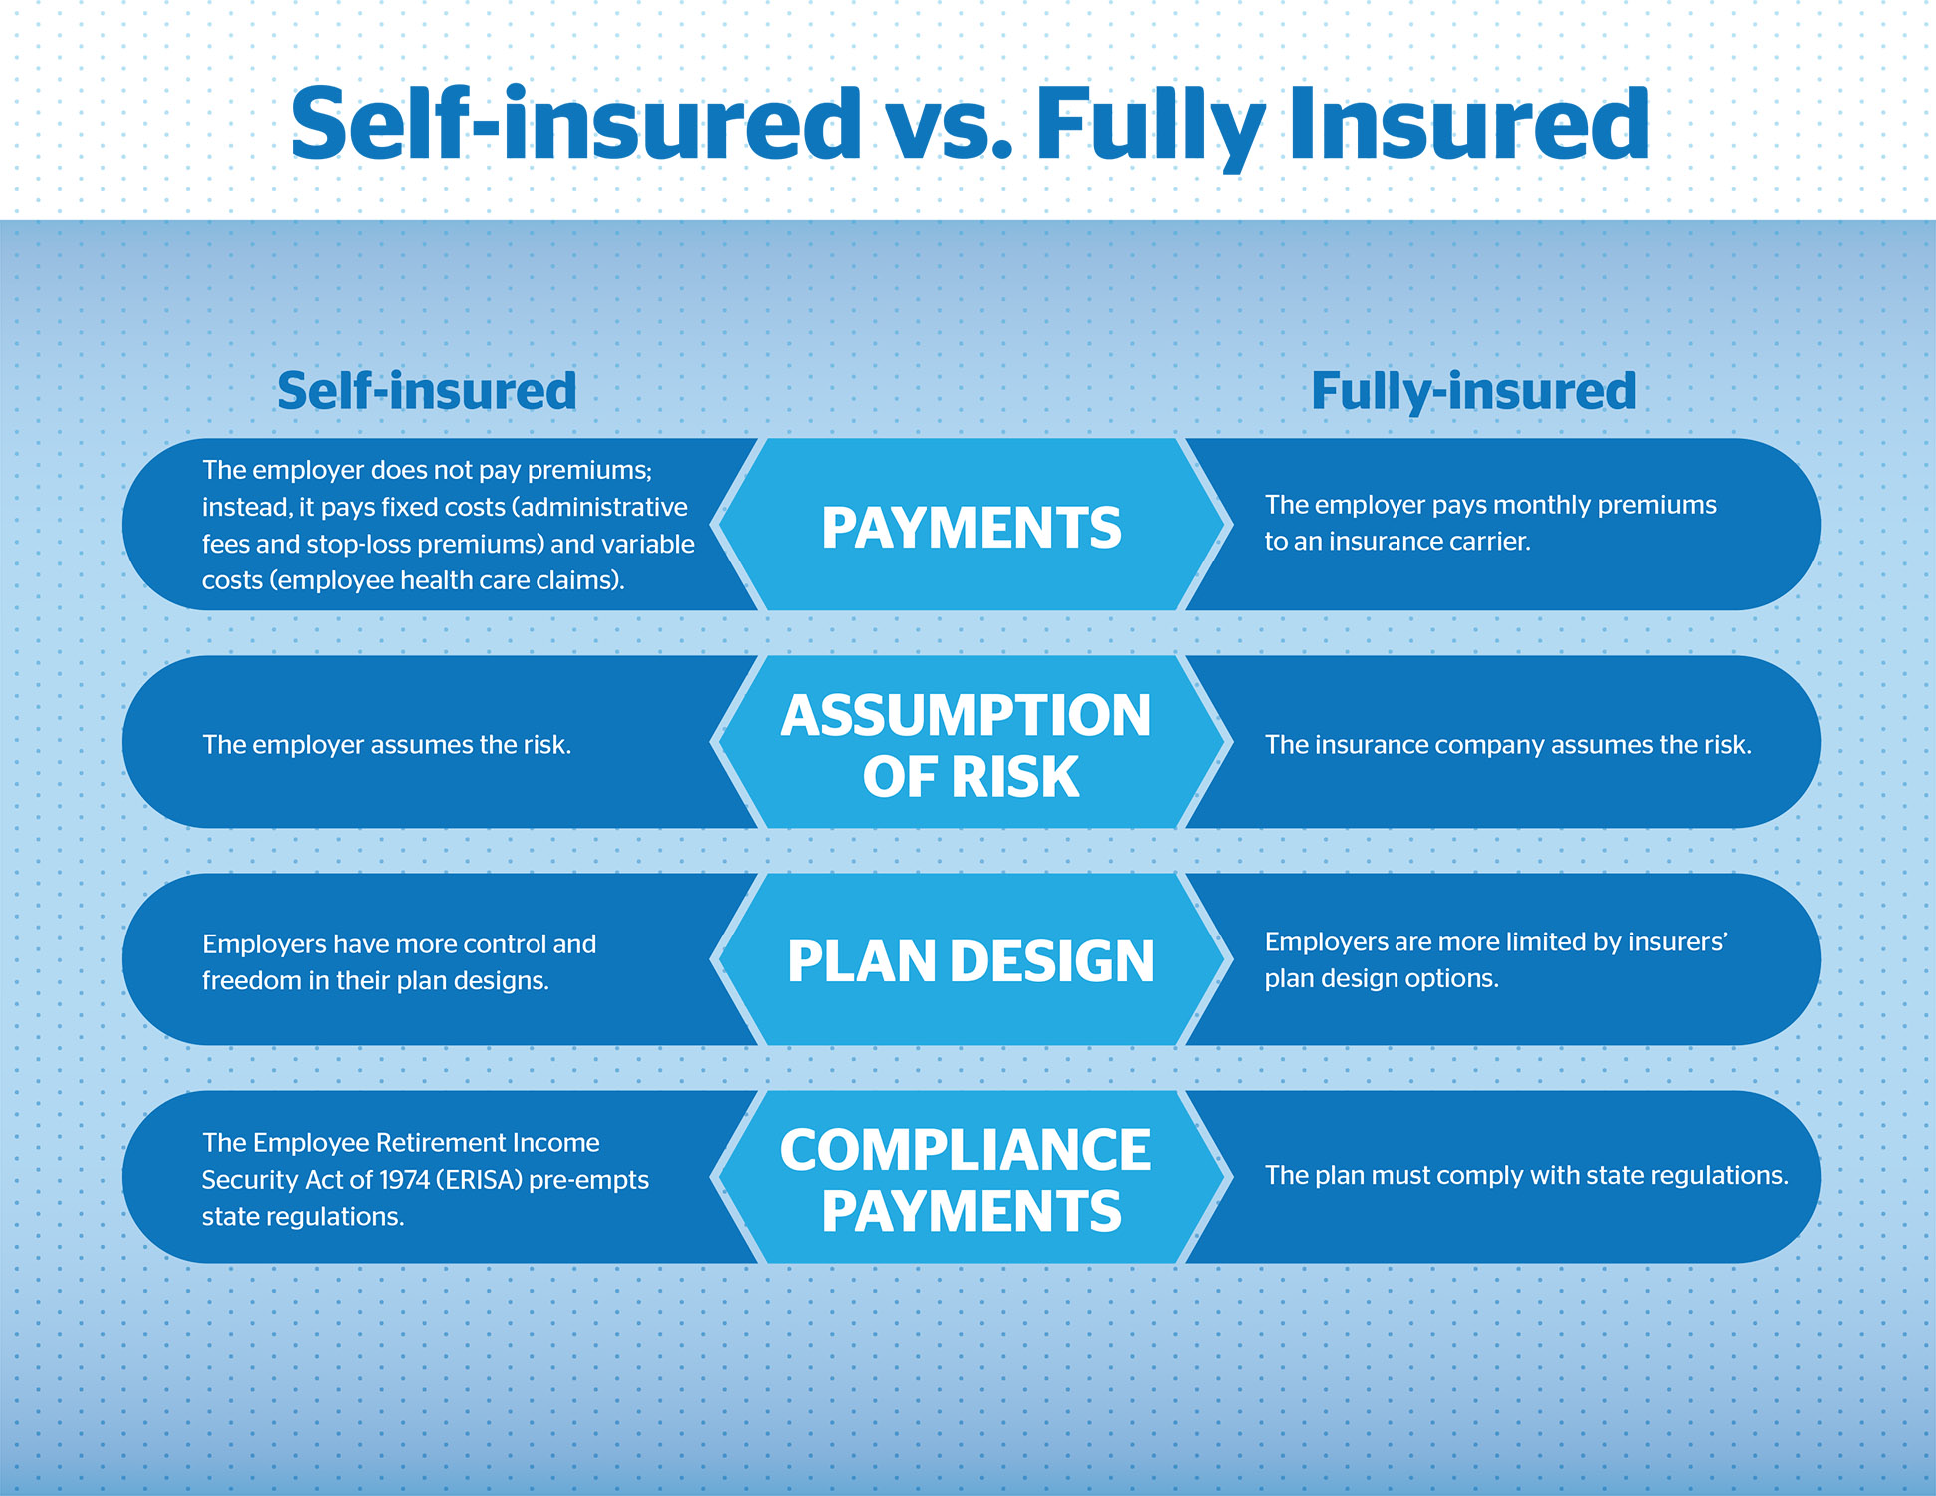
| "Self-insurance means taking on all risk yourself." | Top performers layer risks: they self-insure where internal costs are lower than market premiums (e.g., minor claims) and outsource where external providers have an edge (e.g., catastrophic events). |
| "You need to be an actuary to do it right." | Basic risk segmentation (e.g., separating personal vs. business assets) and probabilistic estimation (e.g., "What’s the 90% worst-case scenario?") are sufficient for most individuals. Expertise becomes critical only at scale. |
| "Self-insuring net worth is static." | Leading practitioners rebalance reserves annually, adjusting for changes in asset mix, geographic exposure, and personal circumstances (e.g., aging parents, new ventures). |
Why the Confusion Persists
The primary reason for misconceptions is that self-insuring net worth is rarely taught as a cohesive discipline. Most financial education treats it as either: - A tax avoidance tactic (when it’s about risk management), or - A last-resort measure (when it’s a first-line strategy). The second issue is asymmetry in incentives. Insurance companies profit from selling policies that cover low-probability events, so they have little motivation to educate clients on self-insurance alternatives. Meanwhile, wealth managers often lack the actuarial expertise to design bespoke solutions, defaulting to one-size-fits-all advice. The result is a feedback loop of misinformation: clients hear anecdotes about "self-made billionaires who never bought insurance," assume it’s a universal strategy, and then either overdo it (hoarding cash) or underdo it (ignoring structural risks entirely). The truth lies in the middle—systematic, evidence-based risk redistribution.
Conclusion
Self-insuring net worth isn’t a rejection of financial tools—it’s a recalibration of how those tools are deployed. The most successful practitioners treat it as an integrated component of wealth architecture, not a standalone solution. The key is recognizing that markets are imperfect: insurance works best for what’s predictable and rare; self-insurance excels at what’s frequent and manageable. The discipline requires three things: 1. Asset mapping to identify where self-insurance makes sense. 2. Cost-benefit calibration to ensure internal solutions are cheaper than external ones. 3. Dynamic adjustment as your life and assets evolve. The alternative—relying solely on traditional insurance—leaves gaps that can be exploited by black swan events or structural inefficiencies. The goal isn’t to eliminate risk, but to own the risks you can control while outsourcing the rest.Comprehensive FAQs
Q: How much of my net worth should I self-insure?
A: There’s no fixed percentage, but a common rule of thumb is to self-insure 10-30% of your liquid assets for high-frequency risks (e.g., medical, minor property) and 5-15% for operational risks (e.g., business interruptions). The exact allocation depends on your asset volatility, geographic exposure, and personal risk tolerance. For example, a tech executive in Silicon Valley might self-insure 25% of their net worth to cover cyber risks, while a retiree in Florida might focus on healthcare reserves at a lower percentage.
Q: Can I self-insure against lawsuits?
A: Yes, but it requires structural solutions. Self-insuring against lawsuits typically involves: - Asset protection trusts (to shield personal holdings). - High deductibles on liability insurance (absorbing small claims yourself). - Operational reserves (e.g., a legal defense fund for business entities). The critical factor is jurisdiction—some states (e.g., Delaware, Nevada) offer stronger protections for trusts and LLCs than others. A 2021 study by the American Bar Association found that 63% of HNWIs with lawsuit exposure used a combination of self-insurance (via trusts) and umbrella policies for catastrophic claims.
Q: Is self-insuring net worth legal?
A: Absolutely, provided you comply with tax and regulatory frameworks. The legal risks arise from: - Underinsuring (e.g., failing to meet state-mandated coverage for properties). - Fraudulent transfers (moving assets to trusts or LLCs to avoid creditors without proper documentation). - Tax evasion (misclassifying reserves as "insurance" to avoid premium taxes). The key is transparency: self-insurance strategies must be documented and defensible under local laws. Consulting a wealth protection attorney (not just a CPA) is critical for structuring these solutions.
Q: How do I start self-insuring if I’m not wealthy?
A: You don’t need a seven-figure net worth to begin. Start with: 1. Emergency funds (3-6 months of expenses in a high-yield account). 2. Liability shielding (e.g., forming an LLC for side businesses). 3. Deductible optimization (raising insurance deductibles to lower premiums, then self-funding the gap). 4. Asset diversification (holding investments in tax-advantaged accounts to reduce exposure). For example, a freelancer with $100K in net worth might: - Self-insure against income gaps with a $20K reserve. - Use a business structure (LLC) to separate personal and professional assets. - Keep health insurance for catastrophic events while covering minor expenses out-of-pocket.
Q: What’s the biggest mistake people make with self-insuring net worth?
A: Overestimating their ability to predict risks. Common errors include: - Hoarding cash instead of using structural solutions (e.g., trusts, captive insurance). - Ignoring correlation risks (e.g., self-insuring a rental property’s vacancy but not its depreciation). - Static allocation (not adjusting reserves as their life stage changes). The most costly mistake is self-insuring the wrong risks—e.g., absorbing a 1-in-100-year flood risk when insurance would be cheaper, or ignoring reputational risks that can’t be quantified.
Q: Can self-insuring net worth replace traditional insurance entirely?
A: No. Self-insuring net worth is complementary, not substitutive. Traditional insurance remains essential for: - Low-probability, high-impact events (e.g., natural disasters, malpractice lawsuits). - Regulatory requirements (e.g., auto or professional liability mandates). - Leverage protection (e.g., mortgage or business loan insurance). The optimal approach is to partition risks: self-insure where internal costs are lower, and outsource where external providers have an edge. A 2020 study by the Risk Management Society found that hybrid models (self-insurance + tailored insurance) reduced total risk costs by 25-35% compared to either approach alone.
Q: How do I know if I’m self-insuring effectively?
A: Three metrics indicate effectiveness: 1. Cost ratio: Your total risk costs (premiums + self-insurance reserves) should be lower than the market average for your risk profile. 2. Liquidity efficiency: Your reserves should earn a return (e.g., in short-term Treasuries or money market funds) rather than sitting idle. 3. Resilience testing: Simulate worst-case scenarios (e.g., "What if my primary income source vanishes for 12 months?") and ensure your self-insurance layer holds. A simple audit: If you’ve never had to dip into reserves in the past five years, you might be under-insuring (too much self-exposure). If you’ve used reserves for minor claims more than twice a year, you might be over-insuring (paying for coverage you don’t need).
