The Complete Overview of Improving the Debt-to-Net-Worth Ratio
The debt-to-net-worth ratio is a silent stress test for financial health. Unlike credit scores or liquidity ratios, it doesn’t trigger alarms until the damage is visible. A ratio above 50% signals vulnerability; above 70%, it becomes a red flag for lenders and a ticking clock for individuals. The ratio isn’t static—it shifts with market cycles, career changes, or unexpected expenses. What’s considered "safe" varies by age, income stability, and asset volatility. A 60-year-old with a diversified portfolio might tolerate a 60% ratio; a 30-year-old in a cyclical industry should aim lower. The real challenge isn’t calculating the ratio (assets minus liabilities, divided by net worth) but interpreting it. A high ratio isn’t always a crisis—it could reflect strategic borrowing (e.g., a real estate investor with leveraged properties). The key is contextual leverage: debt that generates cash flow (rental properties, business loans) behaves differently than debt that drains it (consumer loans, high-interest credit). The goal isn’t to chase a specific percentage but to ensure debt aligns with long-term wealth creation.Historical Background and Evolution
The concept of debt-to-net-worth as a financial health metric gained traction in the 1980s, as personal finance shifted from savings-driven models to asset-based wealth building. Before then, debt was often stigmatized—associated with recklessness or desperation. The rise of home equity loans, student debt, and credit cards in the late 20th century forced a reckoning: debt could be a tool or a trap, depending on how it was managed. The 2008 financial crisis exposed the dangers of treating debt as free money, with millions seeing their net worth evaporate overnight while debt remained. Today, the ratio is used by financial advisors, lenders, and even courts to assess risk. High-net-worth individuals often target ratios below 30% for liquidity and flexibility, while entrepreneurs might accept higher ratios if their debt is income-producing. The evolution reflects a broader shift: from debt avoidance to debt optimization—where the focus is on improving the quality of leverage, not just reducing its quantity.Core Mechanisms: How It Works
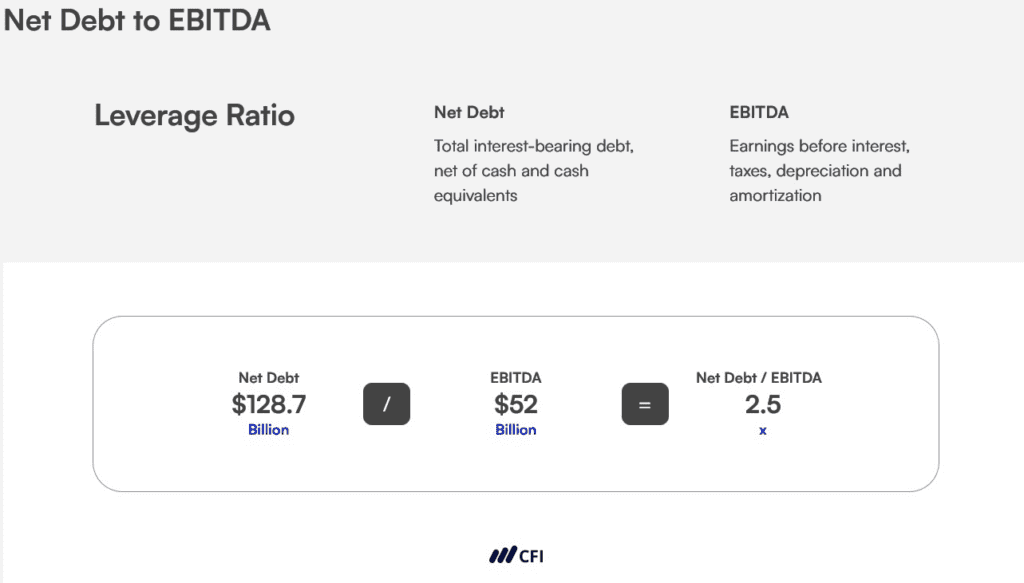
The ratio is calculated as: Total Debt ÷ Net Worth = Debt-to-Net-Worth Ratio Net worth = Total Assets – Total Liabilities. The ratio reveals how much of your wealth is encumbered by debt. A 40% ratio means 40% of your net worth is tied up in obligations. The lower the ratio, the more financial breathing room you have. Improving the ratio isn’t just about paying down debt—it’s about accelerating asset growth while slowing debt accumulation. For example, a freelancer with £100,000 in net worth and £60,000 in debt (60% ratio) could improve their position by: 1. Refinancing high-interest debt (e.g., credit cards) into a lower-rate personal loan. 2. Investing the savings from refinancing into index funds or rental properties. 3. Increasing income to offset debt service costs, thereby raising net worth faster. The mechanics hinge on asymmetric effort: a £1 reduction in debt has the same impact as a £1 increase in net worth, but the latter compounds over time.Key Benefits and Crucial Impact
A well-managed debt-to-net-worth ratio isn’t just a number—it’s a buffer against life’s disruptions. It improves access to credit during emergencies, reduces stress from financial uncertainty, and enhances negotiating power with lenders. Studies show individuals with ratios below 40% recover faster from economic downturns, as their assets retain more value relative to liabilities. The ratio also acts as a financial early-warning system, flagging over-leveraging before it becomes critical. For high-earners, the ratio can unlock opportunities. A ratio below 30% might qualify you for premium lending terms, while a ratio above 60% could limit options during a business expansion. The impact extends beyond personal finance: a strong ratio can influence divorce settlements, inheritance disputes, or even business valuations."Debt is like a drug—it can stimulate growth, but the withdrawal symptoms are brutal. The difference between a healthy ratio and a toxic one isn’t the amount of debt; it’s whether the debt is working for you or against you." — Jane Bryant Quinn, Personal Finance Columnist
Major Advantages
- Enhanced liquidity: Lower ratios free up cash flow for investments or emergencies.
- Stronger credit resilience: Lenders view lower ratios as lower risk, improving borrowing terms.
- Tax efficiency: Strategic debt (e.g., mortgages) can offset taxable income, improving net worth.
- Legacy protection: A lower ratio ensures more wealth transfers to heirs or charitable causes.
Comparative Analysis
| Metric | High Debt-to-Net-Worth Ratio | Low Debt-to-Net-Worth Ratio |
|---|---|---|
| Liquidity | Restricted; limited emergency funds | High; flexible for opportunities |
| Credit Access | Limited; higher interest rates | Premium terms; lower costs |
| Wealth Growth | Slower; debt service eats returns | Faster; assets compound unencumbered |
| Risk Tolerance | Low; vulnerable to shocks | High; absorbs market volatility |
Future Trends and Innovations
The rise of fintech and AI-driven financial tools is making it easier to monitor and optimize the debt-to-net-worth ratio in real time. Apps now simulate how refinancing or asset purchases would impact the ratio, while robo-advisors suggest debt payoff strategies tied to market conditions. However, the biggest shift may come from behavioral finance: as younger generations prioritize financial wellness over traditional markers of success, the stigma around debt is fading—but so is the tolerance for reckless leverage. Another trend is the asset-class diversification approach, where individuals balance high-growth assets (tech stocks, private equity) with low-risk liabilities (mortgages, student loans). This hybrid strategy aims to improve the ratio by ensuring debt is offset by appreciating assets, not just cash reserves.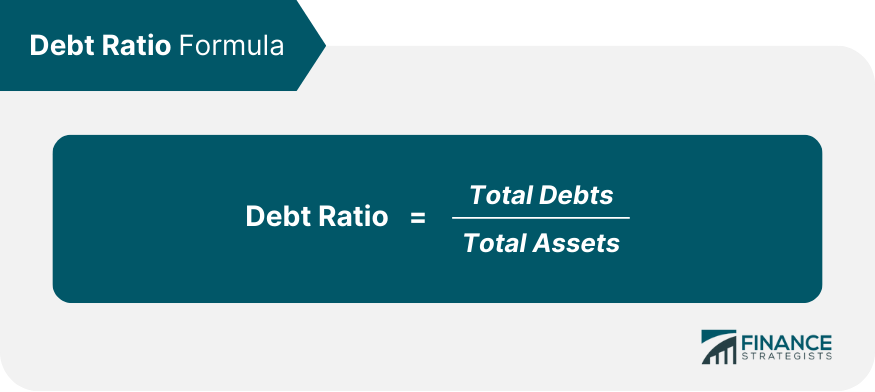
Conclusion
Improving the debt-to-net-worth ratio isn’t about deprivation—it’s about strategic allocation. The best ratios aren’t achieved by slashing spending but by aligning debt with assets that generate returns. For some, this means aggressive paydown; for others, it’s refinancing or restructuring. The common thread is intentionality: every debt decision should either preserve or enhance net worth. The ratio is a living document, not a static target. It evolves with career stages, market cycles, and personal goals. The discipline to track and adjust it isn’t just financial—it’s a mindset that separates those who weather storms from those who sink under them.Comprehensive FAQs
Q: Is there a universally "good" debt-to-net-worth ratio?
A: No. A ratio below 30% is ideal for most, but entrepreneurs or investors may tolerate higher ratios if their debt is income-generating. Context matters—age, income stability, and asset volatility all play a role.
Q: Can refinancing improve my ratio even if I don’t pay down debt?
A: Yes. Refinancing high-interest debt into a lower-rate loan reduces monthly payments, which can free up cash for investments—indirectly improving the ratio by increasing net worth faster.
Q: Does student loan debt affect the ratio differently than a mortgage?
A: Yes. Mortgages are often secured by appreciating assets, while student loans are typically unsecured and non-income-producing. The latter drags down net worth more severely.
Q: How often should I recalculate my ratio?
A: At least annually, or after major financial events (refinancing, inheritance, job change). Quarterly checks are ideal for those with volatile incomes or high debt levels.
Q: Can improving my ratio help me qualify for a better mortgage rate?
A: Absolutely. Lenders use the ratio to assess risk. A lower ratio signals stability, which can unlock better terms—especially for high-value loans.
Q: What’s the fastest way to improve the ratio if I’m in a tight spot?
A: Prioritize high-interest debt payoff (credit cards, personal loans) while maintaining minimum payments on secured debt. Simultaneously, liquidate non-essential assets to boost net worth.
