Breaking Down the Numbers
The math behind retiring based upon net worth is deceptively simple. At its core, it’s about ensuring your portfolio’s withdrawal rate won’t deplete your capital over time. The 4% rule—withdrawing 4% annually and adjusting for inflation—has been the gold standard for decades. But its origins (a 1994 Trinity Study) assumed a 30-year retirement horizon, a 50/50 stock-bond split, and U.S. market conditions. Today’s retirees face lower bond yields, higher healthcare costs, and longer lifespans. Adjusting for these variables means the "safe" withdrawal rate might now be closer to 3.5% or even lower for some. The problem isn’t the rule itself—it’s the assumption that one size fits all. A software engineer in Austin with a $2.5 million net worth and $150,000 in annual expenses might calculate a 6% withdrawal rate (4% rule) and think they’re safe. But if half that net worth is tied up in a primary residence with no equity, or if their portfolio is skewed toward real estate during a downturn, the math breaks down. Retiring based upon net worth requires stress-testing scenarios: What if the market drops 30% in Year 1? What if inflation spikes to 6%? What if you live to 95?The Verified Baseline
Public data on those who’ve successfully retired based upon net worth is scarce, but a few patterns emerge. The earliest adopters—often tech workers or entrepreneurs—tended to have high savings rates (50%+ of income) and low baseline expenses. A 2021 study by the Journal of Financial Planning found that individuals who retired early via net worth typically had portfolios valued at at least 25x their annual spending, but with significant variations by region. For example: - In low-cost areas (e.g., rural Midwest, Southeast Asia), the baseline might be closer to $800,000 for a $32,000/year lifestyle. - In high-cost cities (San Francisco, New York), the same lifestyle could require $3 million or more. What’s verifiable is that retiring based upon net worth isn’t about quitting a job—it’s about replacing earned income with passive returns. The IRS doesn’t recognize "early retirement" as a financial milestone; it’s a personal threshold. That’s why tax-efficient withdrawals (e.g., Roth conversions, capital gains management) become critical. The most successful cases involve treating retirement as a phased transition, not an overnight pivot.What the Estimates Suggest
Industry estimates paint a broader picture, though with caveats. According to Vanguard’s 2023 retirement projections, a couple retiring at 60 with a $2 million portfolio (assuming a 3.5% withdrawal rate) has roughly a 90% chance of not outliving their money over 30 years. However, if that same couple lives in a state with high taxes (e.g., California, New York) or has significant healthcare costs, the odds shift. Retiring based upon net worth in such cases often requires supplemental income streams—rental properties, side businesses, or part-time work—to bridge gaps. Another estimate, from Fidelity Investments, suggests that the average American needs $1.5 million to retire comfortably, but this is a median, not a rule. A 2022 Spectrem Group survey found that high-net-worth individuals (defined as $1M+ in investable assets) who retire early tend to have diversified income sources: 60% rely on Social Security, 30% on pensions, and 20% on side hustles. The key takeaway? Retiring based upon net worth isn’t just about the number—it’s about designing a withdrawal strategy that accounts for taxes, sequence risk, and personal resilience.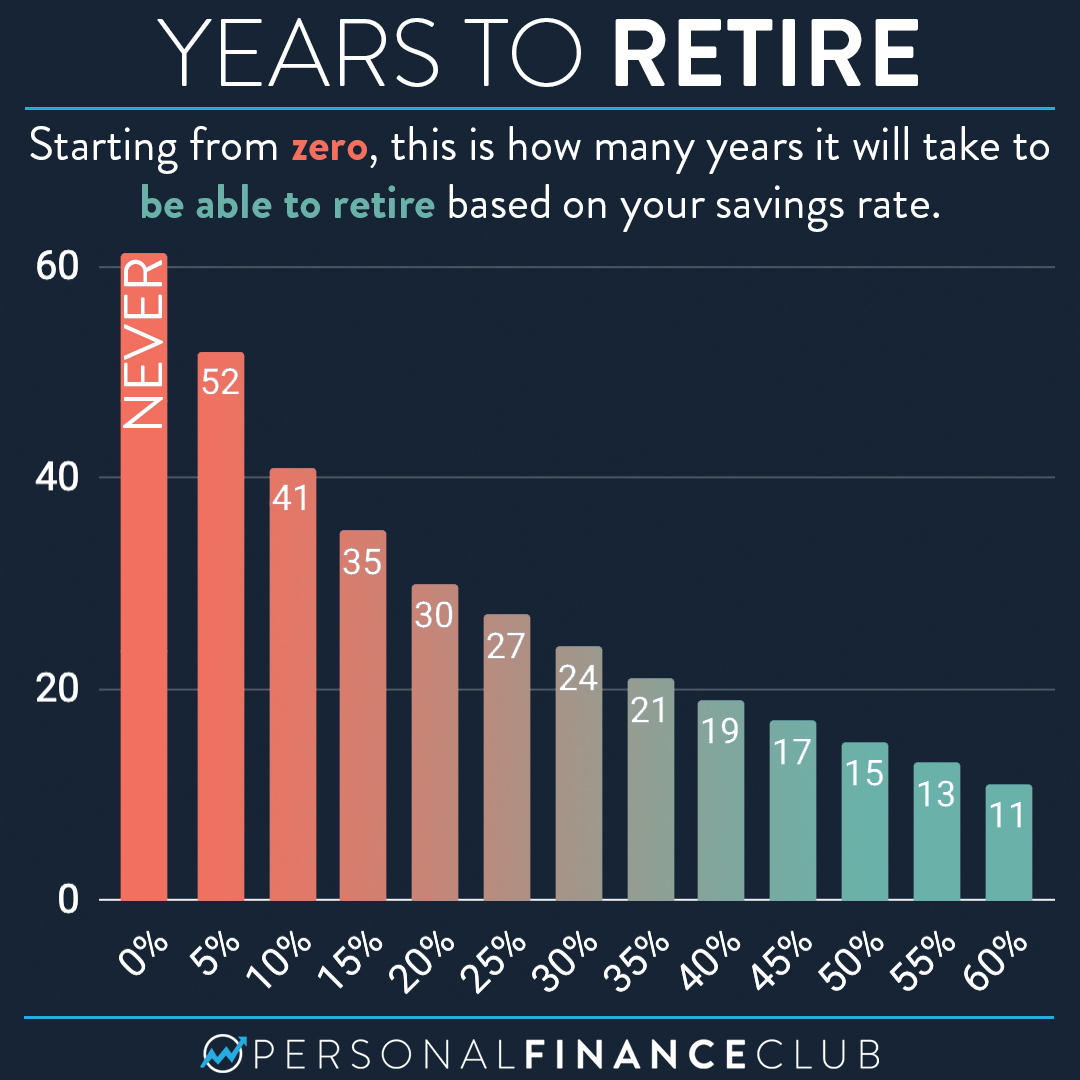
Case Study: A Closer Look
Consider the case of Mark, a 42-year-old financial analyst who retired in 2018 with a net worth of $1.8 million. His annual expenses were $60,000, but his portfolio was concentrated in low-cost index funds and a rental property in Texas. Mark didn’t follow the 4% rule rigidly; instead, he adopted a "flexible spending" approach, adjusting withdrawals based on market performance. In years when his portfolio grew, he increased contributions to a Roth IRA. When it declined (e.g., 2022), he tapped into cash reserves first. > "The biggest mistake people make is treating retirement as a static number," Mark said in a 2020 interview with Morningstar. "I treat it like a business—if revenue (investments) drops, I cut costs (travel, discretionary spending) until it recovers. The goal isn’t to never work again; it’s to work on my own terms." His strategy relied on three levers:| Factor | Estimated Impact |
|---|---|
| Portfolio Allocation | 70% equities (S&P 500), 20% bonds, 10% real estate — adjusted annually based on age. |
| Withdrawal Strategy | 3.2% in low-market years, 4.5% in high-growth years (never exceeding 4% consecutively). |
| Tax Optimization | Roth conversions in low-income years, capital gains deferred until needed. |
What This Means Going Forward
The rise of platforms like Personal Capital and YNAB has democratized retirement planning, but the data shows a growing divide. Those who retire based upon net worth successfully tend to share three traits: 1. They treat retirement as a process, not an event. Most don’t quit cold turkey; they transition over 1–3 years, testing passive income against expenses. 2. They prioritize liquidity over illiquid assets. A $5M portfolio with $4M in a private business isn’t the same as $5M in diversified ETFs. 3. They plan for the "unretirement" phase. Many return to part-time work or consulting within 5–10 years—not because they need to, but because they miss structure. The biggest shift ahead? Retiring based upon net worth is no longer a binary choice. With remote work and gig economies thriving, the new frontier is "semi-retirement"—where individuals scale back but maintain income streams. The numbers are still critical, but the psychology of purpose is becoming equally important.
Conclusion
The myth of retiring based upon net worth is that it’s a math problem with a single answer. In truth, it’s a dynamic equation where variables change with age, health, and market conditions. The 4% rule is a tool, not a doctrine. Location matters. Taxes matter. Even your zip code matters. What doesn’t matter? Assuming you can plug numbers into a calculator and walk away. The most sustainable approach isn’t about hitting a static target—it’s about building a system that adapts. That system requires discipline in saving, flexibility in spending, and foresight in tax planning. For those who master it, retiring based upon net worth isn’t about freedom from work; it’s about freedom to choose—whether that means traveling, volunteering, or launching a passion project. The numbers are the foundation. The rest is up to you.Comprehensive FAQs
Q: Is the 4% rule still reliable for retiring based upon net worth?
A: The 4% rule remains a starting point, but its reliability depends on your portfolio composition, withdrawal strategy, and market conditions. Studies suggest it may be too aggressive for today’s lower bond yields, with some advisors recommending 3.5% or lower for added safety. Always stress-test your plan with a financial advisor.
Q: Can I retire based upon net worth if most of my wealth is tied up in my home?
A: Only if you can access that equity without triggering major tax liabilities or disrupting your lifestyle. Home equity is illiquid—selling may not be feasible if you need cash flow. Alternatives include a HELOC (home equity line of credit) or downsizing, but both have trade-offs. Liquidity is key for retiring based upon net worth.
Q: How do taxes affect retiring based upon net worth?
A: Taxes can erode your portfolio faster than market downturns. Required Minimum Distributions (RMDs) from traditional IRAs start at 73, pushing retirees into higher tax brackets. Strategies like Roth conversions in low-income years or municipal bonds can mitigate this. Ignoring taxes is the fastest way to deplete your net worth prematurely.
Q: Is retiring based upon net worth realistic for average earners?
A: It’s possible but requires extreme savings rates (50%+ of income) and low baseline expenses. The median U.S. household can’t retire early via net worth without aggressive lifestyle adjustments or non-traditional income sources (e.g., side businesses, rental income). For most, it’s a long-term play, not a quick exit.
Q: What’s the biggest mistake people make when retiring based upon net worth?
A: Assuming their expenses will stay the same. Lifestyle inflation, healthcare costs, and unexpected expenses (e.g., home repairs, long-term care) can derail even well-planned retirements. The most successful retirees budget for 20–30% higher expenses in early retirement to account for these variables.
Q: Can I retire based upon net worth if I have student debt?
A: It’s far harder, but not impossible. High-interest debt (e.g., private loans) should be prioritized for repayment before retirement. If your debt is low-interest (e.g., federal student loans), you might structure retirement around debt-free cash flow. However, most financial planners recommend paying off all non-mortgage debt before attempting early retirement.
