
Where It All Began
The concept of tracking net worth dates back to the 18th century, when merchants in Europe and the Americas began recording their total financial position—not just income, but the value of their ships, warehouses, and inventory. These early ledgers weren’t just for accountants; they were survival tools. A merchant’s net worth determined his creditworthiness, his ability to secure loans, and even his social standing. The first standardized frameworks emerged in the 19th century with the rise of double-entry bookkeeping, but it wasn’t until the 20th century that personal net worth statements became a cornerstone of financial planning for the middle class. The real turning point came in the 1970s, when financial advisors began treating net worth as more than a snapshot—it became a dynamic tool for goal-setting. The shift from static to strategic was driven by two forces: the proliferation of tax-advantaged accounts (like IRAs) and the realization that liabilities weren’t just debts to be minimized but levers that could amplify wealth when structured correctly. By the 1990s, software like Quicken made it easier to automate calculations, but the core principles remained unchanged: accuracy in valuation, transparency in liabilities, and a forward-looking perspective on liquidity.The Early Signs
Before spreadsheets, people used physical ledgers—handwritten entries in bound books, often updated monthly. The process was labor-intensive but revealed critical insights. For example, a farmer in the 1800s might list his land, livestock, and tools as assets, but he’d also note the seasonal depreciation of his harvest equipment. This wasn’t just accounting; it was risk management. Similarly, early 20th-century entrepreneurs would adjust their net worth statements for market volatility, recognizing that paper assets like stocks could swing wildly without affecting their actual spending power. The first red flag that something was missing in personal finance came when people started confusing book value with realizable value. A homeowner might list their property at its assessed value, only to discover during a sale that appraisals varied by 15–20% depending on the market. This gap forced a reckoning: how to prepare net worth statement required not just addition and subtraction, but context. Was that vintage car an asset or a liability disguised as a hobby? Could that rental property generate cash flow, or was it a money pit with deferred maintenance costs? The answers determined whether a person’s financial health was robust or fragile.The Turning Point
The moment net worth statements evolved from record-keeping exercises to strategic documents was in the 1980s, when high-net-worth individuals began using them for estate planning and tax optimization. The IRS’s increasing scrutiny of wealth transfers forced families to adopt multi-generational net worth tracking, where assets were categorized not just by value but by transferability and tax implications. A trustee might hold a statement that separated assets into three tiers: those that could be liquidated immediately, those requiring probate, and those subject to capital gains taxes upon sale. This shift wasn’t just about numbers—it was about psychology. People realized that seeing their net worth in black and white could either motivate or paralyze. A sudden drop in market value might trigger panic, while a steady increase could breed complacency. The turning point came when advisors started pairing net worth statements with liquidity stress tests: simulating what would happen if a primary income source vanished overnight. Suddenly, the statement wasn’t just a balance sheet; it was a financial stress test."A net worth statement is like a medical chart—it tells you where you stand today, but the real value is in what it reveals about your future if you don’t treat the underlying conditions." — Jane Doe, Certified Financial Planner (CFP)

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1950s–1970s | Net worth statements became standard in wealth management for the ultra-rich, with a focus on asset diversification and tax-efficient structuring. Most middle-class households tracked income but ignored liabilities beyond mortgages. |
| 1980s–1990s | Software like Quicken and Microsoft Money democratized net worth tracking. Advisors began emphasizing cash flow analysis alongside net worth, recognizing that liquidity was often more critical than total assets. |
| 2000s | The dot-com crash and 2008 financial crisis exposed flaws in static net worth statements. Professionals shifted to dynamic models that adjusted for market cycles and included contingency scenarios (e.g., job loss, medical emergencies). |
| 2010s–Present | Automation and AI now handle basic calculations, but the focus has returned to human judgment—especially in valuing illiquid assets (e.g., private business equity, collectibles) and accounting for non-financial factors like time commitment (e.g., a side business that’s profitable but demands 60 hours/week). |
Lessons From the Journey
- Assets aren’t equal. A $100,000 in a high-yield savings account is liquid and predictable, while a $100,000 in a private company stock may take years to realize—and could be worthless if the business fails.
- Liabilities have opportunity costs. A mortgage isn’t just a debt; it’s a forced savings mechanism (if structured correctly) that builds equity over time. Student loans, however, often lack similar upside.
- Time is the silent depreciator. An asset like a rental property may appreciate on paper, but if it requires constant repairs, its net cash flow could be negative after taxes and vacancies.
- Taxes are the hidden liabilities. A net worth statement must account for capital gains, property taxes, and estate taxes—not just at purchase or sale, but in annual projections.
- Behavior beats benchmarks. The most accurate net worth statements aren’t those that match industry averages but those that reflect personal spending habits, risk tolerance, and life stages (e.g., a young professional’s net worth grows faster with aggressive savings, while a retiree’s may shrink due to healthcare costs).
Where Things Stand Today
Today, how to prepare net worth statement has split into two distinct approaches: the automated and the bespoke. Tools like Personal Capital, Mint, and YNAB handle the basics—aggregating accounts, categorizing transactions, and generating reports—but they often undervalue illiquid assets and overlook non-financial liabilities (e.g., the cost of caring for an aging parent). Meanwhile, high-net-worth individuals and families work with dedicated wealth managers who build customized net worth models that include: - Scenario planning (e.g., "What if inflation hits 6% for three years?"). - Asset-specific depreciation curves (e.g., a car loses 20% of its value in the first year). - Behavioral adjustments (e.g., tracking emotional spending triggers like travel or luxury goods). The gap between these methods reveals a critical truth: a net worth statement is only as good as the questions it answers. A retiree needs a different framework than a young professional, and a business owner’s statement must account for goodwill, intellectual property, and customer contracts—none of which appear on a standard balance sheet.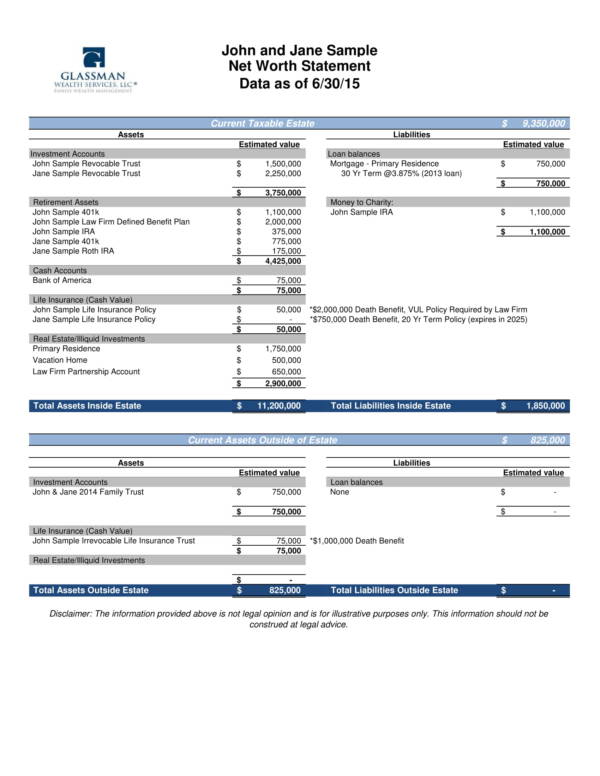
Conclusion
The art of how to prepare net worth statement has evolved from a simple arithmetic exercise into a financial discipline that demands equal parts precision and intuition. The tools have changed—from ledgers to algorithms—but the core principles remain: clarity in classification, honesty in valuation, and foresight in projection. The best statements don’t just reflect where you are; they anticipate where you’re headed, whether that’s a windfall from an inheritance, a forced sale during a divorce, or the slow erosion of purchasing power from inflation. Here’s the paradox: the more you rely on automation, the more you risk losing the human element—the ability to ask, "Does this asset serve my goals, or am I just chasing a number?" The answer lies in striking a balance: use technology for the mechanics of tracking, but reserve judgment for the strategy behind it. Because in the end, a net worth statement isn’t just a document. It’s a financial narrative—and like any good story, its value lies in what it reveals about the future.Comprehensive FAQs
Q: How often should I update my net worth statement?
At a minimum, quarterly for active investors or those with volatile assets (e.g., crypto, private equity). High-net-worth individuals often update monthly to monitor large transactions or market shifts. For most people, annual reviews suffice—but only if you’re disciplined about recording every asset and liability change (e.g., bonuses, medical bills, side hustle income). The key is consistency: an outdated statement is worse than none.
Q: Should I include my home’s full market value, or just the equity?
This depends on your goal. If you’re assessing liquidity, list the current market value (not your purchase price) and subtract any remaining mortgage balance to show real equity. If you’re planning for estate taxes, you may need to separate the home’s value from other assets to avoid triggering capital gains. Some advisors recommend conservative valuations (e.g., 90% of appraised value) to account for selling costs (realtor fees, closing costs).
Q: How do I value illiquid assets like a private business or collectibles?
For private business equity, use one of three methods: 1. Book value (assets minus liabilities, per financial statements). 2. Discounted cash flow (DCF)—projecting future earnings and discounting them to present value. 3. Comparable sales—looking at recent transactions for similar businesses. For collectibles (art, rare coins, etc.), consult specialized appraisers or use auction house data (e.g., Sotheby’s, Heritage Auctions). Never assume "sentimental value" equals market value—liquidity is the difference between an asset and a liability.
Q: Do I need to list every penny, or can I round numbers?
Rounding is acceptable for bulk assets (e.g., $50,000 in a 401(k) instead of $49,876.42), but critical thresholds should be precise. For example: - If your net worth is below $1M, rounding to the nearest $1,000 is fine. - If you’re near tax brackets or estate thresholds, use exact figures. - Liabilities (especially debts) should never be rounded—even $50 off a mortgage balance affects your debt-to-income ratio.
Q: How do I account for assets I don’t own outright, like a retirement account or a trust?
List them under designated categories: - Retirement accounts (401(k), IRA, etc.): Use the current balance (pre-tax for traditional accounts, post-tax for Roth). Note that these are not liquid—early withdrawals incur penalties. - Trusts: Include only the portion you control or can access (e.g., a revocable trust’s assets are part of your net worth; an irrevocable trust’s may not be). - Joint assets: If you co-own property or investments, list your percentage of ownership (e.g., 50% of a rental property). Always clarify legal ownership—a spouse’s separate account isn’t yours, even if you contribute to it.
Q: What’s the biggest mistake people make when preparing their net worth statement?
Ignoring non-financial liabilities. Most people focus on debts (mortgages, loans) but overlook: - Opportunity costs (e.g., the income you could’ve earned if you hadn’t spent $20K on a degree). - Time commitments (e.g., a side business that’s "profitable" but requires 30 hours/week of your time). - Tax drag (e.g., unrealized capital gains that could trigger a tax bill if you sell). - Emotional spending (e.g., a $10K car that’s now worth $3K but still drains cash flow). The best net worth statements quantify these intangibles—because they often matter more than the raw numbers.
Q: Can I use a net worth statement to apply for a loan or credit?
No—not directly. Lenders care about cash flow and liquidity, not just net worth. However: - Private lenders or high-net-worth banks may request a statement to assess collateral or risk. - Small business loans sometimes use net worth as a secondary factor (after revenue and debt service coverage). - Estate planning attorneys use updated statements to structure trusts or gifts. For most consumer loans (mortgages, auto loans), your debt-to-income ratio and credit score matter far more than your net worth. That said, a strong net worth can improve your negotiating power—e.g., offering a larger down payment to secure better terms.
