Where It All Began
The concept of tracking net worth isn’t new. It emerged from the same practical necessity that gave birth to double-entry bookkeeping: the need to know where you stand. In the late 18th century, merchants and landowners in Europe and America began documenting their assets and liabilities not just for taxes, but for survival. A farmer with a mortgage and a herd of cattle needed to know if a bad harvest would leave him solvent or bankrupt. The difference between a life of security and one of desperation often came down to a single ledger. By the early 20th century, as economies grew more complex, so did the tools for tracking wealth. The rise of personal banking in the 1920s made it easier to aggregate accounts, but the real shift came with the post-war boom. Middle-class households, now with savings accounts and retirement plans, needed a way to monitor their progress beyond monthly bank statements. The first consumer-friendly spreadsheets appeared in the 1980s, but even then, most people treated net worth tracking as a once-a-year exercise—something to do when filling out tax forms or applying for a loan.The Early Signs
The real turning point wasn’t technological; it was cultural. In the 1990s, as personal finance became a mainstream topic, tracking net worth stopped being a chore and started feeling like a form of empowerment. Books like Your Money or Your Life (1992) framed it as a tool for freedom, not just a balance sheet. The idea took hold slowly, but by the 2000s, the dot-com boom and bust made it impossible to ignore. People who had seen their 401(k)s evaporate overnight began demanding better visibility into their finances. The tools followed. Mint launched in 2006, offering automated net worth tracking for the first time. Suddenly, updating your numbers didn’t require digging through shoeboxes—it happened in the background. But even as technology made it easier, the core principle remained the same: knowing your net worth isn’t about vanity; it’s about preparedness.The Turning Point
The financial crisis of 2008 was the moment tracking net worth stopped being optional. Overnight, millions of Americans saw their home values plummet, their retirement accounts shrink, and their debt loads become unmanageable. Those who had been monitoring their net worth—even casually—were better positioned to weather the storm. They knew where to cut, where to negotiate, and when to walk away. Those who hadn’t were left scrambling. The shift wasn’t just practical; it was psychological. Before 2008, many people treated net worth like a report card they’d check once a year. Afterward, it became a daily habit for some—a way to stay ahead of the next crisis. Apps like Personal Capital and YNAB (You Need A Budget) emerged, catering to a new audience: people who wanted real-time visibility into their financial lives. The stigma faded. Tracking your net worth wasn’t just for the rich or the paranoid; it was for anyone who wanted to avoid surprises."The only way to predict the future is to track the past—and your net worth is the most honest record you’ll ever keep." — A former financial planner who helped clients navigate the 2008 crash

The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1980s–1990s | Spreadsheets became accessible to the average person. Early adopters used manual calculations to track assets and liabilities, often triggered by life events like buying a home or starting a business. |
| 2000s | Online banking and early fintech tools (e.g., Mint) automated net worth tracking. The dot-com crash and 2008 crisis proved its value, turning it from a niche practice into a mainstream necessity. |
| 2010s–Present | AI-driven tools and robo-advisors integrated net worth tracking with investment advice. The rise of gig economy incomes and side hustles made dynamic tracking essential for freelancers and entrepreneurs. |
Lessons From the Journey
- It’s not about the tools—it’s about consistency. A $5 spreadsheet is just as effective as a $500 app if you use it weekly.
- Net worth fluctuates, but the habit of tracking doesn’t have to. Even in volatile markets, updating your numbers keeps you grounded.
- Debt isn’t the enemy—misunderstood debt is. Tracking net worth forces you to distinguish between "good" debt (e.g., a mortgage) and "bad" debt (e.g., credit card balances).
- Emotions distort perception. A market dip can feel catastrophic until you see it in the context of your long-term net worth.
- Tracking isn’t just for the wealthy. A net worth of $10,000 is just as valid as one of $10 million—what matters is the trend.
- The real benefit isn’t the number itself, but the questions it forces you to ask. Why is my net worth stagnant? What would it take to grow it by 10% next year?
Where Things Stand Today
Today, keeping track of net worth is less about spreadsheets and more about integration. The best systems today don’t just show you a number; they explain it. Apps like Personal Capital and Wealthfront connect to your accounts, categorize your assets, and even suggest adjustments based on your goals. For those who prefer a hands-on approach, Google Sheets templates and Notion databases offer customizable solutions. The barrier to entry has never been lower. Yet the biggest challenge remains human behavior. Even with tools at their fingertips, many people still treat net worth tracking as a chore—something to do when they have time. But the most successful trackers treat it like a fitness habit: non-negotiable, even when life gets busy. The difference between a net worth that grows and one that stagnates often comes down to this: those who track consistently are the ones who make decisions based on data, not fear or impulse.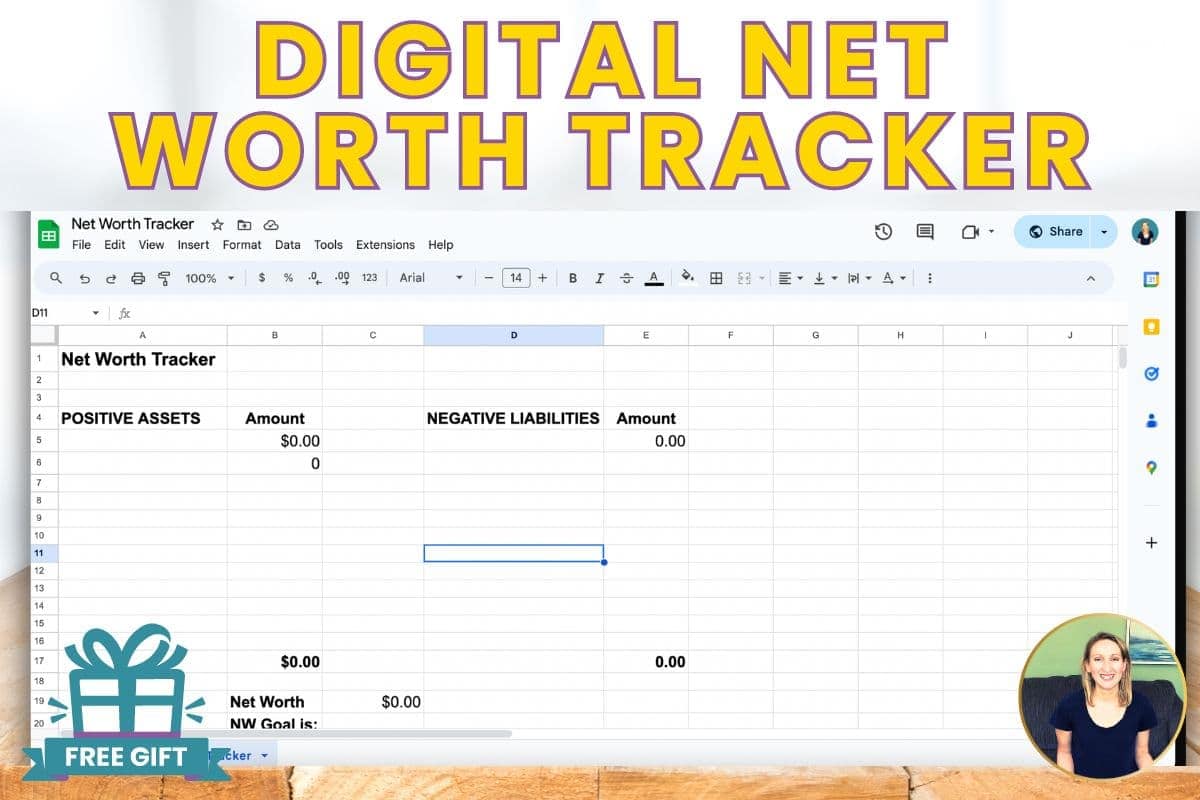
Conclusion
Tracking your net worth isn’t about becoming obsessed with numbers. It’s about gaining clarity in a system designed to keep you confused. The people who do it best aren’t the ones with the highest balances—they’re the ones who treat it as a mirror. It reflects not just their money, but their priorities, their discipline, and their readiness for whatever comes next. The good news? You don’t need to be an expert to start. A simple spreadsheet, a few minutes a month, and a commitment to honesty are all it takes. The rest is just showing up.Comprehensive FAQs
Q: How often should I update my net worth?
Most financial advisors recommend tracking net worth quarterly (every three months) to balance accuracy with effort. If your financial situation changes frequently (e.g., you’re a freelancer or investor), monthly updates may make more sense. The key is consistency—even rough estimates are better than nothing.
Q: Do I need fancy software to track my net worth?
No. A free Google Sheets template or even a notebook works if you’re disciplined. Apps like Mint or Personal Capital automate the process, but they’re optional. The goal is visibility, not complexity.
Q: What if my net worth is negative? Should I panic?
Not necessarily. A negative net worth is common for young adults, students, or those with high debt relative to assets. The critical question isn’t the number itself, but the trend. Are you improving? Are your liabilities (debt) decreasing faster than your assets (savings, investments) grow?
Q: How do I account for assets that aren’t liquid (e.g., a house, art, or a business)?
Estimate their fair market value based on recent appraisals, comparable sales, or professional evaluations. For example, a home’s value might be its current market price, while a business’s worth could require a valuation from an accountant. The goal is realism—overestimating can lead to false confidence.
Q: Should I include my pension or retirement accounts in my net worth?
Absolutely. Retirement accounts (401(k)s, IRAs, pensions) are part of your net worth because they represent future financial security. Just be clear whether you’re tracking current value (what it’s worth today) or future value (projected growth).
Q: What’s the biggest mistake people make when tracking net worth?
Ignoring opportunity costs. For example, treating a high-paying job as pure income without factoring in benefits like employer-matched retirement contributions. Or overlooking side hustles that could grow into significant assets. Net worth tracking should account for all potential wealth-building opportunities, not just cash and investments.
Q: Can tracking net worth actually improve my financial decisions?
Yes. Studies show that people who regularly track their net worth are more likely to:
- Save aggressively during windfalls (e.g., bonuses, tax refunds).
- Avoid lifestyle inflation when their income rises.
- Make rational decisions during market downturns (e.g., not panic-selling).
- Set and achieve specific financial goals (e.g., paying off debt, saving for a home).
Q: Is there a “right” net worth for my age?
No, but there are benchmarks based on averages. For example:
- Age 30: Net worth often ranges from $45,000 to $90,000 (varies by location and income).
- Age 40: $120,000 to $250,000 (assuming steady saving/investing).
- Age 50: $250,000 to $500,000+ (including home equity and retirement accounts).
