Breaking Down the Numbers
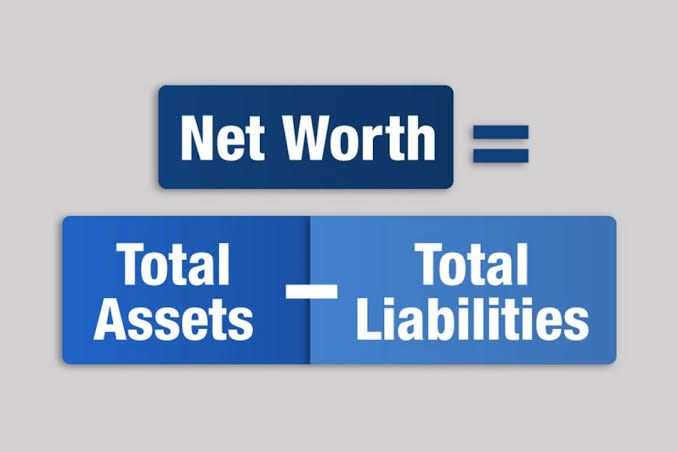
The net worth to total liabilities ratio operates on a simple premise: divide total assets minus total liabilities (net worth) by total liabilities. The result is a ratio that answers one critical question—how much cushion exists between what you own and what you owe. But the real value emerges when this ratio is stress-tested. For instance, a ratio of 4:1 might seem healthy until you factor in a 20% market correction on illiquid assets like real estate or private equity. Suddenly, the ratio could drop to 2.5:1, forcing a fire sale of assets or additional borrowing to cover gaps. What distinguishes this metric from others is its focus on structural rather than cyclical risk. A high debt-to-equity ratio in corporate finance often signals growth potential, but in personal or family wealth contexts, it can indicate overreach. The ratio doesn’t care about the source of the liabilities—whether it’s a mortgage, student loans, or a leveraged buyout of a business. It only cares about the balance. This is why ultra-high-net-worth families often maintain ratios below 1.5:1 not out of frugality, but as a buffer against black swan events, such as legal disputes or sudden shifts in tax policy.The Verified Baseline
Publicly available data on net worth to total liabilities ratios is scarce, particularly for individuals. Most disclosures come from corporate filings, where the equivalent metric—equity to total debt—is standardized. For example, a publicly traded company might report a ratio of 1.8:1, meaning shareholders’ equity covers 1.8 times its total debt. This is verifiable through SEC filings or annual reports. For private entities, however, the picture blurs. Even when wealth managers or family offices publish aggregate statistics, they rarely break down ratios by individual or household. What can be confirmed is the thresholds that institutions and regulators use internally. Banks, for instance, often apply a 3:1 or higher ratio as a baseline for personal lending, though this varies by jurisdiction. Credit bureaus may not disclose exact ratios, but they factor equivalent metrics into credit scores. For high-net-worth individuals, ratios below 1:1 can trigger scrutiny from lenders, even if the individual’s cash flow is robust. The key takeaway from verified data is that the ratio is less about absolutes and more about relative safety margins—what’s acceptable in one economic environment may not be in another.What the Estimates Suggest
Industry estimates suggest that the optimal net worth to total liabilities ratio varies by life stage and risk profile. For young professionals, ratios between 1.5:1 and 2.5:1 are common, reflecting higher debt levels (student loans, mortgages) balanced by liquid assets like retirement accounts. As individuals approach retirement, the ratio tends to rise, with figures around 3:1 or higher becoming more typical, as liabilities stabilize and assets appreciate. However, these are averages—the ratio’s true meaning emerges when paired with asset liquidity. A 4:1 ratio with 80% of assets tied to illiquid real estate carries different risk than one with diversified, tradable securities. Speculative discussions often center on outliers. For instance, some tech entrepreneurs reportedly maintain ratios below 1:1 during hyper-growth phases, relying on future equity upside to offset debt. Others, particularly in industries like finance or private equity, may deliberately keep ratios tight to exploit arbitrage opportunities. The danger here is that interpret net worth to total liabilities ratio in isolation can be misleading. Without context—such as the expected return on illiquid assets or the duration of the debt—even a seemingly strong ratio may mask hidden vulnerabilities.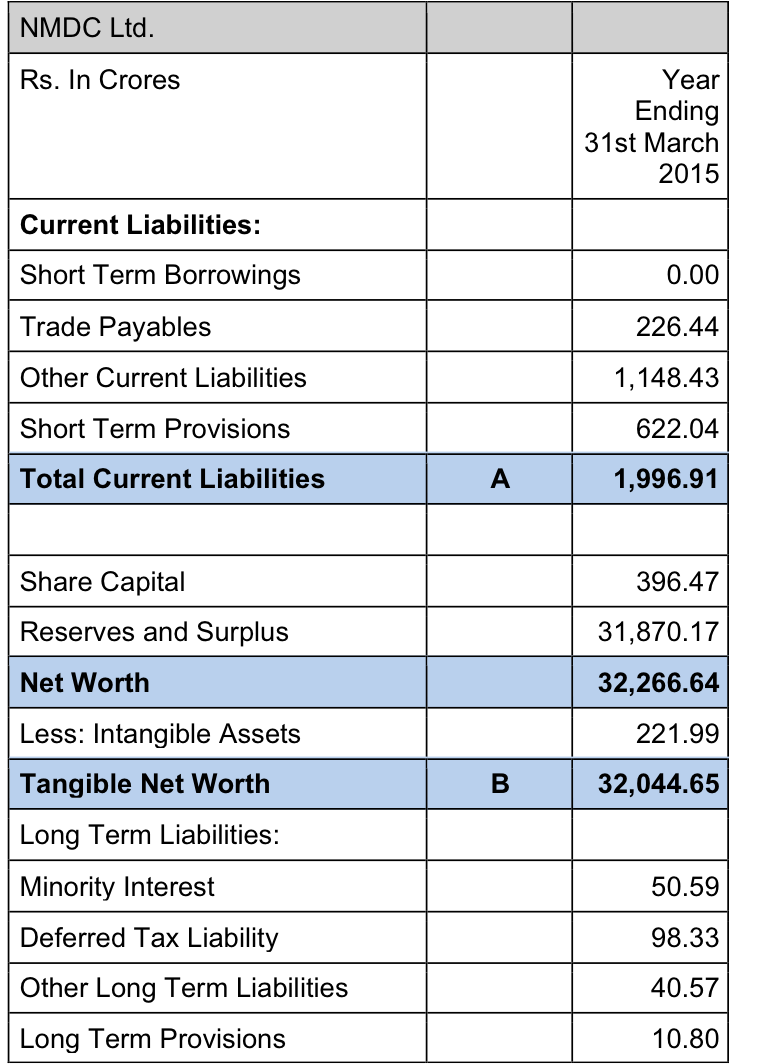
Case Study: A Closer Look
Consider the financial strategy of a mid-career executive who, at age 45, holds a net worth estimated at £5 million, with total liabilities (including a primary residence mortgage and private school tuition for children) around £2 million. On the surface, this yields a ratio of 2.5:1—a figure that would pass muster with most lenders. However, a deeper analysis reveals nuances. The executive’s primary asset, a £3 million London property, is mortgaged at £1.5 million with a 20-year term. If property values stagnate or interest rates rise, the ratio could deteriorate rapidly, forcing a sale or refinancing at an inopportune time. The executive’s strategy hinges on two factors: asset liquidity and liability duration. The private school tuition, while a fixed obligation, is short-term relative to the mortgage. The property, however, is both illiquid and long-term. This mismatch creates a structural risk. A 10% drop in property values could push the ratio below 2:1, even if the executive’s salary and investment income remain steady. The ratio alone doesn’t capture this exposure—it’s the interplay between the ratio and the timing of liabilities that matters."A ratio is only as strong as the weakest link in your balance sheet. You can have a 3:1 ratio today, but if your largest liability is a 30-year mortgage on a depreciating asset, that ‘strength’ is an illusion." — Wealth structuring advisor, London-based family office
| Factor | Estimated Impact on Ratio |
|---|---|
| Property market correction (10% decline) | Ratio drops from 2.5:1 to ~1.9:1; forces reassessment of refinancing options |
| Fixed-rate mortgage reset to variable (2% rate hike) | Monthly outflows increase by ~£15k/year; ratio pressure intensifies if income stagnates |
| Early exit from illiquid private equity stake (forced sale at 20% discount) | Net worth declines by ~£800k; ratio falls to 1.8:1, triggering lender reviews |
What This Means Going Forward
The net worth to total liabilities ratio is evolving in response to two macro trends: the rise of alternative assets and the erosion of traditional liquidity buffers. As more wealth is tied to private equity, crypto, or art—assets that don’t trade daily—the ratio becomes a lagging indicator. By the time the ratio signals distress, the underlying assets may already be in freefall. This is why forward-looking families and institutions are supplementing the ratio with liquidity stress tests, simulating scenarios where 30–50% of assets must be sold within 6–12 months. Regulatory and tax changes are also reshaping how the ratio is interpreted. For example, the UK’s recent reforms to non-domiciled tax status have led some expatriates to restructure liabilities (e.g., offshore trusts) to improve their ratios artificially. While this may reduce taxable exposure, it can distort the true financial health picture. The ratio, in this context, becomes a red herring unless paired with a tax-equivalent adjustment. Moving forward, the most resilient approaches will treat the ratio not as a standalone metric, but as one node in a broader financial graph—connected to cash flow, insurance coverage, and contingency planning.
Conclusion
The net worth to total liabilities ratio is deceptively simple. Its power lies not in the calculation itself, but in what it forces you to confront: the asymmetry between what you control (assets) and what controls you (liabilities). A high ratio doesn’t guarantee safety, nor does a low one guarantee ruin. The ratio’s true value is in the questions it provokes—about leverage, liquidity, and the unspoken assumptions behind every balance sheet. For individuals, it’s a mirror; for institutions, it’s a stress test. Ignore it at your peril, but rely on it blindly and you risk misreading the most critical financial story of all: your own. The ratio’s future may lie in its customization. As AI and alternative data sources refine financial modeling, we may see ratios tailored to specific life stages or risk appetites—perhaps a "growth ratio" for entrepreneurs versus a "conservation ratio" for retirees. But one thing remains constant: the ratio’s core function. It doesn’t tell you whether you’re rich or poor. It tells you whether you’re solvent—or one market cycle away from being exposed.Comprehensive FAQs
Q: Is there a universally "good" net worth to total liabilities ratio?
A: No. Ratios above 3:1 are often considered safe for retirees, while ratios between 1.5:1 and 2.5:1 may be typical for working-age professionals. However, the context matters more than the number. A 2:1 ratio with all assets in cash is far stronger than a 4:1 ratio with 90% of assets tied to a single illiquid venture. The ratio should align with your risk tolerance and liquidity needs.
Q: How often should I calculate this ratio?
A: At minimum, annually—especially if your financial situation is stable. For those with volatile assets (e.g., startups, crypto, or real estate), quarterly checks are prudent. The ratio can shift rapidly with market movements, debt repayments, or new liabilities (e.g., a business loan or inheritance). Automating the calculation via accounting software can help track trends over time.
Q: Can a high ratio hide financial problems?
A: Absolutely. A ratio of 5:1 might look pristine, but if your largest asset is a business with declining revenue or a property in a saturated market, the ratio masks structural illiquidity. Conversely, a ratio of 1.2:1 could reflect deliberate leverage for high-return investments. Always pair the ratio with cash flow analysis and asset quality assessments.
Q: Does this ratio factor in future income or expected returns?
A: No. The ratio is a static snapshot of current assets and liabilities. It doesn’t account for future salary growth, investment returns, or new debt. For a dynamic view, combine it with projections—such as a 5-year cash flow forecast—or use it alongside metrics like the sustainable withdrawal rate for retirees.
Q: How do taxes affect the interpretation of this ratio?
A: Taxes can distort the ratio in two ways. First, tax liabilities (e.g., capital gains tax, inheritance tax) act as hidden liabilities that aren’t always captured in standard balance sheets. Second, tax-efficient structuring (e.g., trusts, offshore accounts) can artificially inflate net worth or reduce reported liabilities, skewing the ratio. Always adjust for tax-equivalent net worth if comparing ratios across jurisdictions or structures.
Q: What’s the difference between this ratio and the debt-to-income ratio?
A: The debt-to-income ratio focuses on monthly obligations versus monthly income, making it useful for lenders assessing repayment ability. The net worth to total liabilities ratio, however, looks at total solvency—the cushion between all assets and all debts. The former answers, "Can you service your debt?" The latter answers, "What happens if you can’t?" Both are critical, but they serve different purposes.
Q: Are there industries where a low ratio is normal?
A: Yes. In high-leverage industries like private equity, hedge funds, or real estate development, ratios below 1:1 are common due to the use of debt to amplify returns. Similarly, venture-backed startups often operate with negative net worth (liabilities exceed assets) as they scale. The key difference is that these entities rely on future cash flows or exits to cover liabilities, whereas individuals or conservative investors typically avoid such structures.
