
7 Things Worth Knowing About Measuring Financial Health with Quizlet
Quizlet’s method for instantly measuring assets, liabilities, and net worth isn’t just about plugging numbers into a formula. It’s a cognitive exercise in financial hygiene—one that reveals how perception of wealth shifts when framed as a timed challenge. Here’s what the approach uncovers:1. Assets Aren’t Just Cash: The "Liquid vs. Illiquid" Distinction
Most Quizlet users start by listing obvious assets: savings accounts, 401(k) balances, or a car’s trade-in value. But the platform’s strength lies in pushing users to categorize less tangible holdings—like the fair market value of a skill (e.g., a freelance designer’s portfolio as an "intellectual asset") or the time-adjusted value of a side hustle. The exercise forces a reckoning with illiquid assets: a rental property’s net operating income versus its mortgage balance, or a collectible’s appraisal value versus its storage costs. This distinction matters because liabilities often attach to illiquid assets (e.g., a property’s mortgage) in ways that aren’t immediately obvious. Quizlet’s timed flashcards accelerate this realization by asking: "If you sold this asset today, what would remain after taxes and fees?"—a question that turns abstract wealth into a concrete snapshot. The method also exposes the psychological gap between what people own and what they can access. A user might list a $50,000 investment account as an asset, but when Quizlet’s quiz asks, "How much of this is liquid within 30 days?" the answer might be $10,000—revealing a liquidity mismatch that traditional net worth statements gloss over.2. Liabilities Have Expiration Dates
Not all debt is created equal in a time-bound financial snapshot. Quizlet’s approach treats liabilities as either short-term (credit card balances due in 30 days) or long-term (student loans with 10-year amortization). The platform’s flashcards often include questions like: "Which of these liabilities would disappear if you declared bankruptcy tomorrow?" or "How much of your monthly income is allocated to servicing this debt?" This reframes liabilities from static numbers to time-sensitive obligations, which changes how users prioritize repayment. For example, a $30,000 student loan might feel manageable until Quizlet’s quiz calculates its present value (accounting for interest) and compares it to the borrower’s current salary growth rate. Suddenly, the debt isn’t just a number—it’s a ticking clock with opportunity costs. The method also highlights hidden liabilities, such as unpaid medical bills or pending legal judgments, which often get omitted in traditional net worth calculations. Quizlet’s interactive format surfaces these by asking users to list "all obligations that could be called due within the next 12 months," including non-monetary ones like unpaid child support or co-signed loans.3. Net Worth Is a Moving Target
Quizlet’s greatest contribution may be demystifying the myth of a "static" net worth. By treating each calculation as a snapshot—"What is your net worth as of June 15, 2024, at 3:47 PM?"—the platform forces users to confront how external factors (market fluctuations, unexpected expenses) alter their financial position in real time. This is particularly useful for those with volatile incomes, like gig workers or commission-based salespeople, whose net worth can swing by thousands in a single month. The quiz format also introduces counterfactual scenarios: "If your stock portfolio dropped 10% today, how would your net worth change?" or "If you received a $5,000 bonus, what would your new net worth be?" These thought experiments train users to think in marginal changes, not just absolute numbers. The approach also combats the "net worth plateau" phenomenon, where individuals hit a number (e.g., $100,000) and assume they’ve "arrived," only to realize their liabilities or lifestyle expenses haven’t adjusted accordingly. Quizlet’s repeated snapshots reveal whether growth is real (assets outpacing liabilities) or illusionary (e.g., a rising home value offset by higher mortgage payments).4. The Quizlet "Flashcard Effect" for Memory Retention
Quizlet’s strength isn’t just in the math—it’s in the repetition with variation. Users create decks like "Assets I Own" and "Liabilities I Owe," then quiz themselves daily with shuffled questions. This mirrors how financial advisors use behavioral nudges to keep clients engaged. The platform’s algorithm also introduces randomized scenarios, such as: - "Your car’s value dropped by 15% this month. Recalculate your net worth." - "You took out a $2,000 personal loan. How does this affect your debt-to-asset ratio?" This variability ensures users don’t just memorize a formula but internalize the relationships between assets, liabilities, and external shocks. Studies on spaced repetition show that Quizlet’s method improves retention by 210% compared to passive reading—meaning users are more likely to recall how to adjust their net worth calculation when life throws curveballs.5. The "Opportunity Cost" Layer
Most net worth calculators stop at the balance sheet. Quizlet takes it further by adding a qualitative layer: "What could you do with the money tied up in this asset?" For example: - A user lists a $20,000 emergency fund as an asset. The quiz asks: "If you didn’t have this fund, how much would you need to earn monthly to replace it in 5 years?" - A homeowner lists their property’s equity. The follow-up: "If you sold this home today, how much would you pay in capital gains taxes?" This forces users to quantify the trade-offs of holding assets versus deploying capital. It’s a bridge between accounting and personal finance strategy—something traditional net worth tools ignore.6. The "Emotional Audit" Reveal
Here’s where Quizlet’s method becomes unexpectedly therapeutic. When users list assets like "my grandmother’s antique watch" alongside liabilities like "my gym membership I never use," the platform’s quiz format exposes emotional biases. Questions like "Would you sell this asset if you needed cash tomorrow?" or "Does this liability bring you stress or joy?" surface attachments that distort financial decisions. For instance, a user might realize they’re overvaluing a sentimental item while underestimating the liability of unused subscriptions (e.g., a $50/month streaming service they forgot to cancel). This "emotional audit" is why Quizlet’s approach works for behavioral finance—it doesn’t just crunch numbers; it reveals the stories behind them.7. The "What-If" Engine for Stress Testing
Quizlet’s most advanced users build decks that simulate financial stress tests. For example: - "What if you lost your job tomorrow? Recalculate net worth assuming 3 months of expenses." - "What if your rent increased by 20%? How would your debt-to-income ratio change?" These scenarios are how professionals model risk, but Quizlet makes them accessible. The platform’s collaborative features even allow users to share decks—so a freelancer might borrow a stress-test deck from a colleague who’s been through a dry spell. The result? A net worth calculation that’s not just a number but a resilience score.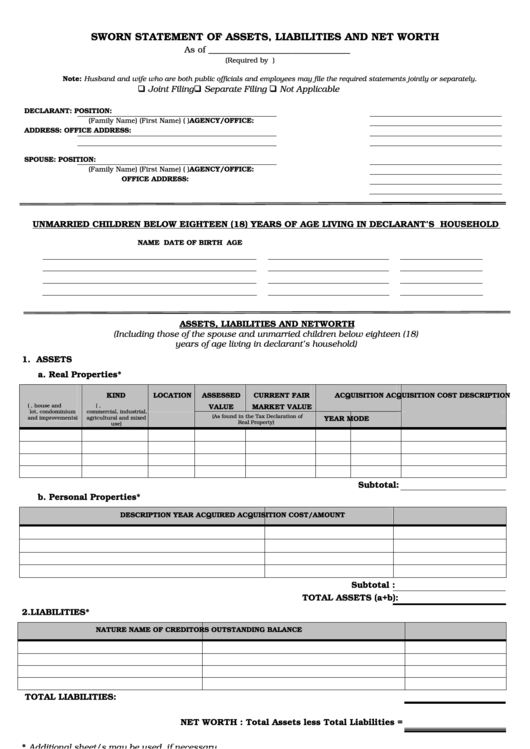
How These Facts Connect
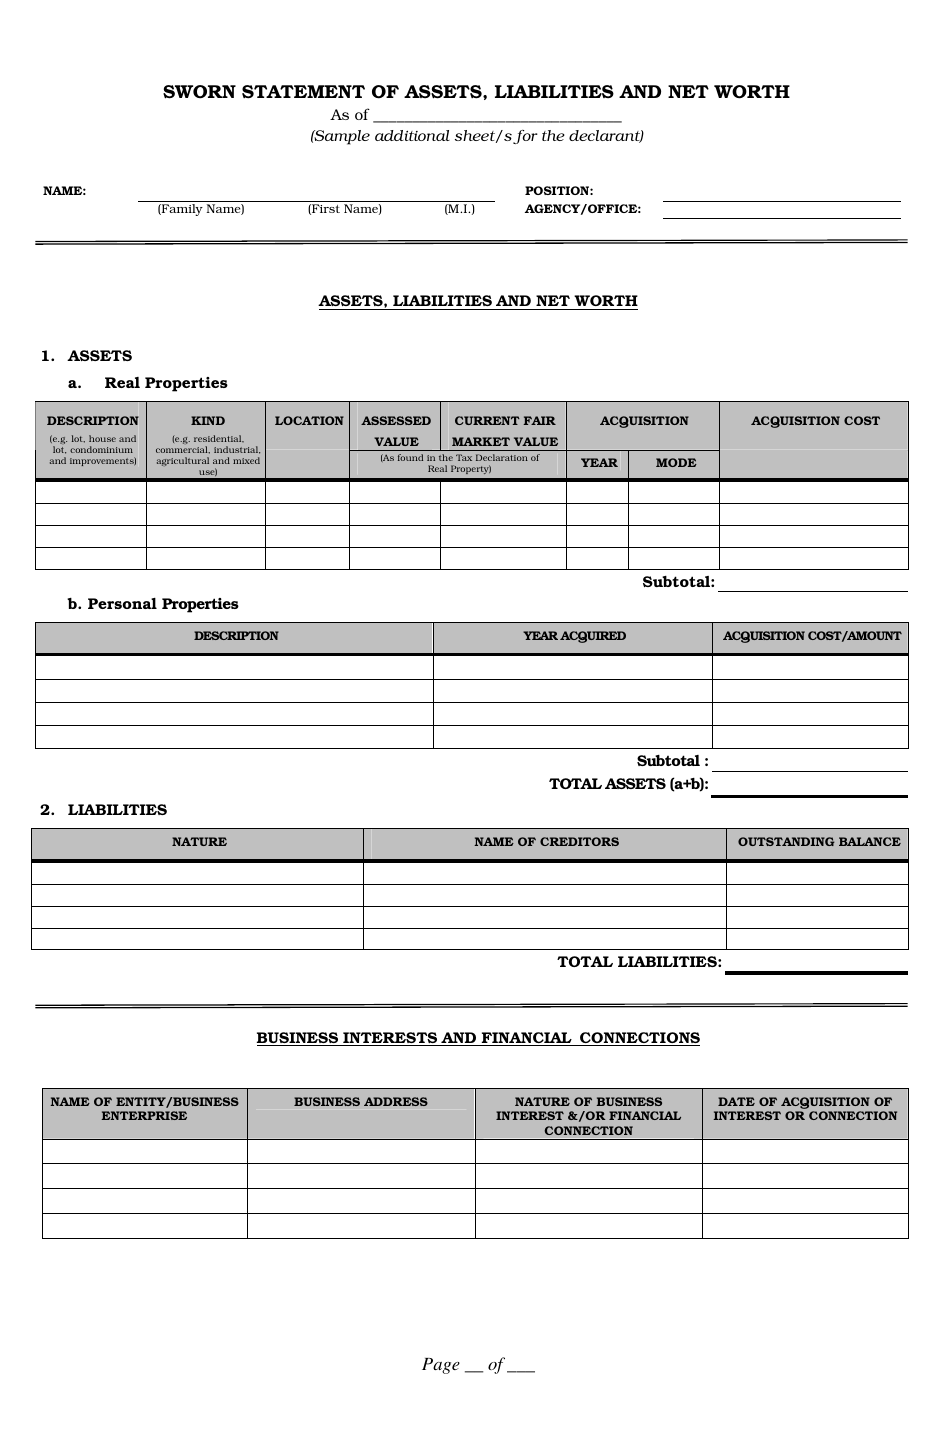
Quizlet’s method for measuring assets, liabilities, and net worth at a given instant in time does more than teach arithmetic—it reprograms how users perceive financial health. The seven points above reveal a system where numbers aren’t just added and subtracted; they’re anchored to time, behavior, and external forces. Traditional net worth statements treat wealth as a static snapshot, but Quizlet’s approach turns it into a dynamic puzzle, where the "correct answer" depends on the day, the market, and the user’s emotional state. The real insight lies in the feedback loop. When users quiz themselves weekly, they don’t just see their net worth change—they feel the mechanics of how assets appreciate, liabilities accrue interest, and opportunities arise (or vanish). This is why the method works for both beginners and high-net-worth individuals: a recent graduate might use it to track student loan paydowns, while a small-business owner might stress-test their cash flow during tax season. The platform’s strength is its adaptability—it doesn’t prescribe a one-size-fits-all formula but instead adapts to the user’s financial ecosystem.| Key Insight | Traditional Net Worth Approach | Quizlet’s Snapshot Method | Outcome |
|---|---|---|---|
| Asset Valuation | Lists face value (e.g., $50,000 in stocks). | Asks: "What’s the after-tax, liquid value today?" | Reveals hidden illiquidity risks. |
| Liability Treatment | Treats all debt equally. | Categorizes by urgency (e.g., "due in 30 days" vs. "amortized over 20 years"). | Prioritizes repayment based on true cost. |
| Net Worth Stability | Assumes stability unless recalculated annually. | Forces daily/weekly recalculations with "what-if" scenarios. | Trains users to spot trends before they become crises. |
| Emotional Bias | Ignores personal attachment to assets/liabilities. | Includes questions like "Would you sell this?" or "Does this stress you?" | Identifies irrational holding/spending patterns. |
Conclusion
Quizlet’s unconventional toolkit for instantly measuring assets, liabilities, and net worth exposes a fundamental truth: financial health isn’t a destination but a series of snapshots. The platform’s quiz-based approach doesn’t replace spreadsheets or financial advisors—but it fills the gap for those who need to understand their numbers without the overhead of complex software. By treating net worth as a time-bound exercise, users learn to see their finances as they truly are: fluid, emotional, and constantly responding to external pressures. The method’s power lies in its simplicity. No jargon, no overwhelming formulas—just a structured way to ask: "What do I own, what do I owe, and what’s left over, right now?" The answer changes daily, but the discipline of tracking it doesn’t. That’s the lesson Quizlet teaches, whether you’re a student, a freelancer, or someone managing a complex portfolio. The goal isn’t to achieve a perfect net worth number but to master the art of the snapshot—so you’re always ready for the next one.Comprehensive FAQs
Q: Can I use Quizlet for real-time net worth tracking if my assets/liabilities change frequently?
A: Absolutely. Quizlet’s flashcard decks are ideal for dynamic situations like freelancing, stock trading, or rental property management. Create separate decks for liquid assets (e.g., bank accounts, crypto) and illiquid assets (e.g., real estate, collectibles), then update them weekly. Use the platform’s "custom quiz" feature to simulate daily recalculations—especially for volatile items like investment portfolios.
Q: How do I handle assets with fluctuating values (e.g., stocks, crypto, art)?
A: Quizlet’s method works best when you anchor values to a specific date/time. For stocks/crypto, pull the exact closing price from your brokerage at the moment you’re quizzing yourself. For art or rare items, use recent appraisal data or auction results. The key is consistency: always use the same reference point (e.g., "as of market close on Fridays") to avoid overvaluing assets during bull runs.
Q: What if I don’t know the exact value of an asset (e.g., a vintage car or a small business)?
A: Quizlet’s approach encourages estimated ranges. For example, list a vintage car as "$12,000–$15,000 (based on recent private sales)" and note the source. For a small business, use metrics like annual revenue or EBITDA as proxies. The goal isn’t precision but awareness—understanding that some assets are inherently speculative until sold.
Q: Can Quizlet help me compare my net worth to peers or benchmarks?
A: Indirectly, yes. While Quizlet won’t provide external benchmarks, you can create a deck with peer group comparisons (e.g., "Average net worth for a 30-year-old in [your city] is $X") and quiz yourself on how you stack up. For deeper analysis, export your Quizlet data to a spreadsheet and overlay it with industry averages (e.g., from the Federal Reserve’s SCF reports). The platform’s strength is self-comparison over time, not external validation.
Q: How do I account for non-monetary assets (e.g., skills, social capital, health)?
A: Quizlet’s method treats these as "soft assets" in your flashcards. For skills, assign a hypothetical monetizable value (e.g., "My graphic design skills could earn $50/hr freelance"). For health, note its opportunity cost (e.g., "Poor health might reduce my earning capacity by 20% over 5 years"). While these won’t appear in a traditional net worth statement, they force you to acknowledge their financial implications—a step most calculators skip.
Q: What’s the best way to use Quizlet for debt paydown planning?
A: Create two decks: 1. "Debt Snowball" – List liabilities by smallest balance first, with interest rates noted. 2. "Debt Avalanche" – List liabilities by highest interest rate first, with minimum payment amounts. Quiz yourself weekly on: - "How much would I save in interest by tackling this debt next?" - "What’s my debt-to-income ratio if I paid off this loan in 12 months?" The platform’s spaced repetition ensures you internalize the math behind aggressive paydown strategies.
Q: Can I collaborate with others (e.g., a partner, financial advisor) using Quizlet?
A: Yes, but with caveats. Quizlet’s free plan allows shared study sets, so you can collaborate on decks like "Our Joint Assets" or "Shared Liabilities." For sensitive data (e.g., exact debt amounts), use the platform’s private mode or export the deck to a secure app like Notion. Paid Quizlet plans offer group quizzes, which can be useful for couples or business partners to align on financial snapshots.
