
5 Things Worth Knowing About Finding House Net Worth
The process of determining a home’s net worth isn’t linear. It requires layering data sources, adjusting for intangibles, and accounting for time-sensitive variables. Here’s what separates a rough estimate from a precise financial snapshot.1. Net worth ≠ market value
Market value reflects what a buyer might pay; net worth reflects what the owner actually retains after all obligations. For example, a $1.2 million waterfront home in Miami might have a net worth of $900,000 after deducting a $250,000 mortgage, $30,000 in back taxes, and $20,000 for structural repairs. The confusion arises because most valuation tools—like Zillow’s Zestimate or Redfin’s estimates—ignore liabilities. Even appraisers often exclude deferred maintenance costs, which can inflate perceived worth by 10–15%. To find house net worth, start by subtracting: - Outstanding mortgage balances (including private loans) - Property taxes owed (current year + escrow) - HOA fees or special assessments - Pending legal judgments or liens2. Location data isn’t just about zip codes
Two identical homes in the same city can have wildly different net worths based on micro-trends. A property in a gentrifying neighborhood might see its net worth surge by 30% in three years, while a comparable home in a stagnant suburb could depreciate. Tools like CoreLogic’s Home Price Index or local MLS data provide benchmarks, but they lack granularity. For instance, a home in Brooklyn’s Bushwick might have a higher net worth due to rising rents, while a similar property in nearby Ridgewood—despite proximity—could lag because of school district boundaries or planned infrastructure projects. To find house net worth accurately, overlay: - Crime rate trends (check NeighborhoodScout) - School district performance (GreatSchools.org ratings) - Future development plans (city council meeting minutes) - Flood zone or wildfire risk (FEMA maps)3. Hidden assets inflate—or deflate—worth
Not all value is visible. A home’s net worth can include: - Built-in equity: Custom renovations (e.g., a chef’s kitchen) may add $50,000 to resale value but cost $80,000 upfront—reducing net worth. - Rental potential: A duplex’s net worth rises if one unit generates $2,000/month in profit after expenses. - Energy efficiency: Solar panels or smart thermostats can boost net worth by 5–10% in eco-conscious markets. Conversely, hidden liabilities erode worth: - Asbestos or lead paint remediation costs (common in pre-1980 homes) - Foundation cracks or mold (often missed in inspections) - Blockchain land records (in states like Georgia or Arizona) reveal ownership disputes that traditional titles obscure.4. Time horizon changes everything
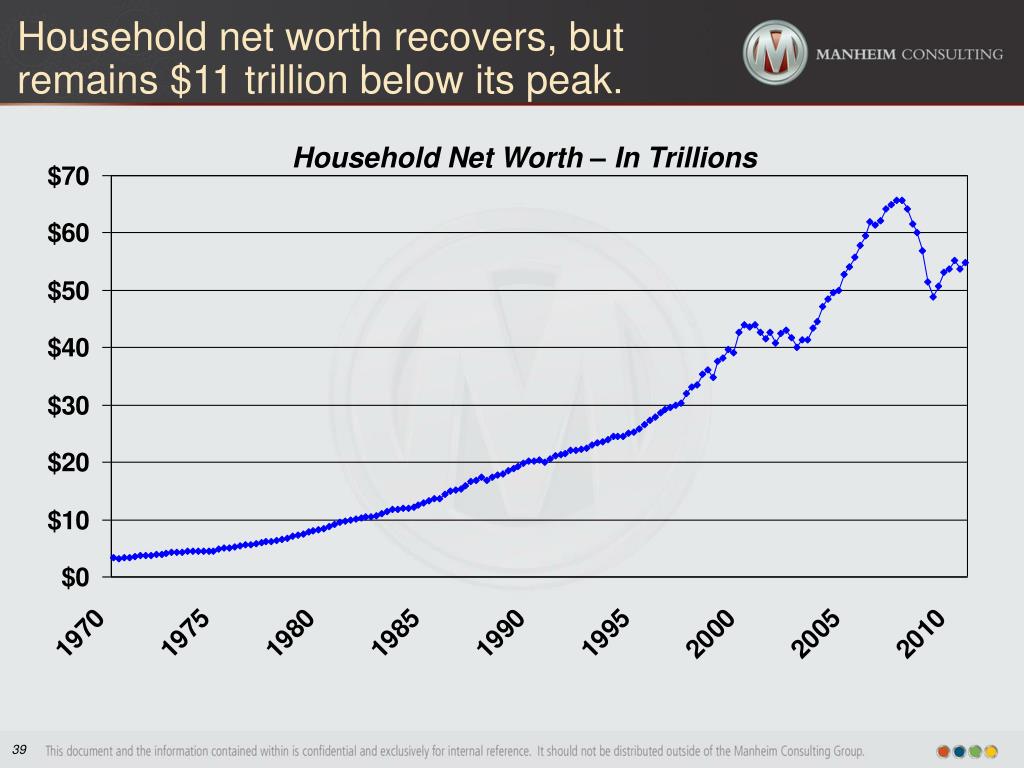
A home’s net worth isn’t static. Holding a property for five years vs. flipping it in six months alters its financial profile. For example: - Short-term: A fixer-upper’s net worth drops if renovation costs exceed post-repair appraisals. - Long-term: Capital gains taxes (up to 20% for high earners) eat into profits, but the primary residence exemption (up to $500,000 for couples) can preserve net worth. - Market cycles: Buying at a peak reduces net worth faster than buying at a trough. The 2008 crash saw homeowners’ net worth plummet by 30% in some regions.5. Professional adjustments matter
Even with data, human judgment is critical. A certified appraiser or real estate analyst can spot: - Comparable sales adjustments: A "comps" home with a pool might not be comparable if your property lacks one. - Tax abatements: Some cities offer property tax breaks for historic renovations, boosting net worth. - Off-market opportunities: Inherited properties or probate sales often sell below net worth due to urgency."The biggest mistake people make is treating net worth like a static number. It’s a living calculation—affected by interest rates, local politics, and even the seller’s emotional attachment to the property." — Sarah Chen, Managing Partner at Urban Valuation Group
How These Facts Connect
The interplay between market value, liabilities, and external factors creates a dynamic equation for net worth. For instance, a home in a city with rising property taxes (like San Francisco) may see its net worth stagnate even as prices climb, while a comparable home in a state with no income tax (like Texas) could retain more equity. Similarly, a homeowner’s credit score affects mortgage rates, indirectly influencing net worth: a 0.5% lower rate on a $700,000 loan saves $50,000 over five years, preserving more net worth. The table below contrasts three key variables in finding house net worth:| Factor | Short-Term Impact | Long-Term Impact |
|---|---|---|
| Market Value | Fluctuates with listings, seasonality, and buyer demand. | Appreciation (or depreciation) compounds over decades. |
| Liabilities | Immediate deductions (mortgages, taxes). | Debt paydown increases net worth over time. |
| External Forces | Crime spikes or school closures can drop value quickly. | Infrastructure projects (e.g., new transit) boost worth gradually. |
Conclusion
Finding house net worth isn’t about pulling a number from an app—it’s about assembling a puzzle with missing pieces. The most precise assessments combine hard data (deeds, tax records) with soft intelligence (neighborhood sentiment, political climate). For buyers, this knowledge prevents overpaying; for sellers, it ensures fair pricing; for heirs, it clarifies whether an inheritance is an asset or a burden. The tools exist—public records, AI-driven analytics, and human expertise—but the skill lies in knowing which levers to pull. The next step? Audit your own property’s net worth. Start with your mortgage statement, then layer in local market trends. If the gap between perceived and actual worth surprises you, you’re already ahead of most homeowners.Comprehensive FAQs
Q: How often should I reassess my home’s net worth?
A: At minimum, annually if you’re tracking for investment purposes, or before major life events (divorce, inheritance, downsizing). Market shifts, tax law changes, or personal financial shifts (e.g., paying off a mortgage) can alter net worth significantly. Use tools like Redfin’s Home Value Estimator for a baseline, then cross-check with a local appraiser for precision.
Q: Can I find house net worth without an appraisal?
A: Yes, but with limitations. DIY methods include: - Subtracting your mortgage balance from Zillow’s estimate (though this ignores taxes/liens). - Using county assessor records for tax-assessed value (often lower than market value). - Calculating rental income potential (if applicable) via platforms like Rentometer. For accuracy, combine these with three comparable sales from the past six months. However, for high-value or complex properties, an appraisal is worth the $300–$600 cost.
Q: Do inherited properties have different net worth rules?
A: Absolutely. Inherited homes may face: - Probate delays (adding holding costs). - Step-up in basis (inheritors pay taxes on the home’s current value, not what the previous owner paid). - Hidden debts (e.g., unpaid HOA fees or back taxes). Always verify the deed and obtain a clear title report before assuming net worth. Consult an estate attorney to factor in inheritance taxes (which vary by state).
Q: How do renovations affect net worth?
A: Not all upgrades pay off. High-ROI renovations (kitchens, bathrooms, energy-efficient windows) typically add 60–80% of their cost to net worth. Low-impact changes (e.g., paint, flooring) may recoup only 30–50%. Avoid over-customizing—unique features (like a home theater) appeal to niche buyers but reduce broad-market net worth. Track pre- and post-renovation appraisals to measure impact.
Q: What’s the biggest mistake people make when estimating net worth?
A: Ignoring opportunity cost. A home might have high net worth on paper, but if it ties up liquidity for 10 years, the real net worth includes the lost potential of investing that capital elsewhere. For example, a $1M home with $500K equity could’ve grown to $1.5M in the stock market over a decade. Always compare property net worth to alternative investment returns (e.g., REITs, bonds).
Q: How do I find net worth for a rental property?
A: Rental net worth requires cash-flow analysis. Start with: 1. Gross rental income (annualized). 2. Subtract: Mortgage payments, property taxes, insurance, maintenance (1–2% of value/year), vacancies (5% buffer), and management fees (if applicable). 3. Add: Tax benefits (depreciation, deductions). 4. Compare to market value: If the property’s net operating income (NOI) is strong but the building is outdated, its net worth may be lower than a newer comp. Tools like BiggerPockets’ Rental Calculator automate this, but a property management audit adds precision.
Q: Can I use AI tools to find house net worth?
A: AI tools like HouseCanary, PropStream, or Reonomy provide predictive analytics (e.g., future appreciation models), but they’re not substitutes for human oversight. AI excels at: - Identifying undervalued properties in off-market data. - Projecting rental demand in your area. - Flagging zoning changes that could boost net worth. For final calculations, cross-reference AI outputs with a local appraiser—especially in niche markets (e.g., luxury homes, farmland).
