The Complete Overview of Calculating Debt Ratio from Financial Position
The debt ratio derived from net worth and liabilities isn’t just a financial metric—it’s a narrative of risk exposure. At its core, it answers a fundamental question: How much of your financial security is tied to obligations rather than owned assets? This ratio cuts through the noise of monthly budgets and credit scores to reveal the true burden of debt. For individuals, it might expose over-reliance on home equity loans; for businesses, it could highlight excessive trade credit. The calculation itself is straightforward, but the interpretation depends on industry benchmarks, personal risk tolerance, and the type of liabilities involved. What complicates the process is the interplay between net worth and liabilities. A rising home value might boost net worth, but if that same home secures a variable-rate loan, the debt ratio could spike unexpectedly. Similarly, student loans classified as long-term liabilities might appear manageable until interest rates rise. The ratio doesn’t just reflect past decisions—it predicts future financial flexibility. Lenders, investors, and even personal financial planners use it to assess whether a borrower’s assets can absorb shocks, from job loss to market downturns.Historical Background and Evolution
The concept of debt ratios traces back to medieval merchant ledgers, where traders recorded assets against debts to assess solvency. By the 19th century, banks formalized these ratios to evaluate loan applicants, distinguishing between speculative borrowers and those with collateral-backed stability. The modern debt-to-net-worth ratio emerged in the 20th century as personal finance became democratized, with institutions like FICO scoring systems refining how liabilities were weighted against assets. The 2008 financial crisis exposed flaws in this system—many households had low debt-to-income ratios but high debt-to-net-worth ratios due to inflated home values, leading to mass foreclosures. Today, the ratio is a cornerstone of financial literacy programs, from university courses to robo-advisors. Its evolution reflects broader economic shifts: the rise of consumer credit in the 1980s, the dot-com bubble’s impact on equity-based borrowing, and the post-2008 emphasis on liquidity over leverage. The metric has also adapted to new asset classes—cryptocurrency holdings, for instance, complicate net worth calculations, while peer-to-peer lending introduces non-traditional liabilities. Understanding its history isn’t just academic; it reveals why some debt structures are sustainable while others are ticking time bombs.Core Mechanisms: How It Works
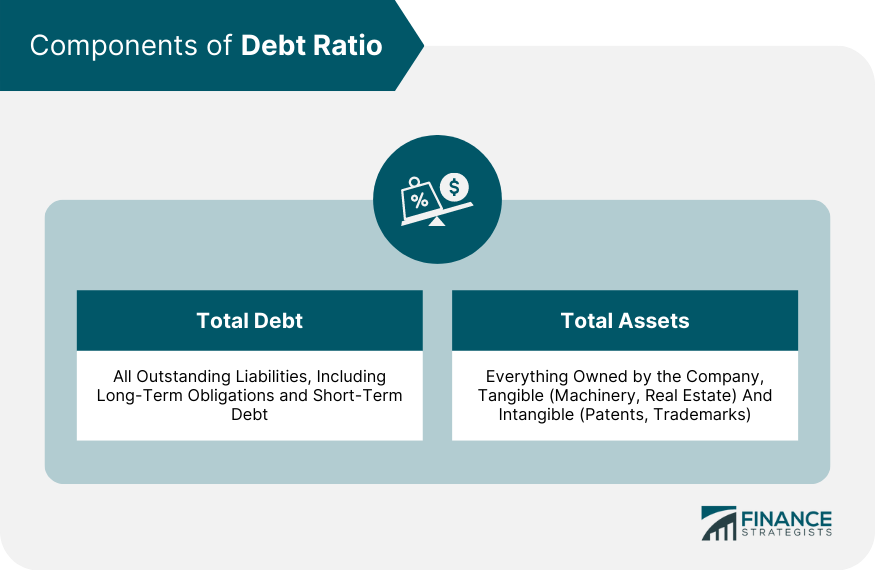
The formula for how to find debt ratio from net worth and liabilities is: Debt Ratio = Total Liabilities ÷ Net Worth At first glance, it’s arithmetic. But the devil lies in the definitions. Total liabilities include all debts: mortgages, credit cards, student loans, auto loans, and even unpaid taxes or medical bills. Net worth is the residual after subtracting liabilities from total assets—cash, investments, real estate, and intangibles like patents. The challenge is categorizing assets and liabilities accurately. A retirement account might be an asset, but if it’s leveraged (e.g., a margin account), the debt must be deducted from its value. The ratio’s power lies in its simplicity and its ability to normalize financial positions. A family with $500,000 in home equity and $200,000 in mortgage debt has a 40% ratio, regardless of income. This makes it a useful tool for comparing households across income brackets or geographic regions. However, the ratio doesn’t account for the type of debt—high-interest credit card debt carries more risk than a fixed-rate mortgage—nor does it reflect cash flow. That’s why it’s often used alongside other metrics, like the debt-to-income ratio or liquidity ratios.Key Benefits and Crucial Impact
Few financial metrics offer as clear a picture of risk exposure as the debt ratio derived from net worth and liabilities. It’s the difference between a household that can absorb a 20% market correction and one that faces foreclosure. For lenders, it’s a filter for high-risk applicants; for individuals, it’s a wake-up call about overleveraging. The ratio forces a reckoning with the true cost of debt—not just monthly payments, but the percentage of one’s financial foundation tied to obligations. This clarity is why it’s a staple in financial planning, from estate strategies to retirement projections. The ratio’s impact extends beyond personal finance. Businesses use it to negotiate terms with suppliers or secure lines of credit. Investors scrutinize it to identify undervalued companies with low leverage. Even governments monitor aggregate debt-to-net-worth ratios to gauge economic stability. Its versatility stems from its ability to distill complex financial positions into a single, actionable number."A high debt ratio isn’t a death sentence—it’s a red flag that demands a strategy. The question isn’t whether you have debt, but whether your assets can outrun it." — Robert Kiyosaki, Rich Dad Poor Dad
Major Advantages
- Risk assessment: Identifies households or businesses vulnerable to economic downturns or interest rate hikes.
- Leverage transparency: Reveals whether debt is being used productively (e.g., to generate income) or destructively (e.g., consumer spending).
- Benchmarking tool: Allows comparison against industry standards (e.g., a 30% ratio may be safe for a manufacturer but alarming for a tech startup).
- Debt management focus: Highlights which liabilities are most critical to address (e.g., variable-rate debt vs. fixed-rate).

Comparative Analysis
| Metric | Purpose |
|---|---|
| Debt-to-Net-Worth Ratio | Measures overall leverage; highlights long-term solvency risk. |
| Debt-to-Income Ratio | Assesses monthly cash flow; used by lenders to approve loans. |
| Liquidity Ratio | Evaluates short-term ability to cover obligations; critical for businesses. |
Future Trends and Innovations
As financial technology advances, the traditional debt ratio may evolve to incorporate real-time data. Blockchain-based ledgers could automate liability tracking, while AI might analyze spending patterns to predict debt risk before it materializes. The rise of gig economy income—often irregular and untaxed—will also challenge static net worth calculations, pushing ratios to adopt dynamic adjustments. Meanwhile, environmental, social, and governance (ESG) factors may influence how liabilities are classified, with sustainable debt (e.g., green bonds) treated differently from speculative borrowing. The ratio’s future may also lie in personalization. Today, a 40% ratio is a one-size-fits-all warning. Tomorrow, algorithms could tailor benchmarks to individual risk profiles, considering factors like age, career stability, and asset liquidity. The goal isn’t to replace human judgment but to refine the metric’s predictive power—especially as economic volatility increases.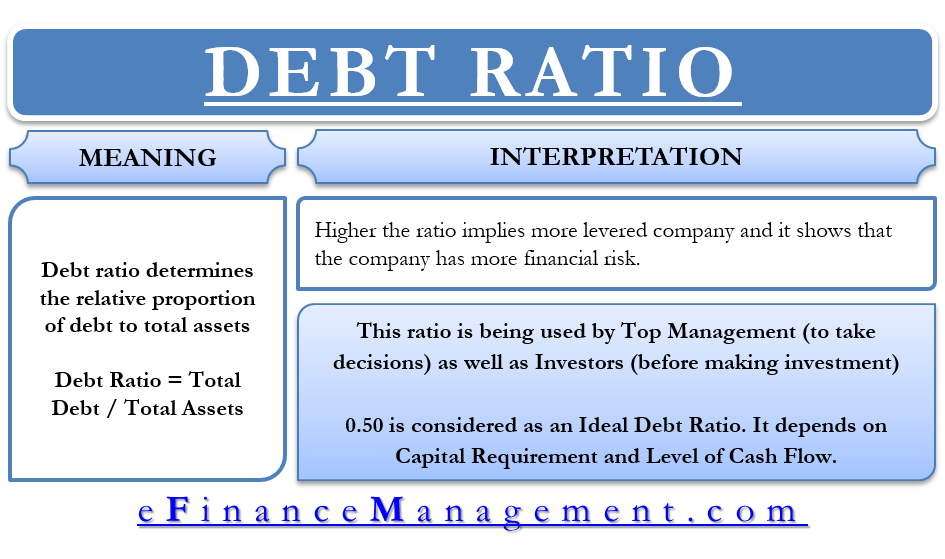
Conclusion
Understanding how to find debt ratio from net worth and liabilities isn’t just about crunching numbers; it’s about recognizing the invisible strings attached to financial freedom. The ratio exposes the gap between perceived wealth and actual security, forcing a conversation about priorities. For some, it’s a call to refinance debt; for others, it’s a signal to build emergency reserves. Ignoring it is like sailing without a compass—you might reach your destination, but the journey could be far riskier than anticipated. The metric’s enduring relevance lies in its simplicity and its ability to cut through financial jargon. In an era of complex investment products and algorithmic trading, the debt ratio remains a grounded reminder: Debt is a tool, not a trap. Used wisely, it can accelerate growth; misapplied, it can erode security. The first step is calculating it accurately—and then asking the harder questions about what it reveals.Comprehensive FAQs
Q: What’s the ideal debt-to-net-worth ratio?
A: There’s no universal "ideal" ratio, but financial advisors often suggest keeping it below 30–40% for households. Ratios above 50% may indicate high risk, especially if liabilities are short-term or high-interest. Context matters—businesses in capital-intensive industries (e.g., manufacturing) may operate with higher ratios than service-based firms.
Q: Should I include all debts in the calculation?
A: Yes. All liabilities—mortgages, credit cards, student loans, personal loans, and even unpaid medical bills—should be factored in. Some debts (e.g., those owed to family) might be excluded if they’re informal, but formal obligations must be accounted for to reflect true financial exposure.
Q: How often should I recalculate my debt ratio?
A: At minimum, annually or whenever major financial changes occur—home purchases, refinancing, inheritance, or significant debt payoff. Market fluctuations (e.g., stock or real estate downturns) can also shift net worth dramatically, making periodic checks essential.
Q: Can a high net worth hide a problematic debt ratio?
A: Absolutely. A high net worth from illiquid assets (e.g., real estate) might inflate the denominator, masking a high debt ratio. For example, a $2 million home with a $1.5 million mortgage has a 75% ratio—even if the home’s value is high. Always assess liquidity alongside the ratio to understand true financial flexibility.
Q: How does this ratio differ for businesses vs. individuals?
A: For businesses, the ratio often includes operational liabilities (e.g., accounts payable) and long-term debt (e.g., equipment loans). Industries with high capital requirements (e.g., airlines, manufacturing) may have higher acceptable ratios (50–70%) than service-based businesses (20–40%). Individuals, meanwhile, focus on personal liabilities and household assets.
Q: What if my ratio is high but my income is stable?
A: A high ratio with stable income suggests leverage is manageable—but only if liabilities are fixed-rate and assets are liquid. If debts are variable-rate (e.g., credit cards) or assets are illiquid (e.g., a single-family home), the risk increases. In such cases, strategies like refinancing or building emergency reserves can mitigate exposure.
