5 Things Worth Knowing About How to Determine Net Worth for FAFSA
The FAFSA’s net worth assessment isn’t a static snapshot but a moving target shaped by federal formulas, institutional overrides, and state-specific variations. Below are five critical insights that separate accurate filings from costly errors.1. The FAFSA Uses a Two-Year Lookback—But Not for Everything
The FAFSA’s Student Aid Index (SAI) replaces the old Expected Family Contribution (EFC) but retains the same core principle: aid eligibility is determined by what a family can reasonably contribute over the next academic year. However, the formula doesn’t treat all assets equally. Income from the prior tax year is fully considered, but assets like home equity or retirement accounts are subject to asset protection allowances that vary by state and institution. For instance, a family with $200,000 in home equity might see that value excluded entirely if their primary residence is below a certain threshold—yet the same equity could be counted against them if they own a second property. The key is understanding which assets are liquid in the eyes of the FAFSA and which are exempt. The real pitfall lies in timing. The FAFSA uses prior-prior-year (PPY) income—meaning the tax return filed two years before the academic year—but assets are evaluated as of the date of application. A stock portfolio that grew by 20% between January and April could push a family into a higher aid bracket if not reported correctly. This is why financial advisors recommend filing the FAFSA as early as October 1st, even if tax returns aren’t finalized, to avoid last-minute asset revaluations.2. Retirement Accounts Are Both Shielded and Vulnerable
Retirement savings—401(k)s, IRAs, pensions—are generally exempt from FAFSA asset calculations, a rule designed to protect families’ long-term security. However, this exemption has critical exceptions. If a parent or student takes withdrawals or loans from these accounts to pay for college, the FAFSA will treat that cash as an asset in the following year’s application. For example, a parent who withdraws $50,000 from a 401(k) to cover tuition in 2023 will see that amount counted as an asset in the 2025 FAFSA, potentially reducing aid eligibility. The formula doesn’t distinguish between educational expenses and other withdrawals—only the timing matters. What’s often overlooked is the 10% early-withdrawal penalty on IRAs (unless used for qualified higher education expenses). Families might assume they can avoid FAFSA scrutiny by tapping retirement funds, but the tax implications and aid repercussions create a double penalty. The solution? Prioritize scholarships, grants, and federal loans before touching retirement accounts—unless the account is already in a Roth IRA, where contributions (not earnings) can be withdrawn penalty-free.3. Business Owners Face a Brutal Double Standard
Small business owners and self-employed individuals encounter the FAFSA’s most aggressive asset treatment. The formula doesn’t just look at cash reserves—it values the entire business at its fair market value, then subtracts liabilities. For a family-owned restaurant with $500,000 in equipment and $200,000 in debt, the FAFSA might still count the net $300,000 as an available asset, even if the business generates no liquid cash. This is where the business net worth formula diverges sharply from personal net worth: the FAFSA assumes the business could be sold to fund college, regardless of industry realities. The damage extends to depreciation and amortization. While accountants deduct these expenses to reduce taxable income, the FAFSA ignores them entirely when valuing a business. A sole proprietor with a $1 million business might see their how to determine net worth for FAFSA calculation treat the full $1 million as an asset, even if their annual take-home pay is $80,000. The only mitigation is to structure the business as an S-corp or LLC and demonstrate that distributions to owners are irregular, but even then, the FAFSA’s asset rules remain inflexible."The FAFSA’s business valuation rules were written for Wall Street, not Main Street. A family farm with $2 million in land and equipment might get counted as a $2 million asset, even if the family lives on $60,000 a year. There’s no room for nuance in the formula." — Mark Kantrowitz, FAFSA expert and publisher of SavingForCollege.com
4. Home Equity Is a Wildcard—And Often a Trap
Real estate is the most misunderstood asset in FAFSA calculations. The formula excludes the primary residence’s equity up to a certain limit, but the rules vary by state and institution. For example, the federal asset protection allowance for a family’s home is $500,000 (as of 2023), but some states—like California—use a $1 million exemption. However, if a family owns a second home or rental property, the FAFSA will count the full equity as an available asset, even if it’s mortgaged. This is why affluent families in high-cost areas (e.g., New York, San Francisco) often see their aid packages shrink dramatically: the FAFSA assumes they could liquidate property to pay tuition. The real catch? Home equity loans and HELOCs. If a family takes out a loan against their home to pay for college, the FAFSA will treat that debt as additional assets in the following year’s application. For instance, a $100,000 HELOC used for tuition in 2023 will appear as a $100,000 asset in 2025, offsetting any aid increases. The solution? Use home equity loans only for non-educational expenses or structure repayments to avoid FAFSA scrutiny.5. The "Zero Asset" Loophole Isn’t What You Think
Many families assume that holding assets in a child’s name will reduce their FAFSA liability, but the formula has countermeasures. The Student Aid Index (SAI) now includes untaxed income (e.g., municipal bond interest, life insurance dividends) and certain business income reported on Schedule C. Even worse, the FAFSA’s dependency status rules mean that if a student is considered independent (e.g., over 24, married, or a veteran), their own assets are counted at a higher rate—20% of assets over $10,000 are expected to contribute to college costs, compared to just 5.64% for dependent students. The "zero asset" strategy—where families transfer wealth to trusts or custodial accounts—can backfire. The FAFSA’s Prior-Prior-Year (PPY) income rule means that if a parent gifts assets to a child, the child’s income from those assets (e.g., dividends, capital gains) will be counted against the family in the following year. For example, a parent who gifts $50,000 to a child in 2023 will see that child’s 2024 taxable income (from investments) included in the 2025 FAFSA, potentially increasing the SAI and reducing aid.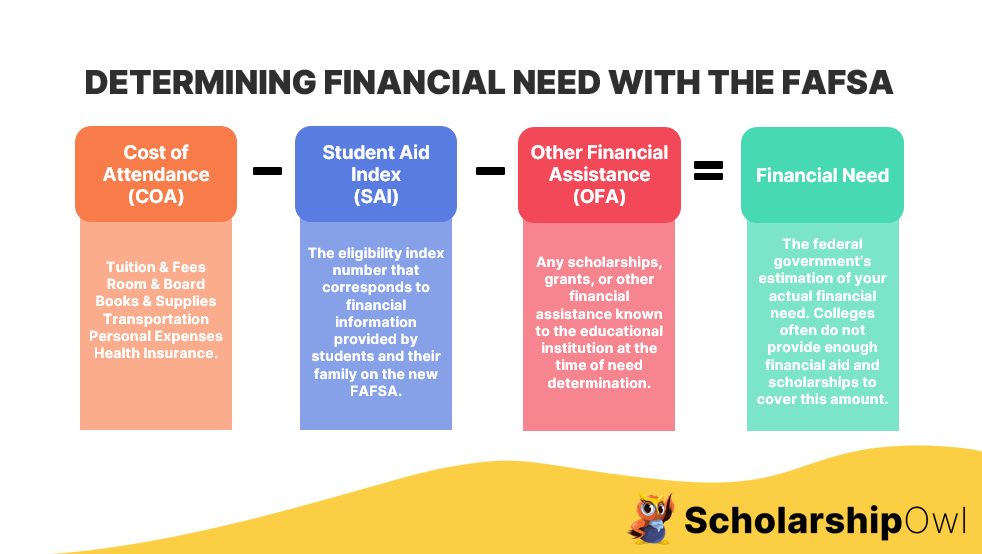
How These Facts Connect
The FAFSA’s net worth calculation isn’t arbitrary—it’s a risk-based system designed to prioritize aid for families with low liquidity and high fixed expenses. The five rules above reveal a pattern: the formula penalizes accessibility (e.g., home equity, business ownership) while rewarding liquidity (e.g., cash, brokerage accounts). This explains why a family with a $3 million home might qualify for more aid than one with $3 million in stocks—the FAFSA assumes real estate is harder to convert to cash. The system also exposes a generational bias. Older families with illiquid assets (e.g., farms, small businesses) are often disproportionately penalized, while younger families with high-income careers and liquid investments benefit from lower asset contribution rates. This isn’t an accident; it’s a byproduct of a formula that treats financial complexity as a liability.| Asset Type | FAFSA Treatment | Key Risk | Mitigation Strategy |
|---|---|---|---|
| Retirement Accounts (401k, IRA) | Exempt unless withdrawn | Withdrawals trigger asset counting in future years | Use scholarships/loans first; avoid Roth IRA conversions |
| Primary Residence Equity | Exempt up to $500k–$1M (state-dependent) | Second homes/rentals count fully | Keep primary residence as exempt; avoid HELOCs for tuition |
| Small Business Value | Full net worth counted as asset | No depreciation adjustments allowed | Structure as S-corp; document irregular distributions |
| Investment Accounts (Brokerage, etc.) | Counted at 20% contribution rate | Highly liquid = higher aid reduction | Hold in dependent student’s name (if under 24) |

Conclusion
Understanding how to determine net worth for FAFSA isn’t about gaming the system—it’s about aligning your financial strategy with the formula’s blind spots. The biggest mistake families make is assuming the FAFSA’s asset rules are fair or logical. They’re not. The system is designed to favor liquidity over stability, which means families with complex finances (business owners, real estate investors, retirees) often need aggressive planning just to access basic aid. The good news? There are legal ways to soften the impact—through strategic asset placement, timing withdrawals, and leveraging institutional aid overrides. The bad news? The rules change frequently, and what worked in 2022 might fail in 2025. The takeaway is simple: treat the FAFSA like a tax return. Just as accountants optimize deductions, financial aid experts optimize asset reporting. The difference is that the FAFSA’s penalties for misreporting aren’t just fines—they’re lost aid that can’t be reclaimed. For families with $100,000+ in assets, the difference between a well-structured filing and a rushed one can be $20,000 or more in aid per year.Comprehensive FAQs
Q: Does the FAFSA count my parents’ retirement accounts if they’re not on the application?
A: No, retirement accounts (401(k)s, IRAs, pensions) owned by parents are not counted on the FAFSA if they’re not included in the student’s application. However, if a parent withdraws funds from their retirement account to pay for the student’s education, those withdrawals will be treated as student assets in the following year’s FAFSA. This can increase the Student Aid Index (SAI) and reduce aid eligibility.
Q: What happens if I underreport assets on the FAFSA?
A: Underreporting assets is fraud and can lead to:
- Denial of federal aid (and sometimes state aid)
- Repayment demands for any aid already received
- Fines up to $20,000 and potential criminal charges under the Higher Education Act
Q: Can I transfer assets to my child to reduce my FAFSA liability?
A: No—this is a common myth. The FAFSA’s dependency rules mean that if a student is under 24 and considered dependent, their assets are counted at a lower rate (5.64%) than parents’ assets (47.24%). However, transferring assets to a child can backfire because:
- The child’s untaxed income (e.g., from investments) will be counted against the family in the following year’s FAFSA.
- If the child is over 24 or independent, their assets are counted at a higher rate (20%).
- The IRS has gift tax rules—transfers over $18,000 per year (2024 limit) may trigger taxable events.
Q: How does the FAFSA treat cryptocurrency and NFTs?
A: Cryptocurrency and NFTs are counted as assets on the FAFSA, but their valuation is tricky. The formula requires reporting the fair market value as of the date of application, not the purchase price. For example:
- A Bitcoin held at $50,000 in 2022 but worth $30,000 in 2024 must be reported at $30,000.
- NFTs with fluctuating values (e.g., Bored Ape collections) must be appraised at their current market price, not their original cost.
Q: What’s the difference between the federal FAFSA asset rules and a college’s institutional aid formula?
A: While the federal FAFSA uses the Student Aid Index (SAI) formula, private colleges often have their own asset rules, which can be more generous or stricter:
- Need-Aware Schools (e.g., Harvard, Stanford): May consider additional assets (e.g., home equity, business value) beyond the FAFSA’s basic formula.
- Need-Blind Schools (e.g., MIT, Rice): Still use the FAFSA SAI but may override decisions based on demonstrated need.
- State Schools (e.g., UC System, CUNY): Often mirror federal rules but may have higher asset protection allowances for in-state families.
Q: How often should I update my FAFSA if my net worth changes?
A: The FAFSA is annual, but major life changes (e.g., job loss, divorce, inheritance) require immediate updates via the FAFSA Correction process:
- Income Changes: If a parent loses a job or takes a pay cut, submit a FAFSA Correction with updated tax documents.
- Asset Changes: Selling a business, receiving an inheritance, or taking a large loan (e.g., HELOC) must be reported within 30 days to avoid aid penalties.
- Dependency Status: If a student turns 24, gets married, or becomes a veteran, refile the FAFSA as independent—this changes asset contribution rates.
Q: Are there any legal ways to "hide" assets from the FAFSA?
A: No—there are no legal loopholes to "hide" assets. However, there are strategic ways to minimize their impact:
- Asset Protection Allowances: Use the $500k–$1M home equity exemption (state-dependent) and retirement account exemptions.
- 529 Plans: Contributions grow tax-free and are reported as parental assets (not the student’s).
- Prepaid Tuition Plans: Some states allow tax-free prepayment of tuition, reducing countable assets.
- Timing Withdrawals: Avoid liquidating assets (e.g., stocks, bonds) in the two years before applying—the FAFSA uses prior-prior-year income but current asset values.
- Transferring assets to trusts (the FAFSA will still count them if the student/parent has access).
- Opening offshore accounts (the IRS and FAFSA require U.S. asset disclosure).
- Underreporting business value (schools verify with tax returns and appraisals).
