
Common Myths About Defining Net Value
The first misconception is that net value is synonymous with liquidity. People assume that if their bank account shows £50,000, their net value is £50,000—ignoring illiquid assets like property or private equity. In reality, define net value requires distinguishing between assets that can be sold quickly (cash, stocks) and those tied up in long-term commitments (real estate, collectibles). A 2022 study by the Financial Conduct Authority found that 42% of UK adults overestimated their net value by at least 20% due to this oversight. For example, a London penthouse might appraise at £2 million, but selling it could take six months and incur agent fees, legal costs, and stamp duty—leaving the owner with far less in hand. Another persistent myth is that net value is static. Financial planners often treat it as a fixed point, but market fluctuations, inflation, and unexpected expenses can shift it dramatically. A tech executive’s net value might spike after a successful IPO, only to plummet if the company’s stock crashes or a patent lawsuit drains cash reserves. Even for individuals, a sudden medical bill or a divorce settlement can redefine net value overnight. The term isn’t just a snapshot; it’s a dynamic measure of financial flexibility. Industry estimates suggest that high-net-worth individuals (HNWIs) with volatile portfolios see their net value swing by 15–30% annually, depending on asset allocation. Yet most people treat it like a photograph rather than a moving target. The third myth is that net value is purely personal. Business owners, in particular, conflate company valuation with their own financial standing. A sole trader’s net value isn’t just their business’s assets minus liabilities—it’s their personal assets minus business debts, plus their ability to extract value without collapsing the enterprise. For instance, a restaurant owner might list their premises and equipment as assets, but if they’re personally liable for a lease breach, that liability erodes their net value far beyond the business’s balance sheet. Even in corporate settings, executives often confuse define net value with enterprise value, overlooking how their personal financial exposure (e.g., unsecured loans, guarantees) affects their true worth.Myth 1: Net Value = Bank Balance
The confusion stems from how people track their finances. A salary earner might glance at their current account and assume that’s their net value, but this ignores savings, investments, and debts outside of banking. For example, a doctor with £80,000 in a savings account and £150,000 in a pension fund—and £50,000 in student loans—has a net value far higher than their visible cash. The error becomes costlier when people make decisions based on incomplete data, such as taking on risky investments or failing to plan for retirement. According to the Office for National Statistics, nearly 60% of UK adults don’t account for all their assets when calculating net value, leading to poor financial planning. The reality is that define net value requires a holistic approach. It’s not just what’s in your account; it’s the sum of all assets (tangible and intangible) minus all liabilities, including those not reflected in bank statements. Intangible assets—like intellectual property, professional licenses, or even a strong personal brand—can significantly boost net value, especially for freelancers or consultants. Meanwhile, hidden liabilities such as unpaid taxes, pending legal claims, or even the cost of replacing a worn-out car can drag net value down. A better framework is to categorize assets by liquidity: - High-liquidity: Cash, stocks, bonds (can be converted to cash in days). - Medium-liquidity: Real estate, business equity (weeks to months to liquidate). - Low-liquidity: Art, collectibles, or illiquid investments (years to realize value).Myth 2: Net Value Is the Same as Wealth
Wealth and net value are often used interchangeably, but they measure different things. Net value is a point-in-time calculation, while wealth is a long-term accumulation of assets that generate passive income or appreciation. A person with a high net value but no income streams (e.g., a retiree with a paid-off home but no pension) may struggle to maintain their lifestyle. Conversely, someone with modest net value but steady rental income or dividends could be considered wealthier in a broader sense. The distinction matters when planning for retirement, tax efficiency, or legacy building. The confusion arises because net value is a component of wealth, not its entirety. Define net value correctly by recognizing that wealth includes: - Growth potential: Assets that appreciate over time (e.g., stocks, property). - Income generation: Assets that produce cash flow (e.g., rental properties, royalties). - Risk mitigation: Assets that protect against inflation or market downturns (e.g., gold, diversified portfolios). A tech entrepreneur with a net value of £5 million but no diversified income streams might see that wealth erode if their company’s valuation drops. Meanwhile, a teacher with a £1 million pension and a £500,000 home might have lower net value but higher sustainable wealth.Myth 3: Net Value Is Only for the Rich
The assumption that net value is irrelevant to average earners stems from the perception that it’s a tool for the ultra-wealthy. In truth, define net value is critical at every income level because it reveals financial health. A young professional with £20,000 in student loans and £10,000 in savings has a negative net value, but tracking it helps them avoid further debt traps. Similarly, a middle-class family with a mortgage and car payments can use net value to assess whether they’re on track to build equity over time. The key is relative net value—how it compares to income, expenses, and life goals. For lower-income individuals, net value often hinges on asset-building strategies like: - Emergency funds: Even small cash reserves improve net value resilience. - Debt management: Paying down high-interest debt (e.g., credit cards) directly boosts net value. - Alternative assets: Skills, side hustles, or community resources can act as intangible assets. Industry data shows that households in the bottom 20% of earners often have negative net value due to debt, but those who focus on incremental asset growth (e.g., saving for a deposit) can flip this within a decade. The takeaway? Define net value isn’t about crossing a wealth threshold—it’s about understanding your starting point and the levers you can pull to improve it.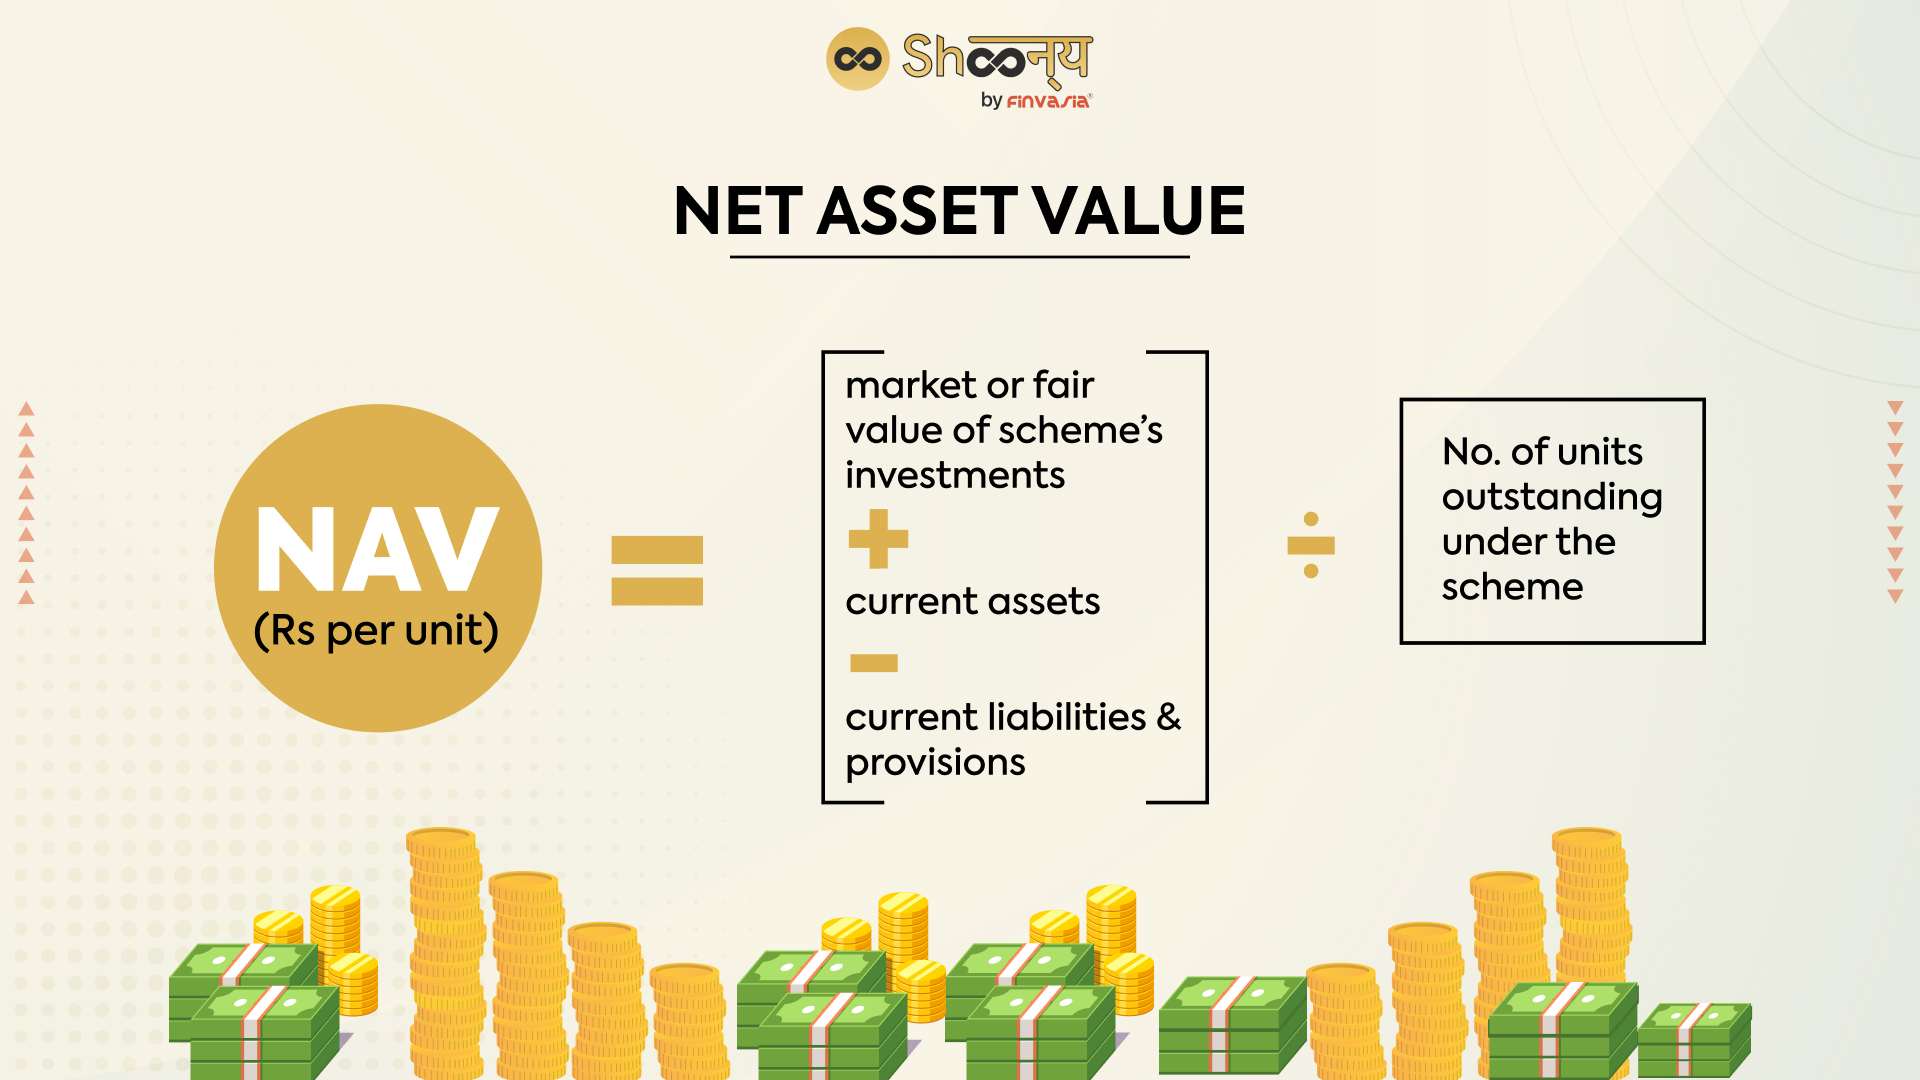
What Holds Up to Scrutiny
At its core, define net value means calculating: Assets (what you own) – Liabilities (what you owe) = Net Value But the rigor lies in how you classify each component. Assets should be valued at their realizable worth—not just book value or emotional attachment. For instance: - Primary residence: Appraised at market value, minus selling costs (agent fees, legal expenses). - Investments: Valued at current market price, not purchase price (avoiding the sunk-cost fallacy). - Business interests: Valued based on earnings multiples or comparable sales, not just revenue. Liabilities must include both obvious debts (mortgages, loans) and hidden obligations (pending lawsuits, future care costs). A common oversight is ignoring contingent liabilities—debts you might inherit, such as a co-signed loan or a partner’s unpaid bills. Even personal guarantees on business credit cards can drag down net value unexpectedly. What separates a rough estimate from a precise define net value is the inclusion of non-financial factors: - Liquidity risk: Can you sell assets quickly without loss? - Tax implications: Are there capital gains taxes or inheritance taxes looming? - Legal exposure: Are there lawsuits, divorces, or regulatory risks tied to your assets? A 2023 report by the Chartered Institute for Securities & Investment highlighted that 78% of high-net-worth individuals who failed to account for these factors saw their net value misrepresented by 30% or more.“Net value isn’t a number—it’s a story. It tells you whether you’re a creditor or a debtor, whether your assets are working for you or against you. The mistake isn’t in calculating it; it’s in ignoring what it doesn’t say.” — Jane Harper, Partner at Harper & Co. Wealth Advisory
| Common Belief | What the Evidence Says |
|---|---|
| Net value = assets minus liabilities (simple subtraction). | Net value must account for liquidity discounts, tax drag, and legal risks. A £1m property might only yield £800k after costs. |
| Higher net value always means better financial health. | Negative net value isn’t inherently bad if it’s part of a growth strategy (e.g., student loans for a high-earning career). |
| Business owners can use company valuation as personal net value. | Personal net value excludes business liabilities unless the owner is personally liable (e.g., sole traders). |
Why the Confusion Persists
The term define net value is deceptively simple, which fuels its misuse. Financial education often glosses over the nuances, treating it as a basic arithmetic exercise rather than a strategic tool. Banks and lenders, for example, may use simplified net value calculations for loan approvals, ignoring the full picture. This creates a feedback loop: people learn to associate net value with a single number, not the broader financial ecosystem. Cultural factors also play a role. In some societies, discussing personal finances is taboo, leading to reliance on oversimplified metrics like home ownership or salary as proxies for wealth. Meanwhile, the rise of social media has amplified the myth of "instant net value"—celebrities and influencers flaunt luxury lifestyles without disclosing debt or illiquid assets, distorting public perception. Even financial media often conflates net worth with net value, using the terms interchangeably despite their technical differences. The result? A generation that mistrusts financial data because it’s either too vague or too rigid.
Conclusion
Define net value isn’t about chasing a higher number—it’s about clarity. It’s the difference between assuming you’re financially secure because your house is paid off and realizing that your pension gap and healthcare costs could derail you in retirement. For businesses, it’s the gap between a balance sheet that looks strong on paper and one that would collapse under a liquidity crisis. The most valuable net value calculations aren’t the ones that impress at dinner parties; they’re the ones that help you make informed decisions under pressure. The key is to treat net value as a living document, not a static label. Recalculate it annually, adjust for market changes, and stress-test it against worst-case scenarios. Use it to ask harder questions: If I lost 20% of my investments tomorrow, could I cover my liabilities? What would happen if I couldn’t sell my biggest asset for six months? These aren’t hypotheticals—they’re the reality of define net value in action. The goal isn’t to achieve a specific number but to understand the levers you control and the risks you can’t.Comprehensive FAQs
Q: How often should I update my net value calculation?
A: At least annually, or more frequently if your financial situation changes—major purchases, debt repayments, market shifts, or life events (marriage, divorce, inheritance). For investors, quarterly updates may be prudent due to volatility. The critical factor is relevance: if your net value calculation isn’t guiding decisions, it’s outdated.
Q: Can net value be negative, and is that always bad?
A: Yes, negative net value occurs when liabilities exceed assets. It’s not inherently bad if it’s temporary (e.g., student loans for a high-earning career) or strategic (e.g., leveraging debt to acquire appreciating assets). However, chronic negative net value—such as high credit card debt with no asset growth—signals financial strain. The distinction lies in intent: is the debt an investment, or is it consumption?
Q: How do I value illiquid assets like a family home or a business?
A: For a primary residence, use a professional appraisal or recent comparable sales. Subtract estimated selling costs (agent fees, legal expenses, stamp duty). For a business, consider: - Earnings multiple: 3–5x annual profit (varies by industry). - Asset-based valuation: Sum of tangible assets minus liabilities. - Market approach: What similar businesses sold for recently? Avoid overvaluing sentimental assets—define net value requires cold, realizable figures.
Q: Does net value include future income streams, like a pension or rental income?
A: No. Net value is a snapshot of current assets and liabilities. Future income streams (pensions, royalties, rental yields) are part of wealth planning, not net value. However, the present value of these streams (e.g., a pension’s lump-sum equivalent) can be included if you’re calculating total wealth—not just net value. The confusion arises because people conflate potential future cash flow with existing assets.
Q: How do taxes affect net value?
A: Taxes can erode net value in two ways: 1. Upfront costs: Capital gains tax, inheritance tax, or stamp duty reduce the realizable value of assets. 2. Ongoing liabilities: Income tax, dividend taxes, or VAT (for businesses) eat into cash flow, indirectly lowering net value over time. For example, selling a £1m property might yield only £850k after agent fees, legal costs, and capital gains tax. Always factor in after-tax net value when making decisions. Some jurisdictions offer tax-efficient structures (trusts, ISAs) to preserve net value—consult a specialist if your situation is complex.
Q: Is net value the same as market capitalization for a company?
A: No. Market capitalization is the total value of a company’s outstanding shares (shares × price). Net value for a business owner is their stake in the company minus personal liabilities, adjusted for liquidity and risk. For instance: - A private company with £10m in assets and £2m in debt has a net asset value of £8m. - If the owner holds 30% equity, their business-related net value is £2.4m—but their personal net value might be lower if they’ve taken on personal guarantees or have other debts. Public companies often trade at a premium to net asset value due to growth potential, but private businesses may trade at a discount due to illiquidity.
