Breaking Down the Numbers
The core principle of "adding back depreciation for net worth" is simple: reverse the accounting treatment of depreciation when calculating personal wealth. Instead of subtracting it as an expense (as businesses do for tax purposes), you restore the asset’s original cost to reflect its true market value. This adjustment aligns personal finance with economic reality—where assets are worth what someone else would pay today, not what was paid years ago minus tax-friendly deductions. The challenge lies in the data. Most people track depreciation passively, if at all. A small business owner might deduct $5,000 annually for machinery but never note that the machine’s actual value has dropped by $20,000 due to market conditions. The IRS allows depreciation as a tax shield, but net worth calculations demand a different approach: reconstructing the asset’s fair value by accounting for both tax-depreciated book value and real-world depreciation curves. This duality is why spreadsheets for net worth often include columns for "cost basis," "accumulated depreciation," and "current market value"—three distinct figures that rarely align.The Verified Baseline
Publicly traded companies disclose depreciation annually in their financial statements, but individuals rarely do. For those who maintain detailed records—common among entrepreneurs or investors—the process starts with verified asset registers. These documents list purchase dates, original costs, and IRS-approved depreciation schedules (e.g., MACRS for businesses). The next step is cross-referencing with independent appraisals or industry-standard depreciation tables (e.g., NADA guides for vehicles, BLS data for equipment). Take a 2018 commercial printer worth $120,000 at purchase. After five years of straight-line depreciation (assuming a 10-year lifespan), its book value is $60,000. However, a 2023 appraisal might value it at $40,000 due to technological obsolescence. To adjust net worth, you’d: 1. Start with the book value ($60,000). 2. Add back the $20,000 of tax-depreciated value (since it was never a cash outflow). 3. Subtract the $20,000 gap between book value and market value. The net effect? The asset’s true contribution to wealth is $40,000—not $60,000.What the Estimates Suggest
For assets without appraisals, estimates rely on depreciation curves. The IRS provides guidelines (e.g., 5-year property for computers, 7-year for furniture), but real-world depreciation often accelerates. A study by Cox Automotive found that luxury vehicles lose 53% of value in three years, far exceeding IRS schedules. Similarly, tech equipment might depreciate 30% annually in its first two years, then stabilize. Industry estimates suggest that unadjusted net worth can overstate wealth by 15–40% for asset-heavy portfolios. A 2022 survey of small business owners by the Federal Reserve revealed that 68% didn’t account for depreciation in personal net worth calculations, yet 42% of their assets were subject to rapid depreciation (e.g., vehicles, tech, inventory). The disconnect isn’t just academic—it affects loan eligibility, insurance valuations, and even divorce settlements, where assets are often split based on stated values rather than economic reality.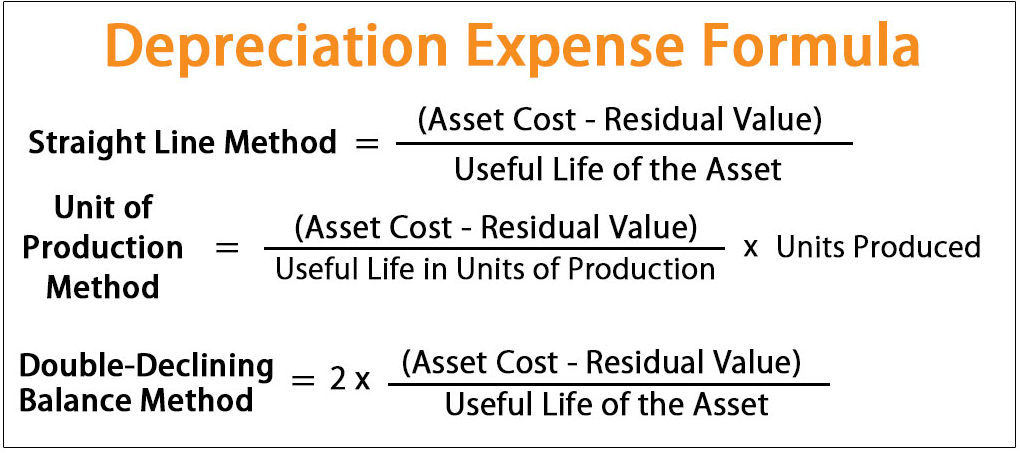
Case Study: A Closer Look
Consider a mid-sized manufacturing firm where the owner, Alex, reports net worth of $3.2 million. His balance sheet includes: - $1.8M in equipment (original cost), with $900K in accumulated depreciation (book value: $900K). - Market value estimates from a recent appraisal: $600K (due to outdated machinery). - Tax depreciation over 7 years: $257K/year (MACRS), totaling $1.8M in deductions. Alex’s unadjusted net worth treats the equipment as $900K. But to reflect true wealth: 1. Add back depreciation for net worth: Restore the $1.8M original cost (since depreciation was a tax benefit, not a cash expense). 2. Subtract market depreciation: The equipment is now worth $600K. 3. Net adjustment: ($1.8M – $600K) = $1.2M reduction from the book value. Result: Alex’s true net worth drops to $2.0M—a 37.5% adjustment. This isn’t a theoretical exercise; it’s why banks may reject loan applications based on inflated collateral values or why estate planners recommend liquidity buffers for depreciating assets."Depreciation is the silent wealth eroder. Clients often assume their balance sheet is gospel, but without reversing tax depreciation, they’re overestimating their safety net by margins that could cripple them in a downturn." — Jane Carter, CPA and Wealth Strategist (New York)
| Factor | Estimated Impact on Net Worth |
|---|---|
| Original equipment cost | $1.8 million |
| Accumulated tax depreciation (IRS schedule) | $900,000 (book value) |
| Current market value (appraised) | $600,000 |
| Net adjustment needed | -$1.2 million (from book to market) |
| Adjusted net worth (after correction) | $2.0 million (vs. $3.2M reported) |
What This Means Going Forward
The shift toward adding back depreciation for net worth is gaining traction among financial planners, but adoption remains uneven. High-net-worth individuals and business owners are the most affected, as their wealth is often tied to tangible assets. For them, the adjustment isn’t optional—it’s a risk management tool. A 2023 white paper by the National Association of Personal Financial Advisors (NAPFA) highlighted cases where clients faced liquidity crises because depreciation wasn’t factored into retirement projections. Technology is changing the game. Fintech tools like Wealthfront and Mint now include depreciation adjustments for select assets, though they often default to IRS schedules rather than market data. The next frontier? AI-driven depreciation models that pull real-time market values for assets like art, collectibles, or even cryptocurrency hardware. For now, manual adjustments remain the gold standard—but the gap between book value and economic value is narrowing as transparency demands grow.
Conclusion
Depreciation isn’t just an accounting footnote; it’s a wealth preservation issue. The phrase "add back depreciation for net worth" encapsulates a fundamental truth: personal finance must reconcile tax treatment with economic reality. Ignoring depreciation leads to overconfidence in asset-backed loans, misaligned estate plans, and flawed investment strategies. The solution isn’t complex—it’s systematic. Track original costs, monitor market values, and reverse tax depreciation when calculating net worth. For most people, this means upgrading from a simple spreadsheet to a dual-column system: one for tax reporting, another for true wealth tracking. The effort pays off in clarity, especially when assets represent a majority of net worth. In an era where wealth inequality is debated daily, precision in net worth calculations isn’t just good practice—it’s a safeguard against financial blind spots.Comprehensive FAQs
Q: Why does depreciation affect net worth differently for individuals vs. businesses?
A: Businesses use depreciation to spread costs over time for tax purposes, reducing taxable income annually. For individuals, depreciation is already a tax benefit—adding it back for net worth restores the asset’s original value, aligning it with market reality. The key difference is intent: businesses deduct depreciation as an expense; individuals must reverse it to avoid overstating asset values.
Q: Can I use IRS depreciation schedules for personal net worth adjustments?
A: IRS schedules (e.g., MACRS) are tax-driven, not market-driven. While they provide a starting point, they often underestimate real-world depreciation—especially for assets like vehicles or tech. For accurate net worth, cross-reference with independent appraisals or industry-specific depreciation curves (e.g., NADA for cars, BLS for equipment). The goal is to reflect what the asset could be sold for today, not its tax-depreciated book value.
Q: How often should I adjust for depreciation in my net worth?
A: Annually for high-depreciation assets (vehicles, tech, machinery) and every 3–5 years for slower-depreciating assets (real estate, collectibles). Rapidly changing markets (e.g., cryptocurrency mining rigs) may require quarterly checks. Automated tools can help, but manual reviews ensure accuracy—especially for unique or high-value assets where market data is scarce.
Q: Does adding back depreciation impact my tax liability?
A: No. Adjusting net worth for depreciation is a personal finance calculation, not a tax adjustment. The IRS already accounts for depreciation via deductions. However, if your net worth drops significantly after adjustments, it may affect loan eligibility (where collateral is valued) or estate planning (where asset liquidity matters). The two systems serve different purposes: taxes focus on income recognition; net worth focuses on economic value.
Q: What’s the easiest way to start tracking depreciation for net worth?
A: Begin with a simple spreadsheet with columns for: 1. Asset name (e.g., "2020 Toyota SUV") 2. Original cost 3. Accumulated tax depreciation (from receipts/tax returns) 4. Current market value (from appraisals or guides) 5. Adjusted net worth contribution = (Original cost – Accumulated depreciation) + Market value adjustment. For businesses, integrate with accounting software (e.g., QuickBooks) to pull depreciation schedules. For individuals, tools like Personal Capital or YNAB offer templates, though they may require manual tweaks for accuracy.
