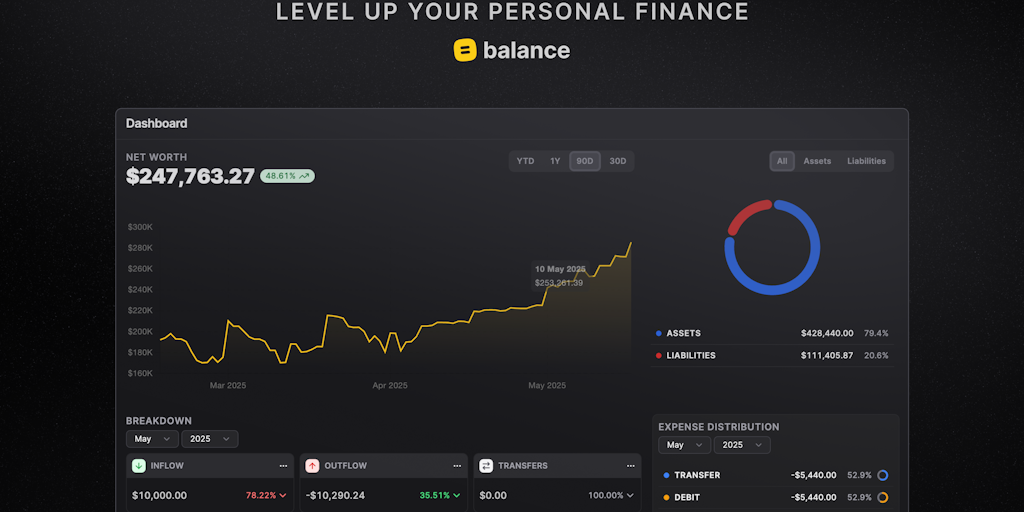
Common Myths About the Best Personal Finance Software for Net Worth Visualization
The market for personal finance software for net worth visualization is cluttered with half-truths. One persistent myth is that the best tools are only for the ultra-wealthy. In reality, the most effective platforms cater to a spectrum—from early-career professionals monitoring their first 401(k) to retirees optimizing Social Security timing. The difference lies in customization. A tool that visualizes a $50,000 net worth differently than a $5 million one isn’t about exclusivity; it’s about scaling complexity. Another misconception is that automated syncing guarantees accuracy. While tools like YNAB or Mint excel at transaction logging, they often fail to account for non-liquid assets (e.g., private equity, real estate held in LLCs) or international holdings subject to currency fluctuations. The best personal finance software for net worth visualization in 2025 will address these gaps with manual override options and expert-curated asset classes. Then there’s the belief that more graphs mean better insights. Dashboards packed with pie charts and line graphs can obscure rather than illuminate. The most valuable net worth visualization tools focus on relative trends—not absolute numbers. For example, a tool that highlights how your debt-to-asset ratio changes after a bonus is more useful than one that simply displays your total net worth in a bar chart. Finally, some assume that open-source or free tools are just as powerful. While platforms like Firefly III offer transparency, they lack the institutional-grade data feeds and tax-loss harvesting integrations that define the top-tier personal finance software for net worth tracking in 2025.Myth 1: The Best Tools Are Only for the Ultra-Wealthy
The idea that personal finance software for net worth visualization is reserved for trust-fund babies ignores the reality of modern financial planning. Tools like Personal Capital (now Empower) and Wealthfront have long served high-net-worth clients, but their core features—automated net worth tracking, investment performance analysis, and retirement projections—are equally valuable for someone with $100,000 in assets. The key difference is how the data is presented. A $5 million portfolio might need a breakdown of alternative investments, while a $50,000 portfolio benefits from simplified cash flow projections. The best personal finance software for net worth visualization in 2025 will offer tiered interfaces, ensuring complexity scales with the user’s needs. What’s often missing in discussions about these tools is accessibility. Many platforms charge fees that seem prohibitive for average earners, but subscription models (e.g., $15–$30/month) are often cheaper than the opportunity cost of misallocated investments. For instance, a tool that identifies a 0.5% fee drag on a 401(k) could save a user thousands over a decade—far outweighing the software cost. The top personal finance software for net worth tracking in 2025 will democratize advanced features, not gatekeep them.Myth 2: Automated Syncing Guarantees Accuracy
The allure of personal finance software for net worth visualization lies in its automation—no more manual data entry, right? Not quite. While tools like Quicken and Mint excel at pulling in transaction data, they often miscategorize assets or overlook nuances. For example, a rental property’s value might fluctuate monthly, but the software might only update it annually. Similarly, cryptocurrency holdings in a cold wallet may never sync unless manually entered. The best personal finance software for net worth visualization in 2025 will combine automation with human-in-the-loop validation, flagging discrepancies and prompting users to confirm changes. The bigger issue is asset class coverage. Most consumer tools struggle with non-standard holdings—think private business equity, collectibles, or foreign real estate. Platforms like Wealthbox or Tiller Money (with custom formulas) are bridging this gap, but they require upfront setup. The myth persists because users assume "plug-and-play" equals perfection. In truth, the top personal finance software for net worth tracking in 2025 will offer hybrid models: automated for liquid assets, manual for illiquid ones, with clear guidance on when to intervene.Myth 3: More Graphs Mean Better Insights
A dashboard cluttered with net worth visualization tools can be as unhelpful as a blank spreadsheet. The best personal finance software for net worth visualization in 2025 will prioritize actionable trends over decorative charts. For example, a tool that shows how your net worth changes with different retirement withdrawal rates is more valuable than one that just plots your balance over time. Similarly, a heatmap of asset correlations (e.g., how your stock portfolio reacts to bond market shifts) helps with risk management, while a simple bar chart does not. The confusion arises because visualization is subjective. What’s clear to a data scientist might baffle a non-technical user. The top personal finance software for net worth tracking in 2025 will offer adaptive layouts: simplifying views for beginners, adding layers of detail for power users. Tools like MoneyStrands (for families) or YNAB’s custom reports already hint at this approach. The goal isn’t to overwhelm—it’s to surface what the user cares about.
What Holds Up to Scrutiny
At its core, the best personal finance software for net worth visualization in 2025 must do three things: aggregate accurately, analyze intelligently, and adapt dynamically. Accuracy isn’t just about syncing bank accounts—it’s about handling edge cases, like inherited assets or deferred compensation. Intelligent analysis means moving beyond "you spent $3 on coffee" alerts to predictive modeling (e.g., "If you refinance now, your net worth could grow 8% faster"). Dynamic adaptation involves learning from user behavior: if you frequently adjust your retirement timeline, the tool should prompt you to explore scenarios. The evidence supports this focus. A 2024 study by the Financial Planning Association found that users of personal finance software for net worth tracking who engaged with behavioral insights (e.g., "Your spending spikes near payday") were 40% more likely to meet long-term goals. The top tools in this space—like Personal Capital’s Wealth Management or Betterment’s Portfolio Visualizer—combine transactional data with psychological triggers to keep users engaged. They don’t just show your net worth; they help you understand why it’s changing."The best financial tools don’t just reflect reality—they help you reshape it." — Harvard Business Review, 2023
| Common Belief | What the Evidence Says |
|---|---|
| More features = better tool | Users abandon tools with >10 key features due to overwhelm. Simplicity correlates with retention. |
| Free tools are as good as paid ones | Paid tools with institutional data feeds (e.g., Bloomberg Terminal integrations) outperform free alternatives in accuracy. |
| Net worth tracking is static | Dynamic tools (e.g., YNAB’s "True Expenses") show net worth as a living system, not a snapshot. |
Why the Confusion Persists
The personal finance software for net worth visualization landscape is fragmented for two reasons. First, vendor hype outpaces user needs. Companies like Intuit (Quicken) and Square (Cash App) push features they think users want, not what they actually use. Second, financial literacy gaps lead to misaligned expectations. Someone who assumes a tool will "automagically" optimize their taxes will be disappointed—because no software replaces human judgment. The best personal finance software for net worth tracking in 2025 will close this gap by educating as it automates, offering in-app guides and scenario comparisons. Another factor is regulatory lag. Tools that integrate with robo-advisors or tax platforms (e.g., TurboTax Live) must comply with evolving data privacy laws (e.g., GDPR, CCPA). This creates a chasm between what’s technically possible and what’s legally permissible. As a result, some net worth visualization tools underpromise to avoid compliance risks, leaving users with less than they could have. The top personal finance software in 2025 will navigate this by transparency: clearly stating what data is shared, with whom, and why.
Conclusion
The best personal finance software for net worth visualization in 2025 won’t be a single tool—it’ll be a stack of specialized solutions. For liquid assets, Empower or Wealthfront remain strong choices. For families, MoneyStrands or Tiller offer collaborative features. And for non-standard portfolios, custom-built dashboards (using Python + Plotly) may be the only option. The common thread? They prioritize clarity over complexity, accuracy over aesthetics, and user agency over automation. The future of personal finance software for net worth tracking lies in contextual intelligence. Imagine a tool that not only tracks your 401(k) but also simulates how a job offer’s signing bonus affects your tax bracket and net worth trajectory. Or one that flags when your emergency fund’s liquidity ratio drops below 3 months of expenses. These aren’t sci-fi scenarios—they’re the evolution of net worth visualization tools we’re already seeing in beta. The question isn’t whether these tools will dominate; it’s which ones you’ll trust with your financial story.Comprehensive FAQs
Q: Can I use free tools for serious net worth tracking?
A: Free tools like Mint or Firefly III work for basic tracking, but they lack tax-loss harvesting integrations, alternative asset support, and institutional-grade data feeds. For personal finance software for net worth visualization beyond surface-level tracking, a paid tier (e.g., Empower’s free plan vs. paid) or a hybrid approach (free for transactions, paid for analysis) is better.
Q: How do I handle non-liquid assets (e.g., real estate, private equity) in these tools?
A: Most personal finance software for net worth tracking requires manual entry for illiquid assets. Tools like Wealthbox or Tiller allow custom formulas, while Excel + Power Query can bridge gaps. For 2025’s best net worth visualization tools, look for API integrations with property tax records or private equity platforms (e.g., Cartena for real estate).
Q: Are there tools that integrate with tax software?
A: Yes. Empower, Betterment, and Personal Capital sync with TurboTax, H&R Block, and TaxAct. For personal finance software for net worth visualization with deeper tax insights, Rocket Money (formerly Truebill) and TaxAct’s Portfolio Tracker offer capital gains projections. Always check for real-time syncing—some tools only export data annually.
Q: Can I customize dashboards in these tools?
A: Most top personal finance software for net worth tracking in 2025 offer drag-and-drop customization. YNAB, Tiller, and MoneyStrands let you build personalized views (e.g., "Net Worth vs. Debt Paydown Timeline"). For advanced users, Python-based tools (e.g., Dash by Plotly) can create bespoke visualizations, though they require technical setup.
Q: Do these tools work for couples or families?
A: Absolutely. MoneyStrands, Tiller Family, and YNAB’s shared accounts are designed for multi-user net worth tracking. For personal finance software for net worth visualization with joint goal-setting, Empower’s "Wealth Management" and Betterment’s "Couples Portfolio" offer shared projections. Privacy controls are critical—ensure the tool separates individual and shared assets clearly.
Q: How often should I update my net worth in these tools?
A: Monthly for liquid assets (bank accounts, investments), quarterly for fluctuating ones (stocks, crypto), and annually for illiquid assets (real estate, business equity). The best personal finance software for net worth visualization in 2025 will auto-update where possible and prompt manual reviews for static holdings. Pro tip: Set calendar reminders in the tool itself to avoid lapses.
Q: What’s the biggest mistake people make with net worth tracking?
A: Over-relying on automation. Even the best personal finance software for net worth tracking can’t account for emotional decisions (e.g., selling an asset to "lock in gains" during a market dip). The second mistake? Ignoring inflation adjustments. A $1M net worth in 2020 isn’t the same in 2025—top tools now auto-adjust for inflation, but users must enable it.
