
The Complete Overview of How to Calculate Your Liquid Net Worth
The concept of liquid net worth emerged from the intersection of personal finance and behavioral economics. Early 20th-century financial advisors focused on total net worth as the primary measure of financial health, but the 1980s and 1990s saw a shift as markets became more volatile. The dot-com bubble and subsequent crash revealed a harsh truth: paper wealth could vanish overnight if assets weren’t liquid. Institutions like Vanguard and Fidelity began emphasizing liquidity ratios in their client reports, and by the 2010s, fintech platforms like Personal Capital and Mint integrated liquid net worth calculations into their dashboards. The methodology itself was refined by practitioners who noticed a pattern: individuals with high liquid net worth were better positioned to weather crises, seize opportunities, and maintain control over their financial destinies. Today, how to calculate your liquid net worth is taught in financial literacy programs worldwide, from Harvard’s Kennedy School to the UK’s Money Advice Service. The framework has evolved to account for digital assets—a term that now includes cryptocurrencies, NFTs, and even loyalty points that can be converted to cash. Yet the core principle remains unchanged: liquidity is about accessibility, not just ownership. A hedge fund manager might have a net worth of $50 million, but if 90% of it is tied up in illiquid private equity stakes, their liquid net worth could be a fraction of that. This disconnect explains why some ultra-high-net-worth individuals rely on lines of credit or family offices to bridge liquidity gaps. The lesson? Wealth without liquidity is a house of cards waiting for the right wind to blow.Historical Background and Evolution
The origins of liquid net worth tracking can be traced to the post-World War II era, when economists began studying how households managed cash flow during economic instability. The term "liquid assets" was formalized in the 1950s by the Federal Reserve as part of its monetary policy reports, but it wasn’t until the 1970s that personal finance experts started advocating for individuals to monitor liquidity separately from total net worth. The oil crisis of 1973 and the subsequent stagflation period forced many to realize that even substantial savings could be depleted quickly if not managed carefully. By the 1990s, the rise of index funds and mutual funds made liquid investments more accessible to the average investor, but the dot-com crash of 2000 exposed a critical flaw: many assumed their 401(k) balances were liquid when they weren’t. The 2008 financial crisis accelerated the adoption of liquid net worth as a financial health metric. As housing values plummeted and stock markets crashed, individuals with high liquid net worth—those who had maintained cash reserves or held liquid investments—were far better equipped to survive. This period saw the birth of liquidity-focused financial planning, where advisors began recommending clients maintain an emergency fund equivalent to 3–6 months of living expenses in liquid form. The methodology also expanded to include alternative assets like peer-to-peer lending and crowdfunding investments, which, while illiquid in the traditional sense, could be converted to cash under certain conditions. Today, the calculation is a standard tool in both personal finance and corporate treasury management, with variations tailored to individual risk profiles and life stages.Core Mechanisms: How It Works
At its core, how to calculate your liquid net worth involves three primary steps: identifying liquid assets, accounting for liabilities, and applying a realistic liquidation timeline. The first step is the most critical. Liquid assets are those that can be converted to cash within 90 days without a substantial loss in value. This includes: - Cash and cash equivalents: Checking accounts, savings accounts, money market funds, and Treasury bills. - Publicly traded securities: Stocks, ETFs, and mutual funds traded on major exchanges. - Short-term bonds: Government or corporate bonds with maturities of less than one year. - Certain cryptocurrencies: While volatile, assets like Bitcoin or Ethereum can be sold quickly on exchanges, though transaction costs and market risk must be factored in. - Prepaid expenses or insurance settlements: If you have a life insurance policy with a cash value or prepaid rent, these may qualify. The second step is subtracting liabilities that must be settled within the same 90-day window. Credit card balances, personal loans, and short-term debt are deducted in full, while long-term liabilities like mortgages are only included if you intend to sell the underlying asset. The third step is where most people err: they assume all assets can be liquidated instantly. In reality, even stocks may take a few days to sell, and bonds could require advance notice. A more accurate approach is to categorize assets by their liquidation speed and apply a conservative estimate. For example, a stock held in a brokerage account might be fully liquid, while a private company stock could take months to sell.Key Benefits and Crucial Impact
Liquid net worth isn’t just a number—it’s a measure of financial resilience. Individuals who track it regularly can respond to opportunities or crises with speed, whether that means investing in a new business, covering an unexpected medical expense, or taking advantage of a once-in-a-lifetime real estate deal. The data backs this up: studies from the Federal Reserve and J.P. Morgan have shown that households with higher liquid net worth ratios recover more quickly from economic downturns. The reason is simple: liquidity reduces stress and eliminates the need for high-interest borrowing or asset fire sales during tough times. The psychological impact of knowing your liquid net worth is equally significant. Many people overestimate their financial security because they confuse total net worth with liquidity. A homeowner with a $1 million house and a $500,000 mortgage might feel wealthy, but if they lack cash reserves, they’re vulnerable to a single major expense. Tracking liquid net worth forces clarity. It reveals whether you’re truly prepared for the unexpected or living on borrowed time. For entrepreneurs, it’s even more critical—startups fail not because of lack of ideas, but because of lack of cash flow. A founder with a $10 million valuation but only $200,000 in liquid assets may find themselves unable to pay salaries or pivot when market conditions change."Liquidity is the lifeblood of financial freedom. You can own the most valuable assets in the world, but if you can’t access them when you need to, they’re just paper promises." — Morgan Housel, The Psychology of Money
Major Advantages
- Financial flexibility: The ability to act quickly on opportunities or mitigate risks without scrambling for cash.
- Reduced financial stress: Knowing you have a buffer against unexpected expenses or income disruptions.
- Better investment decisions: Avoiding forced sales of illiquid assets during market downturns.
- Improved credit and borrowing power: Lenders and investors view high liquid net worth as a sign of stability.

Comparative Analysis
| Metric | Liquid Net Worth | Total Net Worth |
|---|---|---|
| Definition | Assets convertible to cash within 90 days minus liabilities due within the same period. | Total assets minus total liabilities, including illiquid holdings. |
| Use Case | Emergency preparedness, opportunity funding, financial resilience. | Long-term wealth assessment, estate planning, tax reporting. |
| Key Assets Included | Cash, publicly traded stocks, short-term bonds, certain cryptocurrencies. | Real estate, private equity, collectibles, retirement accounts, life insurance. |
| Key Liabilities Included | Credit card debt, personal loans, short-term debt. | Mortgages, student loans, long-term debt (unless asset is liquidated). |
Future Trends and Innovations
The calculation of liquid net worth is evolving alongside technological and economic shifts. One major trend is the integration of how to calculate your liquid net worth with real-time financial tracking tools. Platforms like YNAB (You Need A Budget) and Wealthfront now offer liquidity scores that update daily, accounting for market fluctuations and pending transactions. This shift toward dynamic liquidity metrics is particularly relevant in the gig economy, where income streams are irregular and expenses can spike unexpectedly. Another innovation is the rise of "liquid alternative investments," such as private credit funds or fractional real estate platforms, which offer higher yields than traditional savings accounts while maintaining relative liquidity. These assets blur the line between liquid and illiquid, requiring individuals to rethink their definitions of liquidity. Additionally, the growth of decentralized finance (DeFi) and blockchain-based assets is forcing a reevaluation of what constitutes a liquid asset. While Bitcoin can be sold in minutes, smart contract-based loans or staked tokens may have lock-up periods, complicating the calculation. As these trends develop, the methodology for determining liquid net worth will need to adapt—balancing accessibility with the need for precise, actionable data.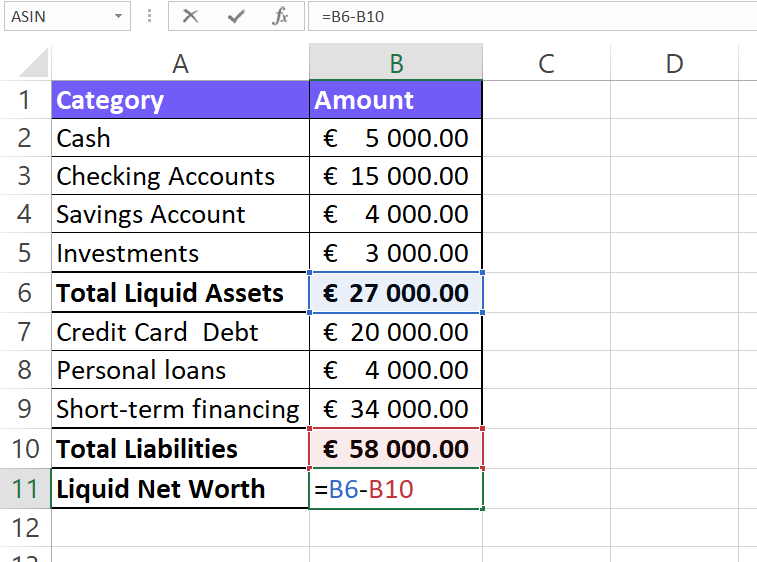
Conclusion
Understanding how to calculate your liquid net worth is more than a financial exercise—it’s a mindset shift. It moves the conversation from "what do I own?" to "what can I do with what I own?" This distinction is why liquid net worth is the metric that separates financial survivors from those who scramble when the unexpected happens. The process itself is straightforward, but the discipline required to maintain it is what truly matters. It’s not about hoarding cash; it’s about ensuring you have the right balance of assets that can be deployed when it counts. For most people, the exercise reveals uncomfortable truths—perhaps their emergency fund is smaller than they thought, or their investment portfolio isn’t as liquid as they assumed. But these revelations are the first step toward financial clarity. The goal isn’t to maximize liquidity at the expense of long-term growth; it’s to strike a balance that aligns with your goals, risk tolerance, and life stage. Whether you’re a freelancer, a retiree, or a high-net-worth individual, mastering this calculation will give you the confidence to navigate financial challenges—and seize opportunities—without hesitation.Comprehensive FAQs
Q: Does my retirement account count toward liquid net worth?
A: Generally, no—unless you’re willing to incur penalties or taxes by withdrawing early. Retirement accounts like 401(k)s or IRAs are considered illiquid for this calculation because accessing funds typically requires a trigger event (retirement, disability, or hardship) and comes with restrictions.
Q: What if I have a side hustle with irregular income?
A: Irregular income complicates liquid net worth calculations, but the key is to estimate your average liquid cash flow over the past 12 months. If your side hustle generates $3,000/month on average, you might allocate a portion of that toward liquid assets while keeping the rest in a separate buffer for tax obligations or slow periods.
Q: How do cryptocurrencies fit into liquid net worth?
A: Cryptocurrencies can be liquid if held on an exchange or in a hot wallet that allows quick sales. However, market volatility means their value can fluctuate wildly—so while they may be technically liquid, their usable liquidity depends on your risk tolerance. Some advisors recommend treating only a small percentage of crypto holdings as liquid, given the potential for sudden crashes.
Q: Should I include my home equity in liquid net worth?
A: Only if you’re prepared to sell or take out a home equity loan/line of credit (HELOC) within 90 days. Otherwise, home equity is illiquid because selling a property takes time, and HELOCs often come with fees or variable interest rates that reduce net liquidity.
Q: What about prepaid expenses, like a gym membership or travel vouchers?
A: These can be considered liquid if they can be converted to cash within 90 days. For example, unused vacation points or gift cards with cash redemption options may qualify. However, their value is often less than face value, so adjust accordingly.
Q: How often should I recalculate my liquid net worth?
A: At a minimum, quarterly—especially if your financial situation changes (e.g., new debt, investment purchases, or shifts in income). Market fluctuations also warrant periodic checks, particularly if you hold volatile assets like stocks or crypto.
Q: Can liquid net worth be negative?
A: Yes, if your short-term liabilities exceed your liquid assets. This is a red flag indicating you may need to build cash reserves or reduce high-interest debt. Negative liquid net worth doesn’t necessarily mean you’re in trouble, but it does signal a need for strategic planning.
