Breaking Down the Numbers
The realistic dividend percent of net worth isn’t static; it shifts with your age, spending habits, and portfolio composition. For example, a 30-year-old tech employee with a $200,000 net worth might aim for a 2% dividend income target ($4,000/year), while a 65-year-old retiree with $1.5 million might target 3–4% ($45,000–$60,000/year). The difference isn’t just age—it’s about how much of their net worth is in dividend-paying assets versus growth-oriented holdings. Dividend income should ideally cover discretionary spending, not essentials. If your dividends pay for vacations but not groceries, you’re on firmer ground than if they’re your sole income source. The realistic dividend percent of net worth also depends on whether you reinvest dividends or take them as cash. Reinvestment compounds returns over time, reducing the percentage you’d need to withdraw later. Conversely, taking dividends as cash means you’re relying on them to replace earned income, which requires a higher buffer.The Verified Baseline
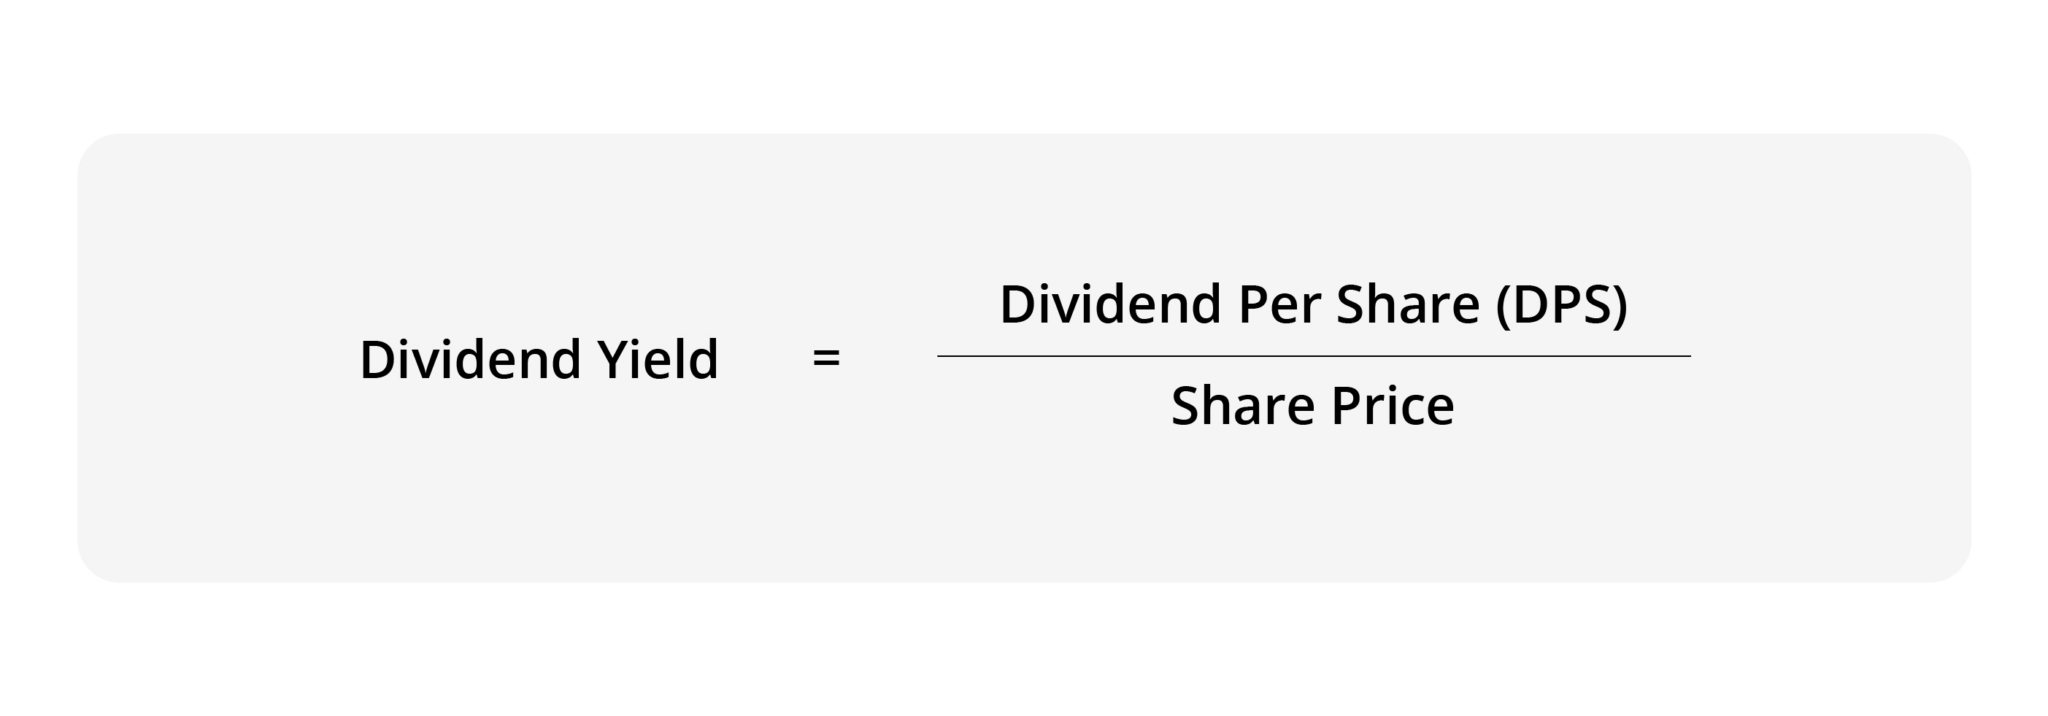
Historical data shows that the S&P 500’s average dividend yield has fluctuated between 2% and 4% over the past century, with periods of higher yields during recessions. However, these yields are not the same as a realistic dividend percent of net worth, which depends on how much of your portfolio is allocated to dividend stocks. For instance, if 50% of your net worth is in dividend-paying assets with a 3% yield, your dividend income would be 1.5% of your total net worth—not 3%. The 4% rule remains the most cited benchmark for sustainable withdrawals, but it assumes a 60/40 stock-bond mix with total returns (capital gains + dividends). If you’re relying solely on dividends, studies suggest a realistic dividend percent of net worth closer to 3% or less for most retirees, assuming a mix of high-quality dividend stocks and bonds. The key verified fact is that dividend growth stocks (like those in the S&P 500 Dividend Aristocrats index) have historically increased payouts by 5–6% annually, which can offset inflation over time.What the Estimates Suggest
Industry estimates for what is a realistic dividend percent of net worth vary widely based on portfolio construction. A 2020 study by Research Affiliates found that a portfolio tilted toward high-dividend stocks could generate 3–5% of net worth in dividends, but this assumes no capital losses and reinvestment of dividends. For retirees, financial advisors often recommend capping dividend withdrawals at 2–3% of net worth to avoid sequencing risk—the danger of selling assets at low prices during market downturns. Some ultra-high-net-worth individuals reportedly structure their portfolios to generate 4–6% of net worth in dividends, but this typically requires a mix of private equity, real estate, and tax-efficient dividend strategies. The catch? These strategies aren’t accessible to most investors and come with higher fees. For the average investor, the realistic dividend percent of net worth likely falls between 1.5% and 3.5%, depending on whether dividends are supplementary income or a primary funding source.
Case Study: A Closer Look
Consider the portfolio of a 55-year-old financial planner with a $1.2 million net worth, allocated as follows: - 60% in dividend stocks (yield: 2.8%) - 20% in bonds (yield: 3.5%) - 15% in cash equivalents - 5% in alternative investments Her annual dividend income from stocks alone would be $20,160 (60% × $1.2M × 2.8%), or 1.68% of net worth. Adding bond interest brings her total passive income to roughly 2.5% of net worth. This aligns with the realistic dividend percent of net worth for someone in accumulation phase, where the goal is growth first, income second. The planner’s strategy assumes reinvesting dividends until retirement, at which point she’ll adjust withdrawals to 3% of net worth ($36,000/year). This follows the 4% rule but with a dividend-focused twist: she’s banking on dividend growth to offset inflation. The trade-off? Her portfolio is less liquid than a traditional 4% withdrawal plan, as dividend stocks may not sell as easily in a downturn."Dividends are the interest payments of the stock market," says Morningstar’s director of personal finance. "But unlike bonds, they’re not fixed. The realistic dividend percent of net worth you can sustain depends on whether you’re counting on companies to keep raising payouts—or just living off today’s yield."
| Factor | Estimated Impact on Realistic Dividend Percent of Net Worth |
|---|---|
| Portfolio Allocation to Dividend Stocks | 50% allocation → ~1.5–2.5% of net worth; 70%+ → 3–5% (but higher risk) |
| Dividend Growth Rate | 5% annual growth → can sustain higher withdrawals over time; 0–2% growth → cap at 2% |
| Reinvestment vs. Cash Withdrawals | Reinvesting → higher long-term sustainability; taking cash → reduce target to 1.5–2.5% |
| Market Conditions | Low interest rates → higher yields but lower growth; high rates → lower yields but higher bond yields |
What This Means Going Forward
The realistic dividend percent of net worth you can aim for isn’t set in stone—it’s a moving target influenced by economic cycles, company performance, and your personal circumstances. For younger investors, the focus should be on building a dividend base rather than extracting income. This means prioritizing dividend growth stocks (like those with 10+ year histories of increases) and reinvesting aggressively. As you near retirement, the equation flips: preserving capital becomes more critical than chasing yield. Taxes and fees also distort the realistic dividend percent of net worth. Qualified dividends in the U.S. are taxed at lower rates than ordinary income, but high earners face phase-outs. International dividends may trigger withholding taxes. Meanwhile, mutual fund fees can eat into yields. A 3% dividend yield might become 2.5% after fees, reducing your realistic dividend percent of net worth by a third. Always calculate post-tax, post-fee income to avoid surprises.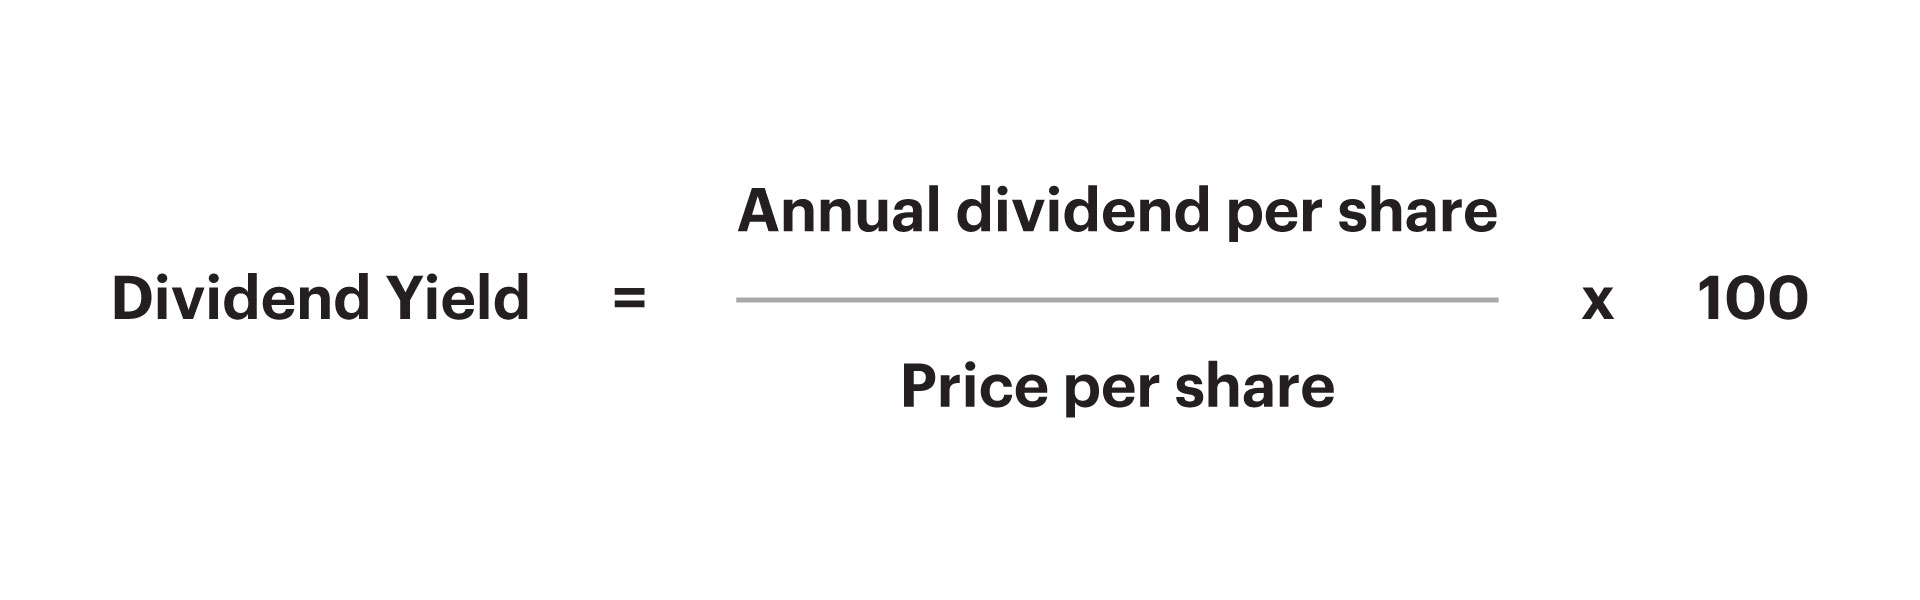
Conclusion
The search for what is a realistic dividend percent of net worth reveals that no single number works for everyone. It’s a personal equation that balances income needs, risk tolerance, and portfolio flexibility. For most investors, 1.5% to 3.5% is a reasonable range, but the sweet spot depends on whether dividends are a supplement or a lifeline. The safest approach is to treat dividends as one piece of a broader income strategy—pairing them with Social Security, pensions, or part-time work if needed. Ultimately, the realistic dividend percent of net worth isn’t about maximizing yield today; it’s about designing a portfolio that can weather downturns, adapt to inflation, and provide income without forcing you to sell assets at inopportune times. The investors who succeed are those who treat dividends as a tool, not a crutch.Comprehensive FAQs
Q: Can I live off dividends alone if I hit a 4% yield?
A: No. A 4% yield on your net worth assumes you’re withdrawing all returns (dividends + capital gains), not just dividends. If you rely solely on dividends, you’ll need a higher yield—or risk running out of money when dividends stagnate or stocks fall. The realistic dividend percent of net worth for a pure dividend strategy is closer to 3% or less, with reinvestment during growth years.
Q: How do I adjust my dividend target if I retire early?
A: Early retirement changes the calculus because you’ll need to stretch your portfolio over 30+ years. Financial planners often recommend a 3% or lower dividend withdrawal rate for early retirees, paired with a flexible spending plan. If your dividends cover only 50% of expenses, you’ll need to supplement with other income sources or accept a lower standard of living. The realistic dividend percent of net worth in this case may need to be as low as 1–2% to avoid depletion risk.
Q: Are high-yield dividend stocks (6%+) worth the risk?
A: High-yield stocks often carry higher risk—whether from financial distress (e.g., energy MLPs) or unsustainable payouts (e.g., REITs with high distributions). While they can boost your realistic dividend percent of net worth in the short term, they may not grow dividends over time. A better approach is to mix high-yield stocks (10–20% of your dividend portfolio) with dividend growth stocks (80%+) to balance income and sustainability.
Q: How do I account for dividend taxes when calculating my realistic dividend percent?
A: Dividend taxes reduce your net yield significantly. In the U.S., qualified dividends are taxed at capital gains rates (0–20%), while ordinary dividends are taxed as income (up to 37%). International dividends may face withholding taxes (e.g., 15% in many countries). To find your realistic dividend percent of net worth after taxes, multiply your gross yield by (1 – your tax rate). For example, a 3% yield with a 20% tax rate becomes 2.4% net. Always use post-tax figures in your calculations.
Q: What happens if my dividends don’t grow but my expenses do?
A: If dividends stagnate while inflation erodes purchasing power, you’ll face a realistic dividend percent of net worth crisis. To mitigate this, diversify into dividend growers (companies with histories of increasing payouts) and hold a portion of your portfolio in TIPS or inflation-protected assets. Some advisors suggest maintaining a liquidity buffer (1–2 years of expenses in cash) to cover shortfalls during dividend droughts.
