Breaking Down the Numbers
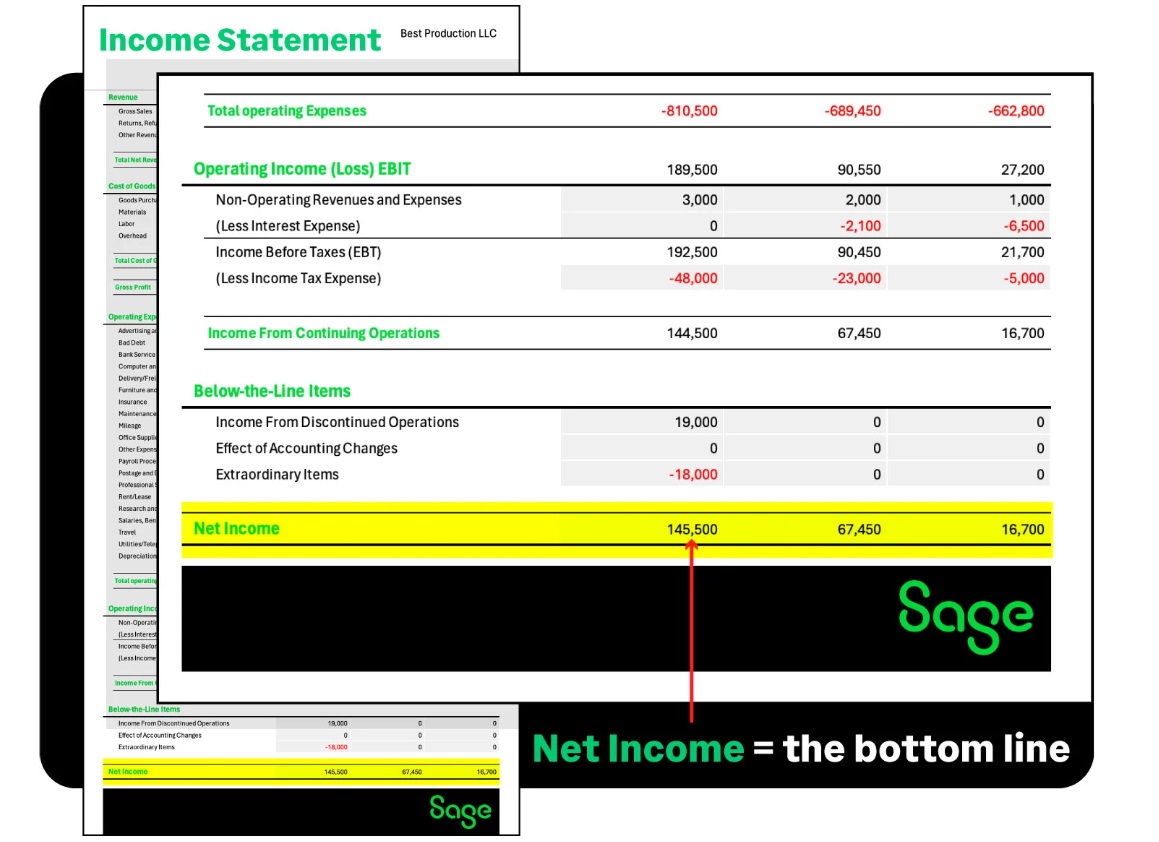
Income statements and net worth calculations operate in different currencies—one in cash flows, the other in asset-liability balances. Yet both share a common thread: the income statement’s bottom line (net income) is the primary driver of net worth changes over time. The problem? Net worth reflects historical asset valuations, while income statements capture current-period performance. Bridging this divide requires dissecting income statement components and mapping them to net worth drivers. Start with the income statement’s core: revenue minus expenses equals net income. That net income is the raw material for net worth growth—if it’s reinvested, saved, or used to pay down debt. But the relationship isn’t linear. A $100K net income might add $50K to net worth if $50K is spent on depreciating assets (e.g., equipment) or if taxes and living expenses consume the rest. The key is tracing how each income statement line item impacts net worth indirectly. For instance: - Revenue recognition timing (e.g., deferred revenue) delays net worth growth. - Non-cash expenses (e.g., amortization) don’t directly reduce net worth but distort reported profitability. - Capital expenditures reduce net income but increase long-term asset value—thus net worth. The income statement also exposes hidden liabilities. A company reporting high "other income" might be masking debt-fueled gains, which inflate short-term net worth but create long-term risk. Conversely, a business with low reported income but high retained earnings (from past profits) could have a net worth far exceeding its current statement.The Verified Baseline
For publicly traded entities, the baseline is straightforward: pull the income statement and balance sheet from the latest 10-K or annual report. Net worth (equity) is already calculated as assets minus liabilities. The income statement’s net income feeds into retained earnings, which is a direct line item in equity. However, how to calculate net worth on income statement for individuals or private businesses requires manual reconciliation. Individuals must: 1. List all assets (cash, investments, real estate, intellectual property) at fair market value. 2. List all liabilities (mortgages, loans, credit lines) at current balances. 3. Cross-reference income statement items with asset changes. For example: - Did the "salary expense" line match actual cash outflows? - Were "investment income" gains reinvested or spent? 4. Adjust for non-cash items. Depreciation reduces net income but doesn’t affect net worth directly—it’s already accounted for in asset valuations. The critical verification step is ensuring income statement "other adjustments" (e.g., stock-based compensation, one-time gains) are reflected in net worth. A common pitfall is ignoring accrual accounting effects: revenue recognized but not yet collected doesn’t boost net worth until cash is received.What the Estimates Suggest
Private companies and high-net-worth individuals often lack audited statements, forcing reliance on estimates. Here, how to calculate net worth on income statement becomes an exercise in triangulation. For example: - Revenue estimates: If a business reports $3M in revenue but industry peers suggest 20% is deferred, the effective net worth impact of that income is lower. - Expense hedging: A founder might underreport "owner’s draws" as personal expenses, inflating reported net income while depleting liquid assets—thus reducing net worth faster than the income statement suggests. - Asset valuation gaps: A privately held tech firm might value its IP at $2M on the balance sheet, but a forced sale could fetch $500K, shrinking net worth by $1.5M overnight. Estimates also matter for off-balance-sheet items. A consultant billing clients but not recording receivables until payment is received might show lower net income but higher actual cash flow—thus preserving net worth better than the income statement implies. The solution? Build a net worth waterfall model that maps income statement line items to asset/liability changes, then stress-test with conservative and aggressive scenarios.
Case Study: A Closer Look
Consider the 2020 financials of a mid-tier SaaS company, CloudSync, which reported $12M in revenue and $3M net income. On the surface, its net worth (equity) grew by $3M. But digging deeper reveals nuances: - Deferred revenue: $4M was recognized but not yet collected, meaning only $8M was "real" cash flow. - Stock-based compensation: $1.5M in equity awards diluted retained earnings, offsetting some net income. - Capital expenditures: $2M spent on R&D added to long-term assets, increasing net worth but reducing short-term liquidity. The income statement’s net income ($3M) didn’t fully translate to net worth growth because: 1. $1.5M was used to fund operations (not reinvested). 2. $0.5M went to taxes, reducing cash reserves. 3. $1M was retained in the business but tied up in inventory or prepaid expenses (non-liquid). Result: Net worth grew by $2M, not $3M."The income statement is a movie; net worth is the final cut. What looks like profit on paper might be smoke and mirrors if you’re not tracking where every dollar lands in the balance sheet." — Jane Park, CFO of a Series B venture-backed firm
| Factor | Estimated Impact on Net Worth |
|---|---|
| Deferred revenue recognition | Delayed net worth growth by ~$1.2M (until cash collected) |
| Stock-based compensation | Reduced equity by $1.5M (dilution effect) |
| Capital expenditures (R&D) | Increased net worth by $2M (long-term asset) but reduced cash flow |
| Taxes and operating expenses | Net cash outflow of ~$2M, directly reducing liquid assets |
| Unrecorded receivables | Potential understatement of net worth by $500K–$1M (if clients slow to pay) |
What This Means Going Forward
The future of net worth calculation lies in real-time reconciliation. Tools like YNAB (You Need A Budget) or QuickBooks Live now integrate income tracking with net worth dashboards, but manual oversight remains critical. For high-net-worth individuals, private equity firms, or startups, the process demands: - Automated data feeds linking bank transactions to income statement categories. - AI-driven anomaly detection to flag discrepancies (e.g., a sudden spike in "other expenses" that might hide embezzlement). - Scenario modeling to simulate how changes in revenue recognition (e.g., switching from accrual to cash-basis accounting) affect net worth. Regulatory shifts will also reshape the landscape. The SEC’s push for private company disclosures (e.g., SPACs) means more individuals will have access to income statement-level data, blurring the line between personal and corporate financial tracking. Meanwhile, crypto and NFT assets introduce new challenges: income statements may report gains, but net worth depends on volatile market valuations. The core principle remains: net worth is a lagging indicator; income statements are leading. Mastering how to calculate net worth on income statement isn’t about chasing precision—it’s about building a system that anticipates where income will land in the balance sheet before it’s too late.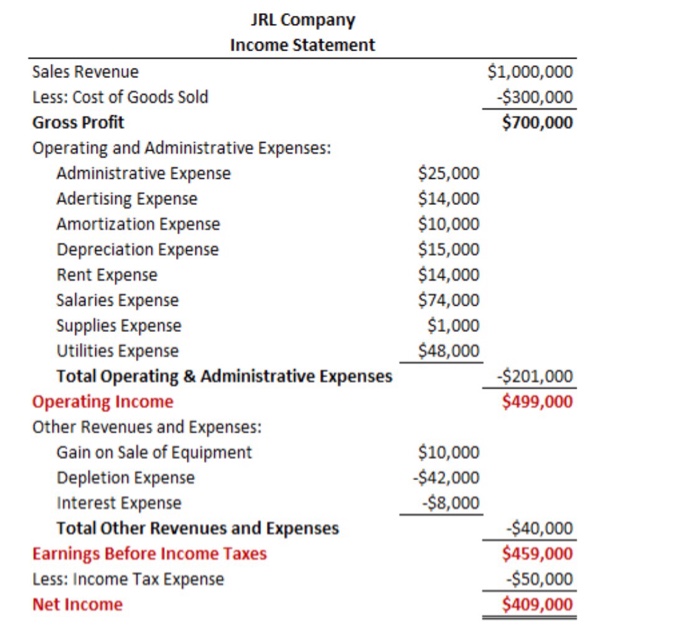
Conclusion
The income statement and net worth are two sides of the same coin, but most people treat them as separate currencies. The truth? They’re interconnected in ways that extend beyond accounting textbooks. How to calculate net worth on income statement isn’t a one-time calculation—it’s a dynamic process of alignment, verification, and forward-looking adjustment. For individuals, the exercise forces discipline: tracking every dollar’s journey from revenue to asset or liability. For businesses, it reveals inefficiencies—whether it’s overleveraging, under-recognized revenue, or assets that don’t translate to cash. The companies and individuals who thrive are those who stop treating net worth as a static number and start treating it as a financial narrative, with the income statement as its chapter-by-chapter breakdown.Comprehensive FAQs
Q: Can I calculate net worth directly from an income statement alone?
No. The income statement shows profitability, not asset-liability balances. You need a balance sheet to derive net worth (assets minus liabilities). However, you can use the income statement to project how net worth will change over time by analyzing reinvested earnings, dividends, or debt repayments.
Q: How do non-cash expenses (like depreciation) affect net worth?
Non-cash expenses reduce net income on the income statement but don’t impact net worth directly. They’re already accounted for in the balance sheet’s asset valuations. For example, $10K in depreciation lowers reported earnings but doesn’t change the book value of the underlying equipment.
Q: What if my income statement shows a profit, but my net worth is shrinking?
This typically happens when: 1. Revenue is deferred (cash hasn’t been collected yet). 2. Expenses are underreported (e.g., personal draws treated as business expenses). 3. Assets are depreciating faster than income grows (e.g., a manufacturing business with heavy equipment costs). 4. Debt is increasing (e.g., taking on loans to fund operations without proportional revenue growth).
Q: Should I adjust my net worth calculation for inflation?
Yes, but only if you’re comparing net worth over long periods. Inflation erodes the purchasing power of cash and fixed assets. For example, a $1M net worth in 2010 might equate to $1.3M in 2023 purchasing power. Use a real return calculator to adjust for inflation when analyzing historical net worth trends.
Q: How often should I reconcile my income statement with net worth?
For individuals: Quarterly (aligns with tax reporting cycles). For businesses: Monthly, especially if revenue or expenses are volatile. Automated tools can streamline this, but manual reviews catch errors like misclassified expenses or unrecorded liabilities.
Q: What’s the biggest mistake people make when linking income statements to net worth?
Assuming all net income translates to net worth growth. In reality, taxes, living expenses, and non-reinvested cash can consume profits without affecting assets or liabilities. The mistake is treating net income as a direct line item in net worth—it’s only a driver if the money is allocated to assets or debt reduction.
