
Common Myths About How to Calculate Net Worth from Salary
The first misconception is that net worth is synonymous with annual income. This oversimplification leads people to believe that doubling their salary will double their wealth, which ignores the role of expenses, taxes, and asset appreciation. For example, a software engineer earning $150,000 might see their take-home pay cut by 30% after taxes and deductions, leaving them with far less liquidity than a physician earning the same salary but benefiting from tax-advantaged retirement contributions and employer-matched 401(k) plans. How to calculate net worth from salary requires distinguishing between gross income and net disposable cash—two entirely different figures. Another persistent myth is that net worth only matters for the ultra-wealthy. While it’s true that billionaires obsess over asset diversification and tax optimization, the principle applies at every income level. A young professional with $50,000 in student loans but $20,000 in a high-yield savings account and a modest retirement fund still has a net worth worth tracking. The framework isn’t reserved for those with seven-figure balances; it’s a tool for anyone who wants to measure financial progress beyond a monthly bank statement.Myth 1: Net Worth = Salary Minus Monthly Expenses
This is the most common oversimplification. While monthly expenses are a critical component, they represent only a snapshot of financial health. A freelancer might have irregular income but substantial savings, while a corporate employee could have predictable paychecks but crippling credit card debt. How to calculate net worth from salary must account for both current liabilities and future earning potential—such as equity in a business, pension vesting schedules, or the value of skills that could lead to higher-paying opportunities. The error lies in treating expenses as static. A $3,000 rent payment in New York City carries different weight than the same amount in a low-cost market. Similarly, a $500 car payment might seem manageable until you factor in depreciation, insurance, and maintenance costs. Net worth calculations require contextualizing expenses against local cost of living, inflation trends, and long-term financial goals—not just a line-item subtraction.Myth 2: High Salary Equals High Net Worth
This is the "lifestyle inflation trap." A CEO earning $500,000 annually might live in a $2 million home, drive a luxury car, and send children to private school—leaving little room for savings or investments. Meanwhile, a mid-level manager earning $120,000 could live frugally, max out retirement accounts, and build a diversified portfolio. How to calculate net worth from salary exposes the gap between income and actual wealth accumulation. The issue isn’t the salary itself but the marginal utility of each dollar earned. For someone in the top tax bracket, an additional $100,000 might yield only $40,000 in take-home pay after taxes and deductions. That same increment for someone in the 25% bracket could mean $75,000 in new disposable income—assuming they don’t immediately upgrade their lifestyle. Net worth growth hinges on reinvesting surplus income into assets, not liabilities.Myth 3: Net Worth Is Only About Cash and Investments
Forgetting about non-liquid assets distorts the picture. A homeowner with a $400,000 mortgage on a $600,000 property has $200,000 in equity—even if they haven’t sold the house. Similarly, a professional with a defined-benefit pension has future income streams worth valuing. How to calculate net worth from salary must include: - Tangible assets (real estate, vehicles, collectibles) - Intangible assets (business ownership, intellectual property, professional licenses) - Future income potential (vested retirement accounts, deferred compensation) Excluding these components leads to an incomplete snapshot. A young entrepreneur might have a negative net worth on paper (due to business loans) but possess a scalable venture worth millions in potential.
What Holds Up to Scrutiny
The verifiable core of how to calculate net worth from salary rests on three pillars: liquid assets, liabilities, and time. Liquid assets—cash, stocks, bonds, and easily convertible investments—provide immediate financial flexibility. Liabilities, including mortgages, student loans, and credit card debt, reduce net worth. Time enters the equation through compound interest, career trajectory, and inflation’s erosion of purchasing power. The key insight is that net worth is a dynamic metric, not a static one. A 25-year-old with $10,000 in savings and $50,000 in student loans has a negative net worth—but if their career path suggests a 7% annual salary growth and they invest aggressively, their net worth could turn positive in a decade. The calculation isn’t just arithmetic; it’s a forecast. > "Net worth is the scorecard of your financial life. It doesn’t tell you if you’re happy, but it does tell you if you’re on track." — Carl Richards, The New York Times financial columnist| Common Belief | What the Evidence Says |
|---|---|
| Net worth is only for the wealthy. | Even small balances reveal financial health trends. A $5,000 net worth is better than $0 if it’s growing at 10% annually. |
| Salary determines net worth. | Spending habits, debt management, and asset allocation have a larger impact than raw income. |
| Homeownership always boosts net worth. | Only if equity exceeds mortgage debt. Renting in a high-appreciation market can outperform a leveraged property. |
Why the Confusion Persists
Financial literacy gaps perpetuate the myth that net worth is a mystery reserved for experts. Schools rarely teach personal finance beyond budgeting basics, and media often reduces wealth to celebrity net worth lists—ignoring the decades of compounding and luck behind those figures. Even financial advisors sometimes prioritize product sales over education, leaving clients to assume that higher income alone will solve their problems. The other culprit is behavioral economics. Humans are wired to prioritize immediate gratification—hence the allure of lifestyle inflation. A promotion feels like a victory until you realize the extra $20,000 went toward a bigger apartment, not investments. How to calculate net worth from salary forces a reckoning with trade-offs: Do you spend now or invest for future growth? The answer depends on risk tolerance, time horizon, and goals.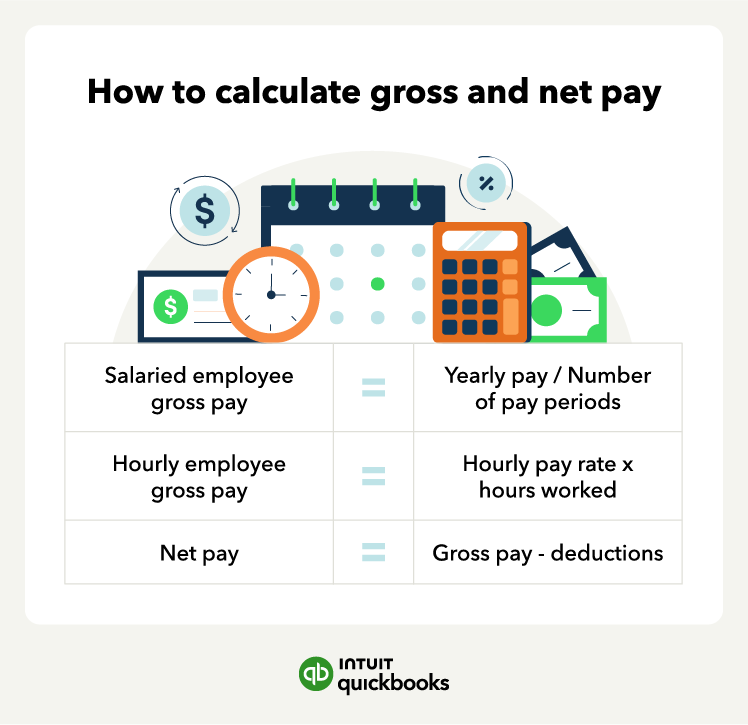
Conclusion
Understanding how to calculate net worth from salary isn’t about crunching numbers—it’s about reframing how you think about money. It’s the difference between seeing a paycheck as a one-time windfall and recognizing it as fuel for long-term wealth. The process exposes hidden opportunities: the freelancer who reinvests every bonus, the public servant who prioritizes low-cost living, or the entrepreneur who accepts lower short-term pay for equity. The takeaway? Net worth isn’t a destination but a compass. It doesn’t guarantee happiness, but it clarifies whether your financial decisions align with your priorities. Start tracking it today—not to obsess over the number, but to steer your path.Comprehensive FAQs
Q: Should I include my car in net worth calculations?
A: Yes, but with caveats. List its current market value (not what you paid) and subtract any outstanding loan balance. Cars depreciate rapidly, so their impact on net worth diminishes over time. If you’re leasing, the asset value is typically low unless it’s a high-end vehicle with appreciating resale potential.
Q: How often should I update my net worth?
A: At least annually, but quarterly reviews are ideal for active investors or those with fluctuating incomes. Automate tracking by linking accounts to a spreadsheet or financial software. The goal is to spot trends—like a sudden drop in investments or rising debt—before they become crises.
Q: Does student loan debt always hurt net worth?
A: Not if the degree leads to higher-earning opportunities. Compare the present value of future earnings against the loan balance. For example, a medical school graduate with $200,000 in debt but a $300,000 salary potential may see net worth grow over time. The key is ensuring the ROI on education exceeds the cost of borrowing.
Q: Can I have a negative net worth and still be financially healthy?
A: Yes, if the negative is temporary and tied to wealth-building strategies. A young professional with student loans but a growing retirement account and side income is in a different position than someone drowning in credit card debt with no assets. Context matters: negative net worth is a red flag only if it reflects poor financial management, not strategic investment.
Q: How do I account for future income streams like Social Security?
A: Use a present-value calculator to estimate their worth today. For Social Security, the Social Security Administration’s online tools can provide projections based on age and earnings history. Pension plans should be valued similarly—consult an actuary if the numbers are complex. The rule of thumb: if a future income stream is reliable, include a conservative estimate in your net worth.
Q: Is there a "good" net worth by age?
A: Benchmarks exist, but they’re guidelines, not rules. A common (though debated) rule is having a net worth equal to your age by 35, doubling by 45, and tripling by 55—assuming modest inflation adjustments. However, these figures vary by income level, location, and lifestyle. A 30-year-old earning $80,000 might aim for $50,000 in net worth, while a peer earning $200,000 could reasonably target $200,000 if they’re aggressive with savings and investments.
