
Breaking Down the Numbers
The FAFSA’s approach to assets isn’t about net worth in the traditional sense—it’s about liquidity and accessibility. While a family’s total assets might be substantial, the FAFSA cares only about what can reasonably be converted to cash within a year without penalty. This distinction explains why a $1 million home equity line might not factor into aid calculations, while a $50,000 savings account could trigger a $5,000 expected contribution. The formula also varies by dependency status: independent students face fewer asset protections than dependents, whose families benefit from higher exclusion thresholds. The FAFSA’s asset calculation is embedded within the SAI formula, which now uses a weighted contribution rate for different asset types. Cash, savings, and investments are assessed at a 20% rate, meaning every dollar above the asset protection allowance is counted as 20 cents toward the SAI. Retirement accounts, however, are excluded entirely—unless they’re non-IRA accounts (like a 401(k) loan) that can be tapped. Even then, the rules are strict: only the non-retirement portion of such accounts is considered. This creates a paradox where families with aggressive retirement savings might paradoxically reduce their aid eligibility if those funds are accessible.The Verified Baseline
Publicly available data confirms that the FAFSA’s asset rules are not arbitrary. The U.S. Department of Education’s Federal Student Aid Handbook outlines the exact thresholds and exclusion categories. For the 2024-25 award year, dependent students’ families receive an asset protection allowance of $100,000, while independent students get $2,000. Any assets above these limits are assessed at the 20% rate. The handbook also clarifies that primary residences are excluded from the calculation, provided the family doesn’t own additional properties. This means a couple with a $1 million home and no other real estate would see zero home equity counted toward their SAI. The FAFSA’s income protection allowance (IPA) further complicates the picture. While assets are assessed at 20%, income is treated differently: only discretionary income (after basic living expenses) is considered. The IPA for 2024-25 is set at $40,000 for a family of four, meaning income above this threshold is assessed at up to 47%. This creates a scenario where a family with high income but low liquid assets might still qualify for aid—while another with modest income but significant savings could be shut out. The interplay between income and assets is why how to calculate net worth for FAFSA often requires a two-step process: first, assess liquidity; second, reconcile it with annual earnings.What the Estimates Suggest
Industry estimates suggest that up to 60% of families misreport their assets on the FAFSA, often due to confusion over which accounts are excluded. For instance, 529 college savings plans are treated as parental assets for dependent students but as the student’s assets if the account is in their name. This means a $50,000 529 plan owned by a parent might add $10,000 to the SAI, while the same amount in a student-owned 529 could push the SAI up by $4,000 (since student assets are assessed at a 50% rate). Financial advisors specializing in FAFSA planning report that families with $300,000 to $500,000 in liquid assets often see their aid eligibility drop precipitously—even if their total net worth exceeds $1 million. Experts also note that small business owners frequently underestimate their FAFSA liability because they assume business assets are shielded. While the FAFSA excludes farm assets and small business net worth (up to $250,000 for dependent students), it does count business income—and the depreciation of business assets can sometimes trigger additional scrutiny. A family-owned LLC with $400,000 in equipment might see that value excluded, but if the business generates $150,000 in annual profit, that income will be fully assessed against the IPA. This is why how to calculate net worth for FAFSA for entrepreneurs requires separating asset value from cash flow.
Case Study: A Closer Look
Consider a hypothetical family of four: parents aged 45 and 48, with two dependent children in high school. Their financial picture includes: - $800,000 in a 401(k) and IRA (fully excluded from SAI). - $150,000 in a brokerage account (assessed at 20%). - $600,000 home equity (excluded, as it’s their primary residence). - $90,000 in annual income, with $30,000 above the IPA threshold. Under the FAFSA’s rules, only the brokerage account would factor into their SAI calculation. The $150,000 exceeds the $100,000 asset protection allowance by $50,000, which is assessed at 20%, adding $10,000 to their SAI. Their income, meanwhile, would contribute an additional $14,100 (47% of the $30,000 above the IPA), bringing their total SAI to $24,100. This would likely disqualify them from Pell Grants (which have a $7,395 maximum for 2024-25) but might still leave them eligible for subsidized loans or institutional aid. The case highlights a critical flaw in relying solely on net worth: liquidity dictates aid eligibility far more than total wealth. If the same family had their $150,000 in a non-retirement investment account tied to a 5-year restriction, the FAFSA might exclude it entirely—even though the total asset value remains unchanged. This is why how to calculate net worth for FAFSA often involves strategic asset placement rather than a passive balance-sheet review."The FAFSA doesn’t care about your net worth—it cares about your ability to pay. Families with $2 million in illiquid assets can still qualify for aid, while those with $200,000 in cash might not. The key is structuring your finances to align with the FAFSA’s arbitrary but rigid rules." — Mark Kantrowitz, Higher Education Expert and Publisher of SavingForCollege.com
| Factor | Estimated Impact on SAI |
|---|---|
| Brokerage Account ($150,000) | +$10,000 (20% of $50,000 over allowance) |
| Discretionary Income ($30,000) | +$14,100 (47% of amount above IPA) |
| Primary Residence Equity ($600,000) | $0 (fully excluded) |
| 401(k) and IRA ($800,000) | $0 (fully excluded) |
| 529 Plan ($40,000, parent-owned) | +$8,000 (20% of $40,000, as it exceeds allowance) |
What This Means Going Forward
The FAFSA’s asset rules are not static. The SAI formula has undergone significant revisions in recent years, with the 2024-25 cycle introducing new income protection allowances and adjusted asset thresholds. Families must now account for two years of tax data (rather than one) when applying, which can significantly alter their reported financial picture. This means a family’s how to calculate net worth for FAFSA in 2024 might differ drastically from their 2023 calculation—even if their actual wealth hasn’t changed. The shift also underscores the importance of proactive planning, as last-minute asset adjustments (e.g., moving funds into a 529 plan) can sometimes backfire if the FAFSA’s verification process flags inconsistencies. The rise of private student loans and institutional aid has further complicated the equation. While federal aid is determined by the SAI, many colleges and universities use the CSS Profile—a supplemental application with its own asset rules. The CSS Profile, administered by the College Board, assesses home equity, trust funds, and even parent business valuations in ways the FAFSA does not. This means a family might qualify for federal aid but be denied institutional grants due to CSS-specific asset exclusions. Navigating both systems requires a dual-track approach, where families must optimize their finances for both FAFSA and CSS Profile—a task that demands precision.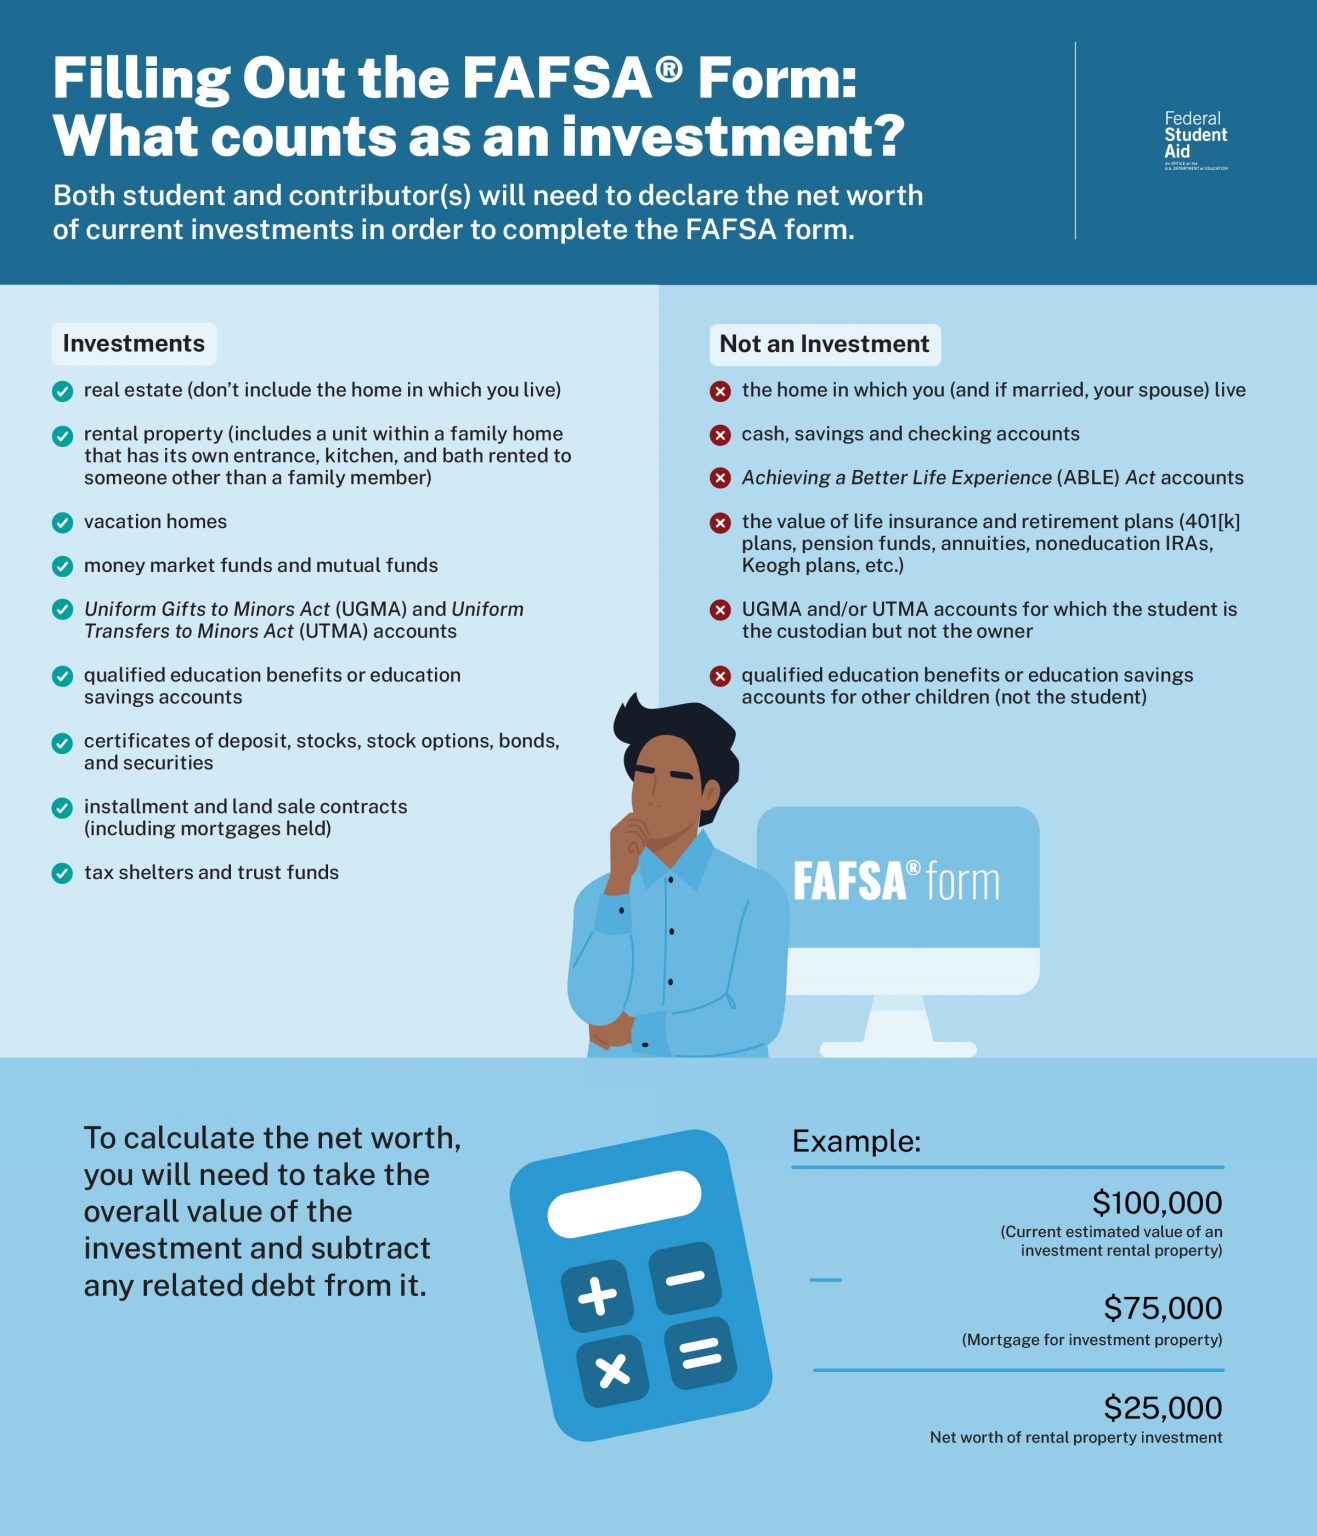
Conclusion
The FAFSA’s net worth calculation is not about wealth—it’s about liquidity and compliance. Families often assume that how to calculate net worth for FAFSA is a straightforward exercise, but the reality is far more intricate. The system prioritizes accessible assets over total holdings, meaning a family with a $5 million portfolio might still qualify for aid if most of it is locked in retirement accounts or illiquid investments. Conversely, a family with $200,000 in cash could see their aid eligibility evaporate overnight. The lesson is clear: strategic asset structuring can mean the difference between thousands in aid and thousands in out-of-pocket costs. As college costs continue to rise, understanding how to calculate net worth for FAFSA will remain a non-negotiable skill for families planning higher education. The process demands annual review, tax-data awareness, and institutional aid research—not just a one-time balance-sheet check. Those who treat the FAFSA as a static form rather than a dynamic financial tool risk leaving money on the table. The good news? With the right approach, even families with modest liquidity can maximize their aid—and those with high net worth can still secure significant assistance by leveraging the FAFSA’s asset protections.Comprehensive FAQs
Q: Does the FAFSA count my business assets toward net worth?
The FAFSA excludes small business net worth (up to $250,000 for dependent students) but includes business income in the SAI calculation. Farm assets are also excluded, but only if they meet specific IRS definitions. If your business is structured as an LLC or corporation, consult a tax advisor to ensure compliance—misclassifying assets can lead to aid denials during verification.
Q: Are 529 plans fully excluded from the FAFSA calculation?
No. For dependent students, 529 plans owned by parents are treated as parental assets and assessed at 20% (above the $100,000 allowance). If the 529 is in the student’s name, it’s assessed at 50%. Prepaid tuition plans (another 529 type) are fully excluded from both parent and student asset calculations. Always check the account ownership when estimating your SAI.
Q: How does home equity affect FAFSA eligibility?
The FAFSA excludes the value of your primary residence from asset calculations, regardless of equity. However, if you own additional properties (e.g., vacation homes, rental properties), their full value is counted as an asset. Home equity lines of credit (HELOCs) are not excluded—only the underlying property value is shielded. This is why families with multiple properties often see higher SAI contributions.
Q: What happens if I underreport assets on the FAFSA?
Underreporting assets is fraud under federal law and can result in aid denials, repayment demands, or criminal charges. The FAFSA’s verification process cross-references your application with IRS tax returns, bank statements, and asset documentation. If discrepancies are found, you may owe back all aid received plus penalties. Always report accurately—even if it means paying more upfront.
Q: Can I reduce my SAI by moving assets into retirement accounts?
Yes, but with strict limitations. The FAFSA excludes IRAs, 401(k)s, and other qualified retirement accounts—but only if they’re non-pension, non-profit-sharing plans. Moving funds into a Roth IRA (for those under income limits) or a 401(k) can lower your taxable income and shield assets. However, early withdrawals or loans from retirement accounts may trigger asset assessments. Consult a financial advisor before making large transfers.
Q: Does the FAFSA consider student loans as assets?
No. Federal and private student loans are not counted as assets on the FAFSA. However, the debt-to-income ratio can indirectly affect aid eligibility if you’re applying for institutional aid (via the CSS Profile). Some colleges may also consider total debt burden when awarding need-based grants, so while student loans don’t hurt your SAI, they can influence other aid decisions.
Q: How often should I recalculate my net worth for FAFSA purposes?
You should reassess annually before submitting the FAFSA, as asset values, income, and household size can shift eligibility. Major life events—such as divorce, inheritance, or job changes—should trigger an immediate review. The FAFSA’s two-year tax data requirement means fluctuations in income or assets from the prior year can also alter your SAI. Use the FAFSA’s online calculator (or a CSS Profile tool) to estimate changes before applying.
Q: What’s the best way to minimize my SAI without lying?
The most ethical and effective strategies include:
- Maximizing retirement contributions (401(k), IRA, HSA).
- Shifting assets into 529 plans (parent-owned for dependent students).
- Using home equity (primary residence only) to reduce liquid assets.
- Structuring business assets to meet FAFSA exclusion rules.
- Applying for state and institutional aid, which often have different formulas.
