
The Complete Overview of How to Calculate Home Value in Net Worth
Net worth is the snapshot of what you own minus what you owe. For most people, their home is the single largest asset—and often the largest liability—on that balance sheet. The challenge lies in translating a property’s market value into a net worth component that reflects its true financial impact. Unlike stocks or bonds, real estate doesn’t generate regular income (unless rented), and its value isn’t liquid. This illiquidity forces homeowners to adopt a conservative approach: how to calculate home value in net worth must account for the time and cost of selling, not just the asking price.
The process begins with a current market appraisal, but even this is fraught with subjectivity. Online estimators, while convenient, often overstate values in hot markets or understate them in stagnant ones. A professional appraisal or comparative market analysis (CMA) from a realtor provides a more accurate benchmark—but these come with costs and potential biases. Then comes the mortgage balance, which isn’t static. Refinancing, interest rate changes, or even a single missed payment can alter the liability side of the equation. The gap between the appraised value and the remaining debt is your home equity, but equity alone doesn’t tell the full story. You must also subtract any pending repairs, unpaid property taxes, or homeowners association fees that haven’t yet been factored into the sale price.
The final step—often overlooked—is adjusting for opportunity cost. If you’re leveraging your home to invest elsewhere (e.g., a rental property or stocks), the potential returns on those alternatives should theoretically offset the home’s value in your net worth. Conversely, if the home is your primary residence and you’re not generating rental income, its value in net worth calculations should reflect its role as a non-income-producing asset. This distinction is critical for retirees or those near retirement, where liquidity and risk tolerance shift dramatically.
Historical Background and Evolution
The concept of net worth has existed since ancient civilizations, but the modern framework—where real estate plays a pivotal role—emerged with the rise of mortgage lending in the 19th century. Before then, homeownership was often tied to land ownership, and wealth was measured in acres rather than equity. The Industrial Revolution changed this, as urbanization and wage labor made homeownership a marker of stability. By the early 20th century, mortgages became standardized, and the idea of home equity as a financial tool took root. The Great Depression exposed the risks of overleveraging, leading to the creation of the Federal Housing Administration (FHA) in the U.S. and similar institutions elsewhere, which codified how mortgages—and by extension, home values—would be calculated in net worth.
The 1980s and 1990s saw another shift, as financial deregulation and the rise of subprime lending turned homes into speculative assets. The 2008 financial crisis laid bare the dangers of treating real estate as a liquid, high-return investment. Post-crisis, regulators and financial advisors emphasized how to calculate home value in net worth with greater caution, stressing the importance of debt-to-equity ratios and stress-testing scenarios. Today, the conversation has evolved further with the gig economy and remote work, where home values are no longer tied to a single location. A freelancer in London might calculate their net worth differently than a corporate employee in Manchester, given the varying costs of living and property markets. This decentralization has made the process of assessing home value in net worth more complex and personalized than ever.
Core Mechanisms: How It Works
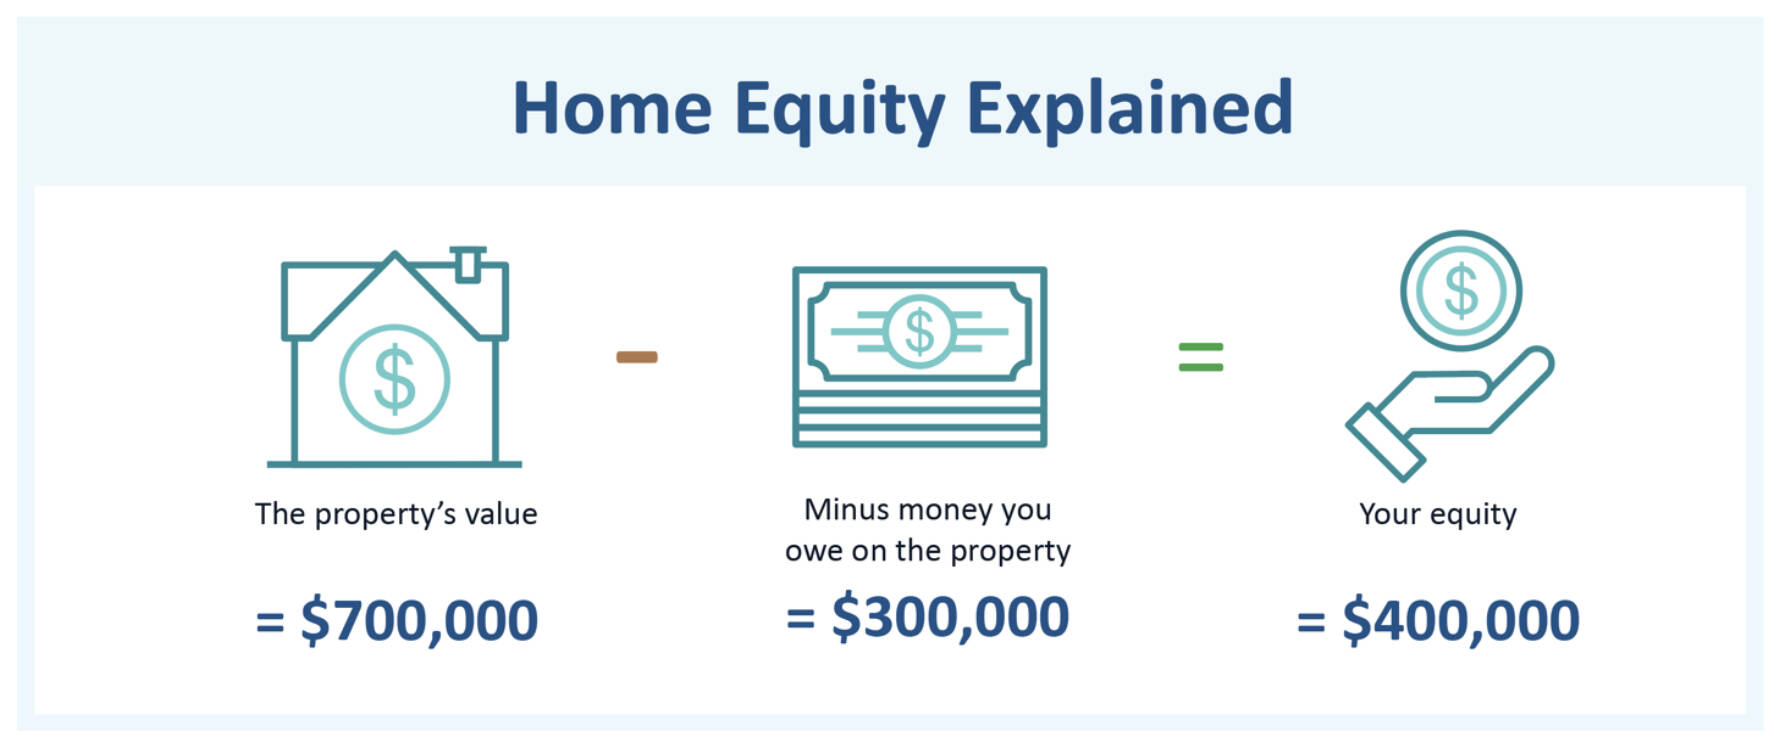
The mechanics of how to calculate home value in net worth boil down to a simple formula, but the execution is where errors creep in. Start with the current market value (appraised or estimated). Subtract all outstanding liabilities tied to the property: the mortgage balance, any second mortgages or home equity lines of credit (HELOCs), unpaid property taxes, and pending repair costs. The result is your net home equity. However, this figure is static—it doesn’t account for the time value of money. If you’re planning to sell in five years, you must factor in transaction costs (agent fees, legal expenses) and potential market fluctuations. A home worth £400,000 today might only net £350,000 after fees, even if the market holds steady.
The second layer involves leverage and opportunity cost. If you’ve taken out a mortgage to finance the home, the interest payments reduce your net worth annually. Conversely, if you’ve paid down the mortgage significantly, your equity increases—but so does the risk of not having liquid assets in case of an emergency. Financial planners often recommend keeping 3–6 months’ living expenses in liquid savings, which can conflict with the desire to maximize home equity. The tension between home value in net worth and liquidity is a recurring theme in financial planning, especially for older homeowners who may rely on property sales for retirement income.
Key Benefits and Crucial Impact
Including your home in net worth calculations provides a clearer picture of your financial health, but it’s not without risks. The primary benefit is clarity in financial planning. Knowing your true home equity helps in decisions like refinancing, downsizing, or taking out a HELOC. For example, a homeowner with £200,000 in equity might consider tapping into it for a renovation—but only if they can afford the new mortgage payments. Without accurate calculations, they risk overleveraging. The impact extends to creditworthiness; lenders often look at home equity as collateral, and a miscalculated net worth can lead to loan denials or higher interest rates.
Yet the benefits come with caveats. Overestimating home value can lead to overconfidence in wealth, while underestimating it may prompt unnecessary belt-tightening. The emotional attachment to a home further complicates the math. Many homeowners refuse to sell even when the market dips, fearing they’ll lose money—only to discover their net worth would have grown faster if they’d reinvested the proceeds elsewhere. This behavioral bias is why financial advisors stress that how to calculate home value in net worth should be a dynamic, not static, exercise.
> "A home is more than an asset; it’s a liability wrapped in hope. The mistake isn’t in valuing it—it’s in treating that value as fixed."
Major Advantages
- Accurate wealth tracking: Provides a realistic snapshot of liquid and illiquid assets, helping in retirement planning or inheritance strategies.
- Leverage opportunities: Identifies how much equity can be accessed for investments, education, or emergencies without overburdening finances.
- Tax planning: Helps in structuring sales or refinancing to minimize capital gains or stamp duty liabilities.
- Risk assessment: Reveals exposure to market downturns or high-interest debt, allowing for hedging strategies.
Comparative Analysis
| Factor | Traditional Net Worth Calculation | Adjusted for Real Estate Nuances |
|---|---|---|
| Home Value | Market appraisal (static) | Market value minus liabilities, transaction costs, and opportunity cost |
| Liquidity | Assumed fully liquid | Adjusts for sale timeline (3–6 months to liquidate) |
| Debt Impact | Mortgage balance only | Includes interest rates, refinancing costs, and tax implications |
Future Trends and Innovations
The way we calculate home value in net worth is evolving with technology and shifting economic models. Blockchain and smart contracts are already enabling fractional home ownership, where investors can buy shares of a property without full ownership. This could change how home equity is recorded in net worth—no longer as a single asset but as a diversified portfolio. Meanwhile, AI-driven valuation tools are making appraisals more dynamic, adjusting for real-time market data and personalization factors like energy efficiency or smart home upgrades.
Another trend is the rise of alternative housing models, such as co-living spaces and modular homes, which don’t fit traditional valuation frameworks. As remote work reduces the need for urban living, homeowners in secondary markets may see their property values fluctuate based on transient demand. The future of how to calculate home value in net worth will likely involve modular, scenario-based models that account for lifestyle changes, not just market trends. For now, the core principle remains: treat your home as both an asset and a liability, and recalculate its value as often as your financial goals shift.
Conclusion
Understanding how to calculate home value in net worth isn’t about crunching numbers—it’s about aligning your property’s role with your broader financial strategy. A home can be a store of wealth, a source of leverage, or a drag on liquidity, depending on how you manage it. The key is to avoid treating it as a static figure. Markets change, mortgages evolve, and personal circumstances shift. What worked in 2020 might not in 2025, especially with rising interest rates and economic uncertainty. The best approach is to reassess home value in net worth annually, or whenever major life events occur—divorce, retirement, or a career change.
For most people, their home is the largest component of net worth, but it’s also the most misunderstood. The difference between a homeowner who feels wealthy and one who’s actually prepared for the future often comes down to this calculation. Don’t let emotional attachment cloud the math. Whether you’re planning to sell, refinance, or simply track your progress, how to calculate home value in net worth must be precise, flexible, and forward-looking.
Comprehensive FAQs
#### Q: Should I include my primary residence in net worth calculations?
A: Yes, but with adjustments. List the current market value minus all outstanding liabilities (mortgage, taxes, repairs). However, if you’re not planning to sell soon, consider the opportunity cost—what you could earn by investing that equity elsewhere. For retirees, liquidity often trumps raw equity in net worth assessments.
####Q: How often should I update my home’s value in net worth?
A: At least annually, or whenever major changes occur: refinancing, renovations, or shifts in the local market. Online tools can give rough estimates, but a professional appraisal every 3–5 years is ideal for accuracy. If you’re near retirement, quarterly checks may be prudent.
####Q: Does refinancing affect my home’s net worth?
A: Yes, but not always in the way you’d expect. Lowering your interest rate can reduce monthly payments, freeing up cash flow—but it may extend the mortgage term, increasing total interest paid. If you refinance to access equity (e.g., for a HELOC), your net worth temporarily drops due to the new debt, even if the home’s market value stays the same.
####Q: What if my home’s value drops? Should I still include it?
A: Absolutely, but adjust for realism. A declining market doesn’t mean your home is worthless—it means your equity has shrunk. The key is to avoid overestimating recovery potential. If you’re relying on home equity for retirement, a conservative valuation (e.g., 10–15% below current appraisals) may be safer than assuming a rebound.
####Q: Can I use home equity for investments without hurting my net worth?
A: It depends on the strategy. Taking a HELOC or cash-out refinance to invest in stocks or a business can work if the expected returns exceed the interest rate on the loan. However, if the investment fails, your net worth drops by both the lost capital and the new debt. Always treat home equity as collateral with a risk premium—never as free money.
