
The Complete Overview of Corporate Tangible Net Worth in Excel
The corporate tangible net worth formula in Excel serves as a financial X-ray, exposing a company’s asset-liability reality after stripping away non-physical valuations. At its core, it subtracts total liabilities from tangible assets—defined here as cash, inventory, property, plant, equipment (net of depreciation), and other physical holdings—excluding intangibles like patents, trademarks, or goodwill. This approach mirrors the "breakup value" concept used by distressed asset investors, who care less about brand equity and more about what can be sold for hard cash. The formula’s power lies in its ability to highlight discrepancies between book value and economic substance, especially in industries where intangibles dominate (e.g., tech or media). Excel becomes the battleground for accuracy here. A single error—such as overlooking deferred tax liabilities or misclassifying lease assets—can distort the tangible net worth by 20% or more. The process begins with raw balance sheet data, but the real work happens in the adjustments: reclassifying operating leases as capital leases, normalizing one-time charges, or recalculating depreciation using accelerated methods. For public companies, this often means cross-referencing footnotes to uncover embedded liabilities. The result? A metric that aligns closer with a company’s liquidation potential than its market perception.Historical Background and Evolution
The concept of tangible net worth predates modern accounting standards, emerging in the 19th century as industrial firms sought to quantify their physical capital. Early railroad companies, for instance, tracked "net plant" to assess collateral for bond issuances—a precursor to today’s tangible net worth calculations. The shift toward intangible-heavy valuations in the late 20th century, driven by mergers and acquisitions, created a gap between book value and economic reality. By the 1990s, private equity firms began demanding tangible net worth analyses to justify leverage ratios, particularly in buyouts where debt was secured against hard assets. Excel’s role in this evolution became critical in the 2000s, as financial modeling software democratized complex calculations. Prior to this, tangible net worth was computed manually, relying on audited financials and spreadsheets with limited automation. The rise of corporate tangible net worth formulas in Excel coincided with the dot-com bubble’s collapse, when investors realized that high market caps could mask negative tangible equity. Today, the formula is a staple in due diligence for everything from leveraged buyouts to bankruptcy proceedings, where creditors prioritize claims against liquidatable assets.Core Mechanisms: How It Works
The corporate tangible net worth formula in Excel follows a three-step framework: identification, adjustment, and calculation. First, tangible assets are isolated from the balance sheet. This includes: - Current assets: Cash, accounts receivable (net of bad debt reserves), and inventory (adjusted for obsolescence). - Non-current assets: Property, plant, and equipment (PPE) net of accumulated depreciation; land (if held for liquidation); and other physical holdings like vehicles or equipment. Excluded are intangibles (goodwill, patents, trademarks), deferred charges, and prepaid expenses. The second phase—adjustments—is where Excel’s flexibility becomes a double-edged sword. Common tweaks include: - Normalizing depreciation: Switching from straight-line to accelerated methods to reflect economic useful life. - Reclassifying leases: Converting operating leases to capital leases (per ASC 842) to capture off-balance-sheet liabilities. - Adding back one-time items: Restructuring charges or asset write-downs that distort recurring value. - Adjusting for embedded liabilities: Contingent liabilities (e.g., environmental remediation) or unfunded pension obligations. The final step is the calculation itself: ``` Tangible Net Worth = (Tangible Assets) – (Total Liabilities) ``` Where Total Liabilities includes both current and long-term obligations, minus any non-recourse debt (e.g., mortgages secured by specific assets). The result is a figure that represents the company’s value if it were liquidated tomorrow—minus intangibles.Key Benefits and Crucial Impact
Few financial metrics offer the clarity of the corporate tangible net worth formula in Excel when assessing a company’s true economic position. Unlike earnings per share, which can be manipulated through accounting policies, tangible net worth reflects the cold hard reality of what a business owns minus what it owes. This matters most in scenarios where market perceptions diverge sharply from asset reality—such as a struggling retailer with high goodwill but collapsing inventory turnover, or a tech firm with a soaring stock price but negative tangible equity. For creditors, this metric becomes the primary lens through which to evaluate collateral quality and recovery potential in a default. The formula’s impact extends beyond distressed situations. Private equity firms use it to justify leverage multiples, while activist investors deploy it to argue for breakups of overvalued conglomerates. Even public companies monitor their tangible net worth to signal financial health to investors. The metric’s transparency also forces management to confront hard questions: Are intangibles overstated? Are liabilities underreported? The answers often reshape strategy, from asset sales to cost-cutting initiatives."Tangible net worth is the ultimate stress test for a balance sheet. If a company’s book value is propped up by goodwill and the market doesn’t believe in its intangibles, the tangible figure will expose that truth—often before the market does." — Senior Director, Financial Restructuring at a Top 5 Investment Bank
Major Advantages
- Collateral clarity: Lenders use tangible net worth to assess loan-to-value ratios, reducing risk in secured financing.
- Distress indicators: Negative tangible net worth often precedes bankruptcy filings, serving as an early warning system.
- M&A due diligence: Buyers compare tangible net worth to purchase price to identify overpayments for intangibles.
- Regulatory compliance: Some jurisdictions require tangible net worth disclosures for solvency assessments.

Comparative Analysis
| Metric | Corporate Tangible Net Worth | Book Value per Share | |--------------------------|-----------------------------------------------------------|--------------------------------------------------| | Focus | Physical assets minus liabilities | Total equity (including intangibles) | | Use Case | Collateral valuation, distress analysis | General financial health, dividend capacity | | Market Sensitivity | Low (tied to assets) | High (affected by intangibles and market mood) | | Adjustment Needs | High (requires lease, depreciation, and liability tweaks)| Low (uses audited figures) |Future Trends and Innovations
The corporate tangible net worth formula in Excel is evolving alongside changes in accounting standards and corporate structures. The adoption of ASC 842 (lease accounting) and IFRS 16 has forced companies to bring operating leases on-balance-sheet, directly impacting tangible net worth calculations. As a result, Excel models now require dynamic lease amortization schedules, adding layers of complexity. Meanwhile, the rise of asset-light business models—where companies outsource PPE ownership (e.g., cloud computing, co-working spaces)—is shrinking tangible asset bases, making the metric less relevant for some sectors. Automation may further reshape the process. Tools like Alteryx or Power BI are beginning to integrate tangible net worth calculations with real-time data feeds, reducing manual errors. However, the human element remains critical: interpreting adjustments (e.g., whether to capitalize R&D as an asset) still demands judgment. The next frontier may lie in AI-assisted adjustments, where machine learning flags anomalies in depreciation patterns or lease terms—but for now, the corporate tangible net worth formula in Excel remains a manual, high-stakes discipline.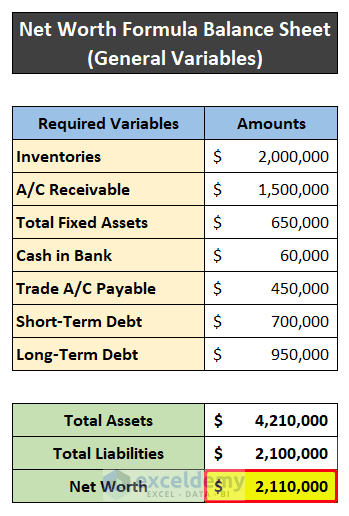
Conclusion
The corporate tangible net worth formula in Excel is not just a calculation—it’s a financial philosophy that prioritizes substance over perception. In an era where goodwill can exceed tangible assets by orders of magnitude, this metric offers a rare unvarnished view of a company’s economic foundation. Its limitations are clear: it ignores growth potential tied to intangibles and assumes liquidation value equals fair market value. Yet its strength lies in its brutality—it forces stakeholders to confront the question every creditor and investor must ask: What’s left if everything else fails? For those who master the formula, the rewards are tangible. Whether negotiating a loan covenant, structuring a buyout, or evaluating a distressed asset, the ability to compute and interpret tangible net worth separates the informed from the speculative. The tools exist—Excel, audited financials, and a disciplined approach to adjustments—but the skill lies in knowing when to trust the numbers and when to question them.Comprehensive FAQs
Q: How do I handle goodwill in the corporate tangible net worth formula in Excel?
A: Goodwill is excluded entirely from tangible assets. If the balance sheet includes goodwill under "intangible assets," subtract it from total assets before calculating tangible net worth. Some analysts also subtract other intangibles like patents or trademarks, depending on their liquidation potential.
Q: Should I adjust for deferred tax liabilities?
A: Yes. Deferred tax liabilities are a real obligation and should be included in total liabilities. In Excel, locate them under "non-current liabilities" in the balance sheet and add them to the liabilities sum. If the company has deferred tax assets, these may offset liabilities—but only if they’re realizable.
Q: Can the corporate tangible net worth formula in Excel be used for startups?
A: With caveats. Startups often have negligible tangible assets (e.g., a software firm with no PPE) and high intangibles (IP, customer lists). In such cases, tangible net worth may be negative or meaningless. Instead, focus on cash burn rates or milestone-based valuations. The formula works best for asset-heavy businesses.
Q: How often should tangible net worth be recalculated?
A: At minimum, quarterly, especially if the company has: - Significant capital expenditures (affecting PPE). - Major lease transactions (post-ASC 842). - Changes in inventory levels or receivables (current assets). For public companies, align recalculations with earnings releases. Private firms may need monthly updates during high-growth or distress phases.
Q: What’s the difference between tangible net worth and shareholders’ equity?
A: Shareholders’ equity includes all assets minus liabilities, while tangible net worth excludes intangibles. The gap between the two reveals how much of a company’s value is tied to non-physical assets. For example, a firm with $1B in equity but $800M in goodwill has only $200M in tangible net worth.
Q: How do operating leases affect the formula?
A: Under ASC 842, operating leases must be capitalized, meaning: 1. The present value of lease payments becomes a liability (added to total liabilities). 2. The right-of-use asset is recorded under tangible assets (if the leased asset is physical, like equipment). This often reduces tangible net worth because the new liability outweighs the asset’s book value. In Excel, use the lease amortization schedule to adjust both sides of the balance sheet.
Q: Is tangible net worth useful for valuing tech companies?
A: Limited, but not irrelevant. Tech firms often have negative tangible net worth due to high intangibles (e.g., R&D, brand). However, it can still serve as: - A floor valuation (what assets could be sold for). - A red flag if intangibles are overstated (e.g., inflated goodwill). For tech, pair tangible net worth with metrics like cash burn multiple or revenue per employee for a fuller picture.
