The Short Answers
- A net worth portfolio is a curated collection of assets and liabilities optimized for growth, protection, and liquidity—beyond a simple balance sheet.
- Diversification isn’t just about stocks vs. bonds; it’s about balancing liquidity (cash, ETFs), growth (private equity, real estate), and preservation (gold, fine art).
- Tax-efficient structuring—like holding companies or trusts—can legally reduce liabilities by 20–40% in high-tax jurisdictions.
- Liquidity planning is critical: ultra-high-net-worth individuals often allocate 10–30% of their portfolio to immediately accessible cash equivalents.
- Rebalancing isn’t annual—it’s triggered by life events (inheritance, career shifts) or market conditions (e.g., post-2008, many portfolios shifted 15–20% toward defensive assets).
- Your net worth portfolio should evolve with your risk tolerance; a 30-year-old tech founder and a 65-year-old retiree may both have £10m portfolios but with radically different allocations.
Deep Dive: The Full Picture
A net worth portfolio isn’t static. It’s a living document that reflects not just market performance but personal evolution—career shifts, family dynamics, and even geopolitical exposure. The most sophisticated portfolios treat assets as tools: a London property might serve as collateral for a business loan, while a Swiss bank account acts as a hedge against currency volatility. The goal isn’t just accumulation; it’s functional wealth—assets that work for you, not just against inflation. The psychological dimension is often overlooked. A portfolio worth £20 million can feel precarious if 60% is tied to a single venture-backed startup, while a £5 million portfolio with diversified income streams (dividends, rental yields, private credit) may offer greater peace of mind. The net worth number alone tells you nothing about sleep quality.The Context You Need
Historically, net worth portfolios were the domain of the ultra-wealthy—private bankers structuring trusts for dynastic wealth. Today, digital platforms have democratized access, but the core principles remain unchanged: asset correlation risk (e.g., holding too much UK real estate when commercial property crashes), jurisdictional arbitrage (optimizing for tax treaties), and generational transfer (ensuring heirs aren’t burdened with capital gains taxes). The rise of alternative assets—from wine investments to digital collectibles—has further complicated the landscape. A portfolio that once relied on 60% equities and 30% bonds now might include 10% in non-fungible assets (for their appreciation potential) and 5% in royalty streams (e.g., music publishing rights). The challenge? Valuation. Illiquid assets require professional appraisals, adding friction to liquidity planning.The Mechanics
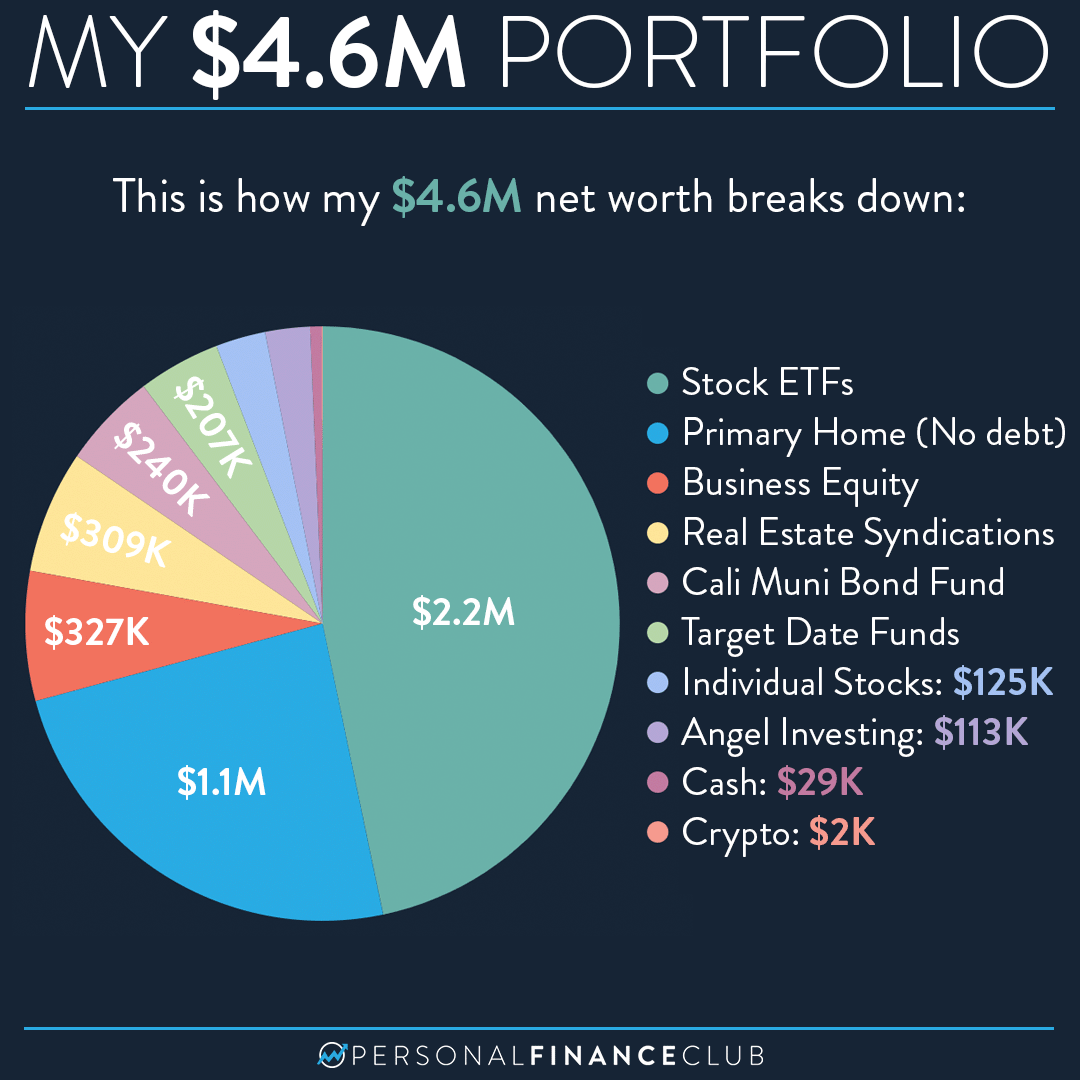
At its core, a net worth portfolio is a risk-adjusted growth engine. The allocation typically follows these tiers: 1. Core Growth (50–70%): Public markets (ETFs, individual stocks), private equity, venture capital. 2. Income Generation (20–30%): Dividend stocks, rental properties, corporate bonds, private credit. 3. Preservation (10–20%): Gold, fine art, rare collectibles, cash equivalents. 4. Leverage (0–15%): Margin debt, property loans, or structured notes (high risk, high reward). Tax efficiency isn’t an afterthought—it’s a primary driver. In the UK, for example, pension contributions (up to £60,000/year) reduce taxable income, while business relief can slash inheritance tax on assets held for two years. Offshore structures (e.g., Cayman trusts) are controversial but legally valid in many cases, offering asset protection from lawsuits or creditors.Details That Change the Picture
The gap between a well-structured net worth portfolio and a haphazard collection of assets often comes down to three overlooked factors: 1. Behavioral Leaks: Emotional decisions—like holding onto a losing stock or overconcentrating in a founder’s company—can erode wealth faster than market downturns. 2. Jurisdictional Friction: Moving assets between countries triggers capital gains taxes, currency conversion costs, and legal hurdles. A portfolio split across the UK, Singapore, and the UAE requires cross-border tax planning. 3. Liquidity Mismatches: Illiquid assets (e.g., a vineyard) can’t be sold quickly in a crisis. The best portfolios maintain a 3–6 month cash buffer in easily accessible accounts."A net worth portfolio isn’t about the numbers on paper—it’s about the options those numbers unlock. Can you retire at 45? Send your kids to Ivy League schools without debt? Weather a recession without selling at a loss? That’s the real measure of success." — James Rickards, The New Case for Gold
| Asset Class | Typical Allocation Range (High-Net-Worth) |
|---|---|
| Public Equities (ETFs/Stocks) | 30–50% |
| Private Equity/Venture Capital | 10–25% |
| Real Estate (Residential/Commercial) | 15–30% |
| Cash & Equivalents (High-Yield Savings, Money Market) | 5–15% |
| Alternatives (Art, Wine, Royalties, Crypto) | 5–10% |
Conclusion
The most resilient net worth portfolios aren’t those with the highest valuations but those built with intentionality. A £10 million portfolio concentrated in a single sector is riskier than a £5 million one with global diversification. The key isn’t chasing returns—it’s controlling risk while allowing growth. For most individuals, the process begins with a net worth audit: cataloging all assets (including non-financial ones like intellectual property) and liabilities, then stress-testing the portfolio against scenarios like a 20% market drop or a 50% drop in rental income. The goal isn’t perfection—it’s adaptability.Comprehensive FAQs
Q: How often should I review my net worth portfolio?
Quarterly for active traders, annually for long-term investors—but trigger events (divorce, inheritance, career change) demand immediate reviews. Many ultra-high-net-worth individuals conduct deep dives every 3–5 years with their advisors.
Q: Can I include non-financial assets (e.g., a restaurant business) in my net worth portfolio?
Absolutely. A restaurant, patent, or professional practice can be valued (via earnings multiples or comparable sales) and included. The challenge is liquidity—these assets may not convert to cash quickly, so they require careful integration into the broader portfolio.
Q: How do I protect my net worth portfolio from lawsuits or creditors?
Structures like asset protection trusts (in jurisdictions like the Cook Islands or Nevis) or limited liability companies (LLCs) can shield wealth from lawsuits. However, fraudulent transfer laws mean these must be set up before legal exposure arises.
Q: Should I hold cash in my net worth portfolio?
Yes, but strategically. High-net-worth individuals often keep 10–30% in liquid assets (high-yield savings, short-term bonds) for opportunities or emergencies. The rest is deployed in growth-oriented assets, with rebalancing to maintain the target allocation.
Q: How do I account for inflation in my net worth portfolio?
Inflation erodes purchasing power, so portfolios must include real return assets: TIPS (Treasury Inflation-Protected Securities), commodities (gold, silver), and inflation-linked real estate (e.g., properties in high-demand markets). Historically, diversified portfolios have maintained ~3–4% real returns over long periods.
Q: What’s the biggest mistake people make with their net worth portfolio?
Overconcentration—whether in a single stock, property, or sector. The 2008 financial crisis revealed how a 40% allocation to financials could wipe out decades of wealth. Diversification isn’t just a strategy; it’s insurance against black swan events.
