
7 Things Worth Knowing About Investing in Google Stock
The most overlooked aspects of holding Google stock aren’t in the headlines—they’re in the footnotes of earnings calls and the fine print of regulatory filings. Here’s what separates informed investors from those who chase ticker moves without context.1. Google’s Advertising Duopoly Is Under Siege—But Not Broken
Google and Facebook (now Meta) control roughly 90% of US digital ad spend, a duopoly that has insulated Google from pricing wars. Yet this dominance has made it a prime target for antitrust enforcers. The EU’s Digital Markets Act (DMA) could force Google to allow third-party ad tech to compete directly with its own systems—something it currently blocks to protect margins. Investing in Google stock now means weighing whether these changes will erode its 30%+ operating margins or force it into a less profitable but more compliant model. The risk isn’t immediate collapse; it’s the slow erosion of pricing power in ads, which still account for ~90% of free cash flow. The bigger question is whether Google can pivot ad revenue into higher-margin areas like AI-driven creative tools or programmatic audio ads. Early signs suggest it’s hedging: Google’s AI Overviews (search results powered by generative AI) could eventually cut ad impressions by 20% or more, according to some estimates—yet it’s also testing AI-generated ad copy. The duopoly isn’t dead, but it’s no longer a fortress.2. Google Cloud’s Growth Story Isn’t Just About AWS
Google Cloud has been the sleeper hit of buying Google stock over the past five years, growing revenue at a ~30% CAGR while AWS and Azure dominate. Yet its path to profitability is nonlinear. In 2023, Google Cloud’s gross margins hovered around 20%, far below AWS’s 30%+. The company has repeatedly pushed back its profitability timeline, now targeting 2025 or later. For investors, this means two scenarios: either Google Cloud becomes a cash cow that offsets ad slowdowns, or it remains a high-growth but perpetually unprofitable segment—like a tech version of a subscription box service. What’s often missed is that Google Cloud’s strength lies in niche adjacencies: AI/ML tools (TensorFlow, Vertex AI), Kubernetes (Anthos), and data analytics (BigQuery). Unlike AWS, which is a generalist platform, Google Cloud’s bet is on vertical specialization—think healthcare, financial services, and government contracts where compliance is king. If this strategy pays off, Cloud could become a $100B+ business by 2030, according to some bullish analysts. The catch? It requires Google to spend aggressively on R&D and acquisitions (like its $6.5B purchase of cybersecurity firm Mandiant) without immediate returns.3. AI Isn’t Just a Buzzword—It’s Redefining Google’s Earnings
When Google rebranded to Alphabet in 2015, it separated its "Other Bets" (like Waymo, Loon) from core operations. Today, AI is the new "Other Bet"—but with far higher stakes. Google’s AI investments span three layers: 1. Infrastructure (TPUs, data centers optimized for AI training). 2. Tools (Vertex AI, TensorFlow, Gemini). 3. Applications (AI-powered search, ads, and YouTube recommendations). The risk? Google’s AI playbook is costly and unproven at scale. Training large language models burns cash, and Google has no clear path to monetization beyond enterprise sales and cloud usage. Unlike Microsoft, which bundles AI into Office 365, Google’s AI revenue streams are fragmented. Investing in Google stock with an AI thesis means betting that Google can turn its R&D into recurring revenue—something it’s struggled to do with past moonshots (e.g., Google Glass). > "AI isn’t a product; it’s a platform. The question isn’t whether Google will succeed, but whether it can monetize success before the next wave arrives." > — Sundar Pichai, CEO of Alphabet (2023 earnings call)4. Hardware Is a Distraction—But Not a Loser
Google’s foray into hardware—Pixel phones, Nest devices, and Chromebooks—has long been a money-loser. Yet it’s not a total write-off. Pixel phones, for instance, subsidize Google’s services (YouTube, Google Photos, Play Store), creating a virtuous cycle where hardware sales drive software usage. The real play isn’t margins; it’s data and ecosystem lock-in. A Pixel user is 3x more likely to use Google Assistant than an iPhone user, according to internal data. For long-term holders of Google stock, hardware acts as a loss leader—a necessary evil to deepen user engagement. That said, Google’s hardware ambitions are constrained by scale. Apple and Samsung dwarf it in phone sales, and Nest’s smart home dominance is threatened by Amazon’s Alexa ecosystem. The key metric to watch isn’t hardware revenue (which is <5% of total) but how it influences Google’s other businesses. If Pixel’s AI features (like on-device Gemini) drive more cloud usage, the trade-off makes sense. If not, it’s a drain.5. International Growth Is Google’s Wildcard
The US and Europe account for ~70% of Google’s revenue, but emerging markets—India, Southeast Asia, Latin America—are the fastest-growing segments. In India alone, Google’s search and YouTube usage is growing at 25%+ annually, and its payments arm (Google Pay) is challenging PayPal and local players. The challenge? Regulation and competition. India’s data localization laws force Google to store user data locally, increasing costs. In Brazil, Meta’s WhatsApp dominates messaging, limiting Google’s ad reach. Investing in Google stock with an international focus means betting that Google can navigate local partnerships (like its deal with Jio in India) without ceding too much control. The payoff? A $50B+ revenue stream by 2030 from non-US markets, per some estimates. The risk? Getting outmaneuvered by TikTok (ByteDance) or local champions like Baidu in China.6. Dividends Are a Red Herring—But Share Buybacks Aren’t
Google doesn’t pay dividends, which frustrates income investors. But its share repurchase program—where it buys back stock to reduce shares outstanding—has been a far more effective way to return cash to shareholders. Since 2015, Google has spent over $100B on buybacks, which boosts earnings per share (EPS) even if revenue stagnates. For long-term holders, this is a stealth tax cut: buybacks reduce the number of shares, making each remaining share more valuable. The catch? Buybacks can distort valuation. If Google repurchases shares at inflated prices (like during the 2021 tech bubble), it destroys value. Analysts recommend monitoring the buyback-to-free-cash-flow ratio—ideally, it should stay below 50% to avoid overpaying.7. The Biggest Risk Isn’t Competition—It’s Google Itself
Google’s greatest threat isn’t Microsoft or Amazon—it’s its own management. History shows that Alphabet’s leadership has struggled with execution in non-core areas: - Waymo (self-driving cars) has burned $20B+ with no clear path to profitability. - Fiber broadband was a flop outside select cities. - Google+ (social network) launched and died in 18 months. The lesson? Investing in Google stock requires discipline: focus on search, ads, Cloud, and AI, and avoid betting on side projects. Sundar Pichai’s track record suggests he’s more risk-averse than his predecessors (e.g., no more "moonshot factories"), but even he can’t control regulatory whiplash or AI hype cycles.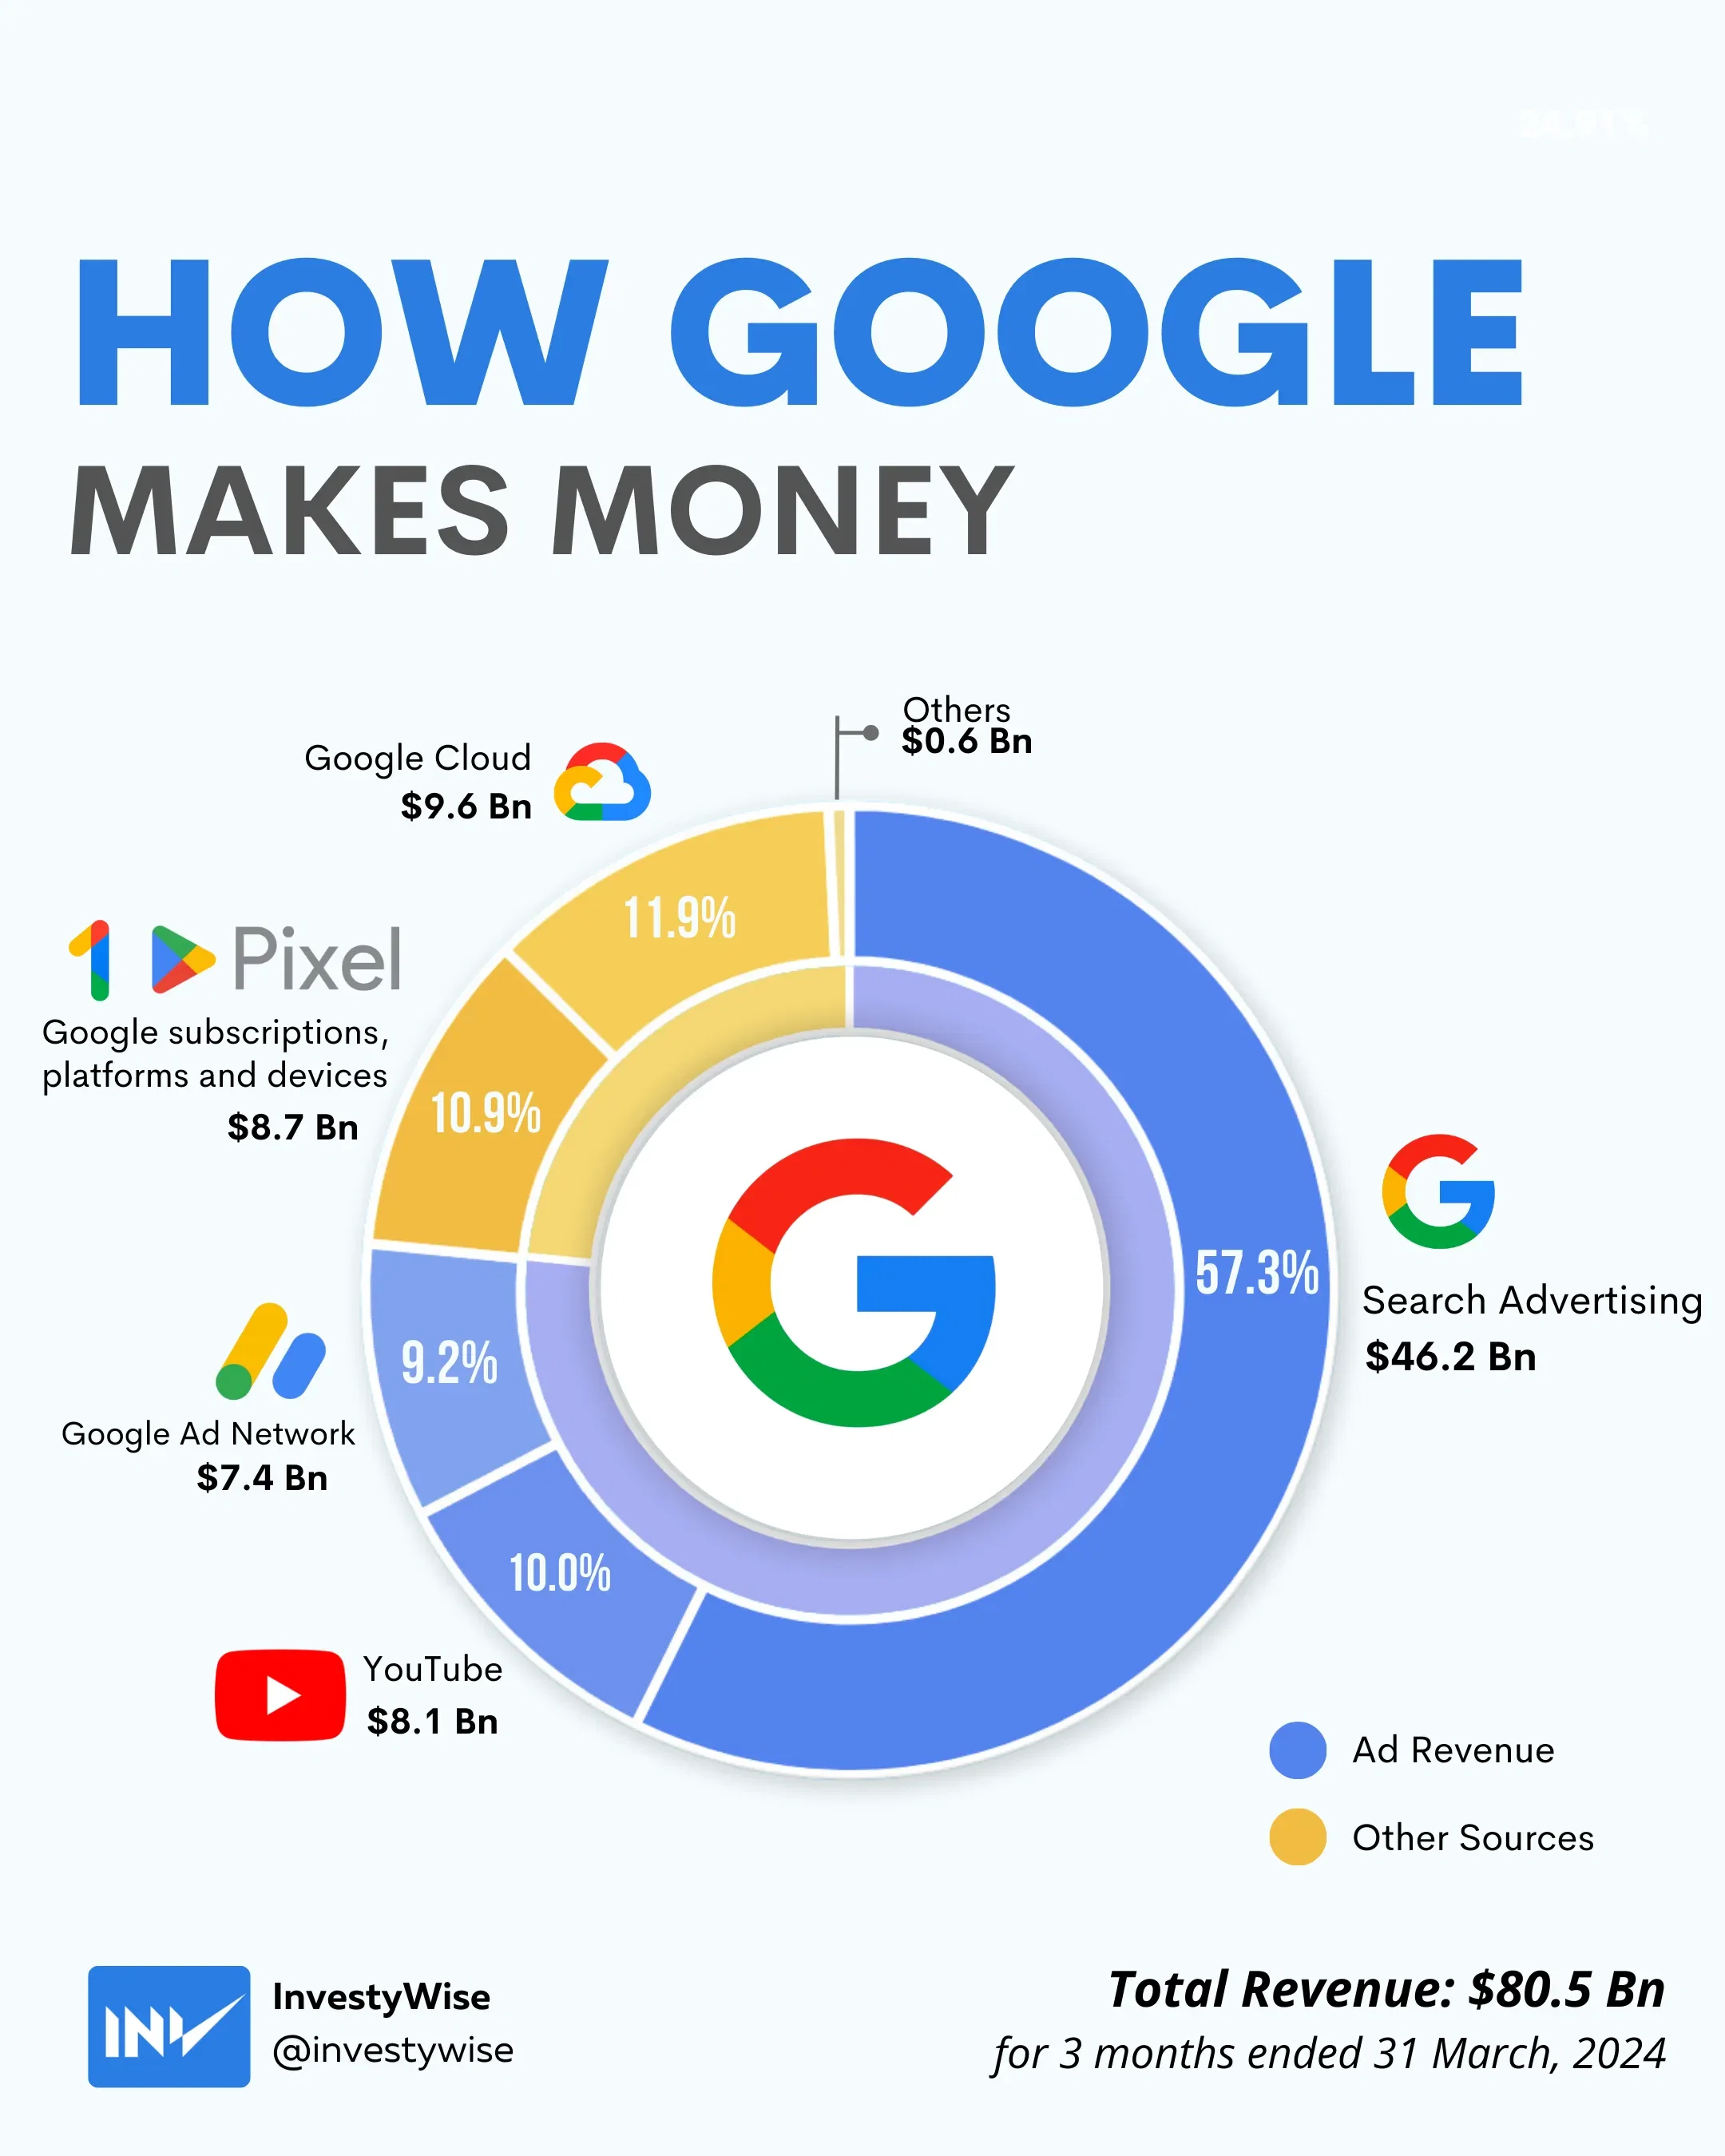
How These Facts Connect
The most successful Google stock investors don’t treat it as a static holding—they treat it as a portfolio of bets. Search and ads remain the cash cows, but Cloud and AI are the growth engines. The question isn’t whether Google will succeed, but how quickly it can monetize AI without destabilizing its core business. Hardware and international expansion are wildcards: they could pay off handsomely or become albatrosses. The biggest misconception about buying Google stock is that it’s a "set and forget" play. In reality, it demands active monitoring of three vectors: 1. Regulatory shifts (DMA, US antitrust). 2. AI adoption (Will enterprises pay for Vertex AI?). 3. Cloud profitability (Can it hit 20%+ margins by 2025?). Ignore any of these, and you’re gambling—not investing.| Factor | Opportunity | Risk | Key Metric to Watch |
|---|---|---|---|
| Advertising Duopoly | High margins, global reach | Antitrust breakup, AI reducing ad impressions | Cost per thousand impressions (CPM) growth |
| Google Cloud | 30%+ revenue growth, AI/ML dominance | Unprofitable, AWS/Azure competition | Gross margin expansion (target: 20%+) |
| AI Investments | First-mover advantage in enterprise AI | High R&D burn, unclear monetization | Enterprise AI contract wins (e.g., healthcare, finance) |
| International Markets | India/SEA growth at 25%+ annually | Regulatory hurdles, local competition | YouTube/Google Search MAUs in emerging markets |

Conclusion
Investing in Google stock isn’t about chasing the next earnings beat—it’s about understanding which parts of Alphabet’s business will compound over a decade. Search and ads will keep printing cash, but Cloud and AI are the real growth levers. The difference between a 12% annual return and a 20% one often comes down to whether you’re betting on Google’s past (search) or its future (AI and Cloud). The biggest mistake isn’t buying too late—it’s buying without a thesis. Google isn’t a one-trick pony anymore; it’s a multi-faceted conglomerate where each segment has its own risks and rewards. Do your homework, stay updated on regulatory filings, and avoid the trap of treating Google as a "safe" stock. It’s anything but.Comprehensive FAQs
Q: Is Google stock a good buy for beginners?
Google is not beginner-friendly unless you’re willing to hold for 5+ years. Its volatility comes from regulatory risks, AI bets, and Cloud execution. Beginners should start with index funds (e.g., S&P 500) before diving into individual tech stocks. If you proceed, focus on long-term trends (AI, Cloud) rather than quarterly earnings.
Q: Should I buy GOOGL or GOOG?
GOOGL (class A) has voting rights; GOOG (class C) doesn’t. The difference is symbolic for retail investors—both track the same fundamentals. Some prefer GOOGL for "ownership" vibes, but performance is identical. Tax implications vary by country, so check with a financial advisor.
Q: How does Google’s stock compare to Microsoft’s?
Microsoft (MSFT) has higher growth potential in AI (Azure, Copilot) but lower margins than Google’s ad business. Google’s stock is more defensive (ads are sticky), while Microsoft’s is more speculative (AI bets). A balanced portfolio might include both: Google for stability, Microsoft for upside.
Q: What’s the best time to buy Google stock?
There’s no perfect time. Google’s stock reacts to: - Earnings reports (search/ad growth vs. Cloud/AI investments). - Regulatory news (e.g., DMA rulings). - AI hype cycles (e.g., Gemini launches). Strategy: Use dollar-cost averaging (DCA) to mitigate timing risk. Buy 10% of your portfolio in chunks over 6–12 months.
Q: Does Google stock pay dividends?
No, Google does not pay dividends. Instead, it repurchases shares (buybacks), which can boost EPS and share price. For income investors, consider dividend aristocrats (e.g., Coca-Cola, Johnson & Johnson) or ETFs (e.g., SCHD) that yield 3–5% annually. Google’s returns come from growth, not dividends.
Q: How does antitrust risk affect Google stock?
Antitrust actions don’t kill Google overnight, but they erode margins. The EU’s DMA could force Google to: - Allow third-party ad tech (reducing ad revenue). - Unbundle services (e.g., separating Google Maps from search). Impact: Expect 5–10% stock drawdowns during regulatory battles, but long-term holders often recover. Monitor FTC and EU Commission filings for early warnings.
Q: Can Google stock crash 50% like in 2022?
A 50% crash is possible but unlikely in the next 3–5 years. Google’s search monopoly, cash flow, and Cloud growth provide buffers. However, black swan events (e.g., a US-EU trade war, AI patent lawsuits, or a search competitor breaking the duopoly) could trigger volatility. Mitigation: Keep a 10–20% allocation to Google in your portfolio, not 50%.
Q: Should I sell Google stock if AI doesn’t deliver?
Don’t sell on hype—sell on fundamentals. If Google’s Cloud margins stay below 20% and AI revenue lags Microsoft’s, that’s a red flag. But AI is a marathon, not a sprint. Google has $100B+ in cash reserves to weather slowdowns. Rule: Sell if two quarters of declining search/ad revenue coincide with Cloud/AI underperformance.
