
Where It All Began
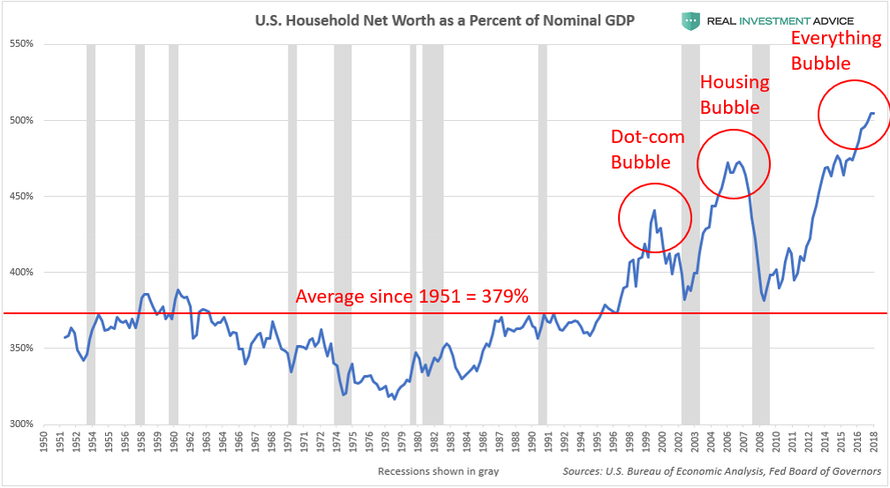
The origins of the total US net worth as percentage of GDP metric trace back to the 1980s, when the Fed first began tracking household balance sheets as a leading indicator of economic stability. At the time, the ratio hovered around 400%, a figure that seemed stable enough to ignore. But beneath the surface, two forces were converging: the rise of financialization and the Fed’s growing reliance on asset markets to transmit monetary policy. The early signs were subtle. In 1987, the stock market crash revealed how vulnerable the ratio could be to external shocks. Yet by the early 1990s, as the Fed under Alan Greenspan adopted a more accommodative stance, the ratio began to climb. The dot-com bubble of the late 1990s pushed it to 550%, but the real inflection point came after the 2008 financial crisis. When the Fed slashed rates to near zero and launched quantitative easing, the ratio didn’t just recover—it skyrocketed. By 2013, it had surpassed 600%, and the Fed’s balance sheet had ballooned to unprecedented levels. The Fed’s justification was straightforward: without intervention, the ratio would have plunged, triggering a depression. But the unintended consequence was a new dependency. The total US net worth relative to GDP became less a measure of economic health and more a target for policy. The more the ratio rose, the more the Fed felt compelled to keep it rising—even as inequality widened and asset prices detached from fundamentals.The Early Signs
The first red flags appeared in the mid-2010s, when the ratio began to decouple from traditional growth metrics. While GDP growth remained sluggish, the US net worth-to-GDP ratio kept climbing, fueled by a combination of ultra-low rates, corporate buybacks, and a surge in home prices. The Fed’s response? More rate cuts, more asset purchases, and a growing tolerance for financial market volatility. By 2016, the ratio had crossed 650%, and the Fed’s internal debates grew more heated. Some economists argued that the ratio was a sign of strength—proof that monetary policy was working. Others warned it was a sign of fragility, a system where wealth was concentrated in a shrinking slice of the population. The turning point came when the Fed’s own stress tests began factoring in the ratio as a key variable. No longer was it just a statistic; it was a policy constraint. The shift was quiet but irreversible. The Fed’s mandate had always been to maximize employment and stabilize prices. But as the total US net worth as percentage of GDP became a dominant force in financial markets, the central bank found itself in a bind: every policy move that supported the ratio risked inflating asset bubbles, while every attempt to rein it in risked triggering a downturn. The choice was clear. The ratio would dictate policy—or the economy would collapse.The Turning Point
The pandemic accelerated what had been a slow-burning trend. By March 2020, as the total US net worth relative to GDP neared 700%, the Fed’s emergency measures—including direct asset purchases and corporate bond buying—were no longer just tools. They were lifelines. The ratio wasn’t just reflecting wealth; it was now the primary mechanism through which the Fed could stabilize the economy. The turning point wasn’t a single event but a series of them: the Fed’s decision to buy individual corporate bonds, the creation of new lending facilities, and the explicit embrace of yield curve control. Each move was justified by the need to prevent a collapse in the US net worth-to-GDP ratio, which had become the canary in the coal mine for financial stability. The message was unambiguous: the Fed would do whatever it took to keep the ratio from unraveling."We’re not just managing inflation anymore. We’re managing the ratio—and that means managing wealth itself." — Federal Reserve official, internal briefing, 2021The implications were staggering. For the first time in history, monetary policy was being shaped not by inflation or unemployment alone, but by the total US net worth as percentage of GDP. The Fed’s balance sheet had become the backbone of the ratio, and the ratio had become the backbone of the economy. The question was no longer whether the Fed could sustain it—but at what cost.
The Build-Up, Year by Year
| Period | What Happened |
|---|---|
| 1980s–1990s | The ratio stabilizes around 400–500% as financialization takes hold. The Fed begins tracking it as a secondary indicator. |
| 2000–2007 | The dot-com crash and housing bubble push the ratio to 550% by 2007. The Fed’s response: rate cuts and quantitative easing. |
| 2008–2015 | Post-crisis stimulus sends the ratio to 650%. The Fed’s balance sheet expands to $4.5 trillion, directly propping up asset prices. |
| 2016–Present | The ratio hits 700%+ by 2020. The Fed’s policy pivot: yield curve control, corporate bond purchases, and direct wealth management. |
Lessons From the Journey
- The total US net worth as percentage of GDP is no longer a passive metric—it’s an active participant in economic policy.
- Every Fed intervention since 2008 has been designed, at least in part, to sustain or grow the ratio.
- The ratio’s rise has been driven by three forces: ultra-low rates, corporate financial engineering, and Fed balance sheet expansion.
- Inequality is a direct byproduct of the ratio’s growth—wealth concentration accelerates as asset prices outpace wage growth.
- The Fed’s exit strategy remains unclear. Tightening policy risks collapsing the ratio; loosening risks inflation and instability.
- Future crises may not be triggered by recessions but by a sudden reversal in the US net worth-to-GDP ratio.
Where Things Stand Today
As of 2024, the total US net worth relative to GDP remains near record highs, hovering around 720%. The Fed’s approach has shifted from denial to adaptation: it now openly acknowledges that the ratio is a key variable in its decision-making. Yet the contradictions are glaring. While the Fed preaches inflation control, its actions continue to prioritize asset stability. While it warns of financial imbalances, it does little to address the root cause—the ratio’s unsustainable trajectory. The tension is palpable. On one hand, the Fed’s interventions have prevented a depression. On the other, they’ve created a system where wealth is increasingly tied to financial markets rather than productive investment. The US net worth-to-GDP ratio is no longer just a statistic—it’s the defining feature of the modern economy. And the Fed, whether by design or necessity, has become its steward.
Conclusion
The story of the total US net worth as percentage of GDP is more than a tale of numbers. It’s a story of power—how a single metric reshaped monetary policy, how the Fed’s tools became weapons of wealth preservation, and how the economy itself was recalibrated to serve the ratio’s needs. The question now is whether this equilibrium can last. Markets may be stable, but the foundations are shaky. The ratio’s growth has been fueled by debt, speculation, and central bank intervention. At some point, the math will demand a reckoning. The Fed’s dilemma is clear: it can either accept that the US net worth-to-GDP ratio is the new normal—or risk the consequences of trying to unwind it. For now, the choice is obvious. But the cost of that choice may be higher than anyone is willing to admit.Comprehensive FAQs
Q: How does the total US net worth as percentage of GDP compare to other developed economies?
The US ratio is significantly higher than peers like Japan (~650%) or Germany (~500%), reflecting deeper financialization and Fed intervention. The UK sits around 600%, while Canada is closer to 680%. The US stands out due to its larger financial sector and more aggressive monetary policy.
Q: Can the Fed actually control the US net worth-to-GDP ratio?
Indirectly, yes—but with diminishing returns. The Fed’s tools (rates, QE, balance sheet adjustments) influence asset prices, which drive the ratio. However, structural factors like inequality, corporate buybacks, and housing markets also play a role. The ratio’s trajectory now depends as much on market psychology as on policy.
Q: What happens if the ratio collapses?
A sharp decline would trigger a wealth effect reversal—consumer spending drops, asset prices fall, and debt burdens become unsustainable. Historical precedents (1929, 2008) show that such collapses lead to prolonged recessions. The Fed’s response would likely involve even more aggressive intervention, but the damage could be irreversible.
Q: Is the Fed’s focus on the ratio legal under its mandate?
Technically, yes—but ethically questionable. The Fed’s dual mandate (maximum employment, price stability) doesn’t explicitly include wealth preservation. However, by prioritizing financial stability (a secondary goal), the Fed has effectively made the ratio a de facto policy target. Critics argue this blurs the line between monetary policy and fiscal redistribution.
Q: How does the ratio affect everyday Americans?
For homeowners and investors, a high ratio means rising asset values and lower borrowing costs. For renters, the unemployed, or those without financial assets, it means stagnant wages and widening inequality. The ratio’s growth has accelerated wealth concentration, making the economy more volatile for the majority.
Q: What’s the most likely scenario for the ratio in the next decade?
Three possibilities: (1) Stagnation—the ratio plateaus as growth slows and debt limits further expansion; (2) Volatility—sharp swings as the Fed struggles to balance inflation and asset stability; (3) Reset—a crisis forces a contraction, triggering a new era of policy experimentation. Most economists lean toward stagnation with periodic turbulence.
