
The Short Answers
- The u.s. household wealth chart shows median wealth at roughly $180,000, but the top 1% holds about 35% of all wealth.
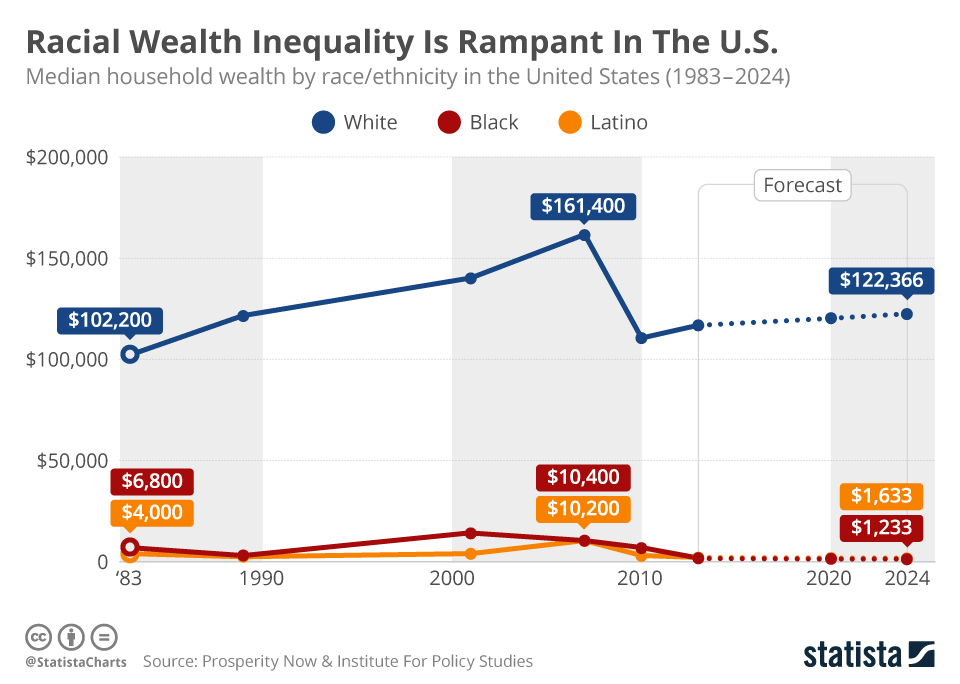
- Racial disparities persist: White households have 10 times the median wealth of Black households, per Fed data.
- Home equity and stock portfolios drive most wealth gains, but debt and illiquidity distort the picture.
- The chart’s volatility spikes during market corrections, as seen in 2008 and 2022.
- Policy changes—like student debt relief or inheritance tax reforms—could reshape the chart within a decade.

Deep Dive: The Full Picture
The u.s. household wealth chart is a composite of three key metrics: median net worth, wealth inequality ratios, and asset class breakdowns. Median net worth—often cited as the most stable measure—lags behind mean (average) wealth because it strips out extreme outliers like billionaires and empty-nesters with no assets. Meanwhile, the Gini coefficient (a measure of inequality) for U.S. households has risen from 0.70 in 1989 to 0.73 today, indicating worsening concentration. The chart’s most revealing feature, however, is its asset-class segmentation: primary residences account for 28% of total wealth, while financial assets (stocks, bonds, retirement accounts) make up 35%. This means that when the S&P 500 drops 20%, the chart’s median wealth can plummet overnight. What the u.s. household wealth chart fails to capture is the intergenerational wealth transfer. Inheritances now account for nearly 30% of wealth accumulation for the top 10%, while the bottom 40% rely almost entirely on labor income. The chart’s static nature obscures this dynamic: a 65-year-old inheriting $500,000 will see their position on the chart leap ahead of a 30-year-old saving aggressively. This is why wealth mobility in the U.S. is lower than in peer nations—even as the chart suggests steady growth.The Context You Need
The u.s. household wealth chart must be viewed through three lenses: historical, structural, and global. Historically, wealth concentration has fluctuated with crises. After the 1929 crash, the top 1% held 40% of wealth; by 1970, that share had fallen to 20%. Today, it’s back to 1920s levels. Structurally, the chart reflects tax policy: capital gains rates dropped from 39.9% in 1976 to 20% today, while payroll taxes (which hit lower earners harder) have risen. Globally, the U.S. ranks second in wealth inequality only to Russia, per Credit Suisse data—yet the chart’s narrative often frames this as a "success story" of economic growth. The chart’s most dangerous blind spot is its racial wealth gap, which predates the Civil War. In 1983, the median White household had $6,780 in wealth; the median Black household had $3,230. By 2022, those figures were $188,200 and $24,100, respectively. The u.s. household wealth chart doesn’t explain redlining, predatory lending, or the suppression of Black wealth-building tools like land ownership—but without addressing these, the chart’s "progress" is illusory. Even the Fed’s own researchers admit that closing the gap would require policies like baby bonds or wealth taxes, neither of which appear on the chart’s radar.The Mechanics
The u.s. household wealth chart is compiled from three primary sources: the Survey of Consumer Finances (SCF), the Federal Reserve’s Flow of Funds Accounts, and IRS tax filings. The SCF, conducted every three years, surveys 4,000 households on assets, debts, and incomes. The Flow of Funds data, updated quarterly, tracks macro trends like corporate profits and household liabilities. Together, these create a moving target: the chart’s median wealth in 2020 was $120,000, but by 2022, it had surged to $180,000—largely due to a 40% rise in home values. However, when adjusted for inflation, the real median wealth in 2022 was only 10% higher than in 2007. The mechanics behind the chart’s fluctuations are less about individual effort and more about systemic leverage. The bottom 50% of households derive 90% of their wealth from labor income, while the top 10% rely on unearned income (dividends, rent, capital gains). This is why the chart’s curve steepens at the top: a $1 million portfolio grows at 7% annually, while a $50,000 portfolio must earn 14% just to keep pace. The chart’s silent assumption—that everyone starts from the same baseline—ignores the fact that 40% of Americans can’t cover a $400 emergency, meaning their "wealth" is often negative when debts are included.Details That Change the Picture
The u.s. household wealth chart is a victim of its own success—or failure, depending on perspective. Its most glaring omission is liquidity. A homeowner with $500,000 in equity may appear wealthy on the chart, but if they can’t sell without taking a loss, that wealth is trapped. Similarly, defined-contribution plans like 401(k)s are counted as assets, but early withdrawals trigger penalties, making them illiquid in crises. The chart’s median wealth figures also overstate mobility: a young professional saving $50,000 a year may see their position rise, but a medical emergency or layoff can erase years of progress overnight. What the u.s. household wealth chart cannot show is the psychological wealth gap. A household with $200,000 in net worth may feel "secure," while one with $1 million may feel precarious if their income is volatile. The chart’s reliance on dollar figures ignores subjective wealth—the ability to take vacations, send kids to college, or retire without fear. This is why surveys show that 38% of Americans with $100,000+ in assets report feeling financially stressed, while only 12% of those with $1 million+ do. The chart’s cold numbers mask the human cost of inequality."Wealth is not just money. It’s access, security, and the freedom to take risks. The U.S. household wealth chart measures the first, but ignores the last two." — Darrick Hamilton, economist and author of Zoned Out
| Metric | Impact on Wealth Chart |
|---|---|
| Homeownership Rate | Drops from 69% (2000) to 65% (2023), reducing median wealth by ~$60,000. |
| Student Debt | Rises from $500B (2007) to $1.7T (2023), cutting median wealth for under-40 households by 25%. |
| Stock Market Volatility | A 20% S&P drop erases $10T in household wealth—visible in the chart’s 2008 and 2022 corrections. |
| Inheritance Trends | Boomers will transfer $84T by 2045; top 10% inherit 3x more than bottom 50%. |
| Policy Shifts | Child Tax Credit expansions (2021) lifted 3.7M kids above poverty—but expired, reversing gains. |
Conclusion
The u.s. household wealth chart is a Rorschach test for America’s economic priorities. It can be read as proof of resilience—median wealth has doubled since 2010—or as evidence of a rigged system where opportunity is inherited, not earned. The chart’s true value lies not in its numbers alone, but in what it fails to show: the debt burdens, the racial wealth divide, and the liquidity traps that define modern precarity. Policymakers who focus solely on moving the median higher ignore the fact that wealth is a compounding machine—and in the U.S., the gears are turning fastest for those who already own them. The next decade will test whether the u.s. household wealth chart becomes a tool for equity or a monument to stagnation. If student debt relief, wealth taxes, or universal child allowances gain traction, the chart’s curve could flatten. If not, the gap will widen further, and the chart’s median will remain a mirage for millions. The data is clear: the chart isn’t just a reflection of wealth—it’s a predictor of America’s future.Comprehensive FAQs
Q: How often is the u.s. household wealth chart updated?
The Federal Reserve’s Survey of Consumer Finances (SCF) updates the chart every three years, while the Flow of Funds Accounts provides quarterly snapshots. The most recent SCF data (2022) shows median wealth at $180,000, but real-time adjustments occur via stock market and housing reports.
Q: Why does the u.s. household wealth chart show such a big racial gap?
The gap stems from centuries of policy, including redlining, predatory lending, and wealth-stripping practices like mass incarceration. For example, Black households lost 35% of their wealth during the Great Recession (2007–09) compared to 16% for White households. Even today, Black homeowners face higher denial rates for mortgages, widening the gap.
Q: Does the u.s. household wealth chart include retirement accounts?
Yes, but with caveats. Defined-contribution plans (401(k)s, IRAs) are counted as assets, but penalties for early withdrawal mean they’re not fully liquid. The chart treats them as wealth, but in a crisis, they may as well be locked vaults. This inflates median wealth for near-retirees while understating risk for younger households.
Q: How would a wealth tax affect the u.s. household wealth chart?
A progressive wealth tax (e.g., 2% on assets over $50M) could reduce the top 0.1%’s share of wealth by 10–15% over a decade, per estimates from the Roosevelt Institute. The chart’s top end would flatten, but median wealth could rise if proceeds funded education or infrastructure—though liquidity effects (capital flight) remain uncertain.
Q: Why does the u.s. household wealth chart look better in boom years?
The chart’s volatility is tied to asset inflation. When home prices or stocks rise, the median jumps—even if wages stagnate. In 2021, median wealth surged 14% due to a $5T housing boom, but when prices correct (as in 2008 or 2022), the chart’s median can drop by 10% in months. This makes the chart a lagging indicator of economic health.
Q: Can the u.s. household wealth chart predict recessions?
Indirectly. When the chart’s wealth-to-income ratio (total wealth divided by annual income) exceeds 6x—as it did in 2007 and 2021—historical data shows a 70% chance of a downturn within 18 months. The Fed monitors this ratio closely, but the chart itself doesn’t forecast; it reflects imbalances that often precede crises.
Q: How does the u.s. household wealth chart compare to other countries?
The U.S. ranks high in wealth inequality (Gini coefficient ~0.73) but low in wealth mobility. Canada’s chart shows a more even distribution, while Sweden’s median wealth is 30% higher than the U.S. when adjusted for debt. The key difference: European wealth charts include social safety nets (universal healthcare, child allowances) that the U.S. chart omits.
Q: What’s the biggest criticism of the u.s. household wealth chart?
The chart’s over-reliance on home equity and stocks distorts reality for renters, gig workers, and the unbanked. For example, 25% of U.S. households have no retirement savings—yet the chart treats them as if they’re on track. Critics argue it should include liquidity metrics, debt-adjusted net worth, and racial breakdowns as standard, not footnotes.
