Breaking Down the Numbers
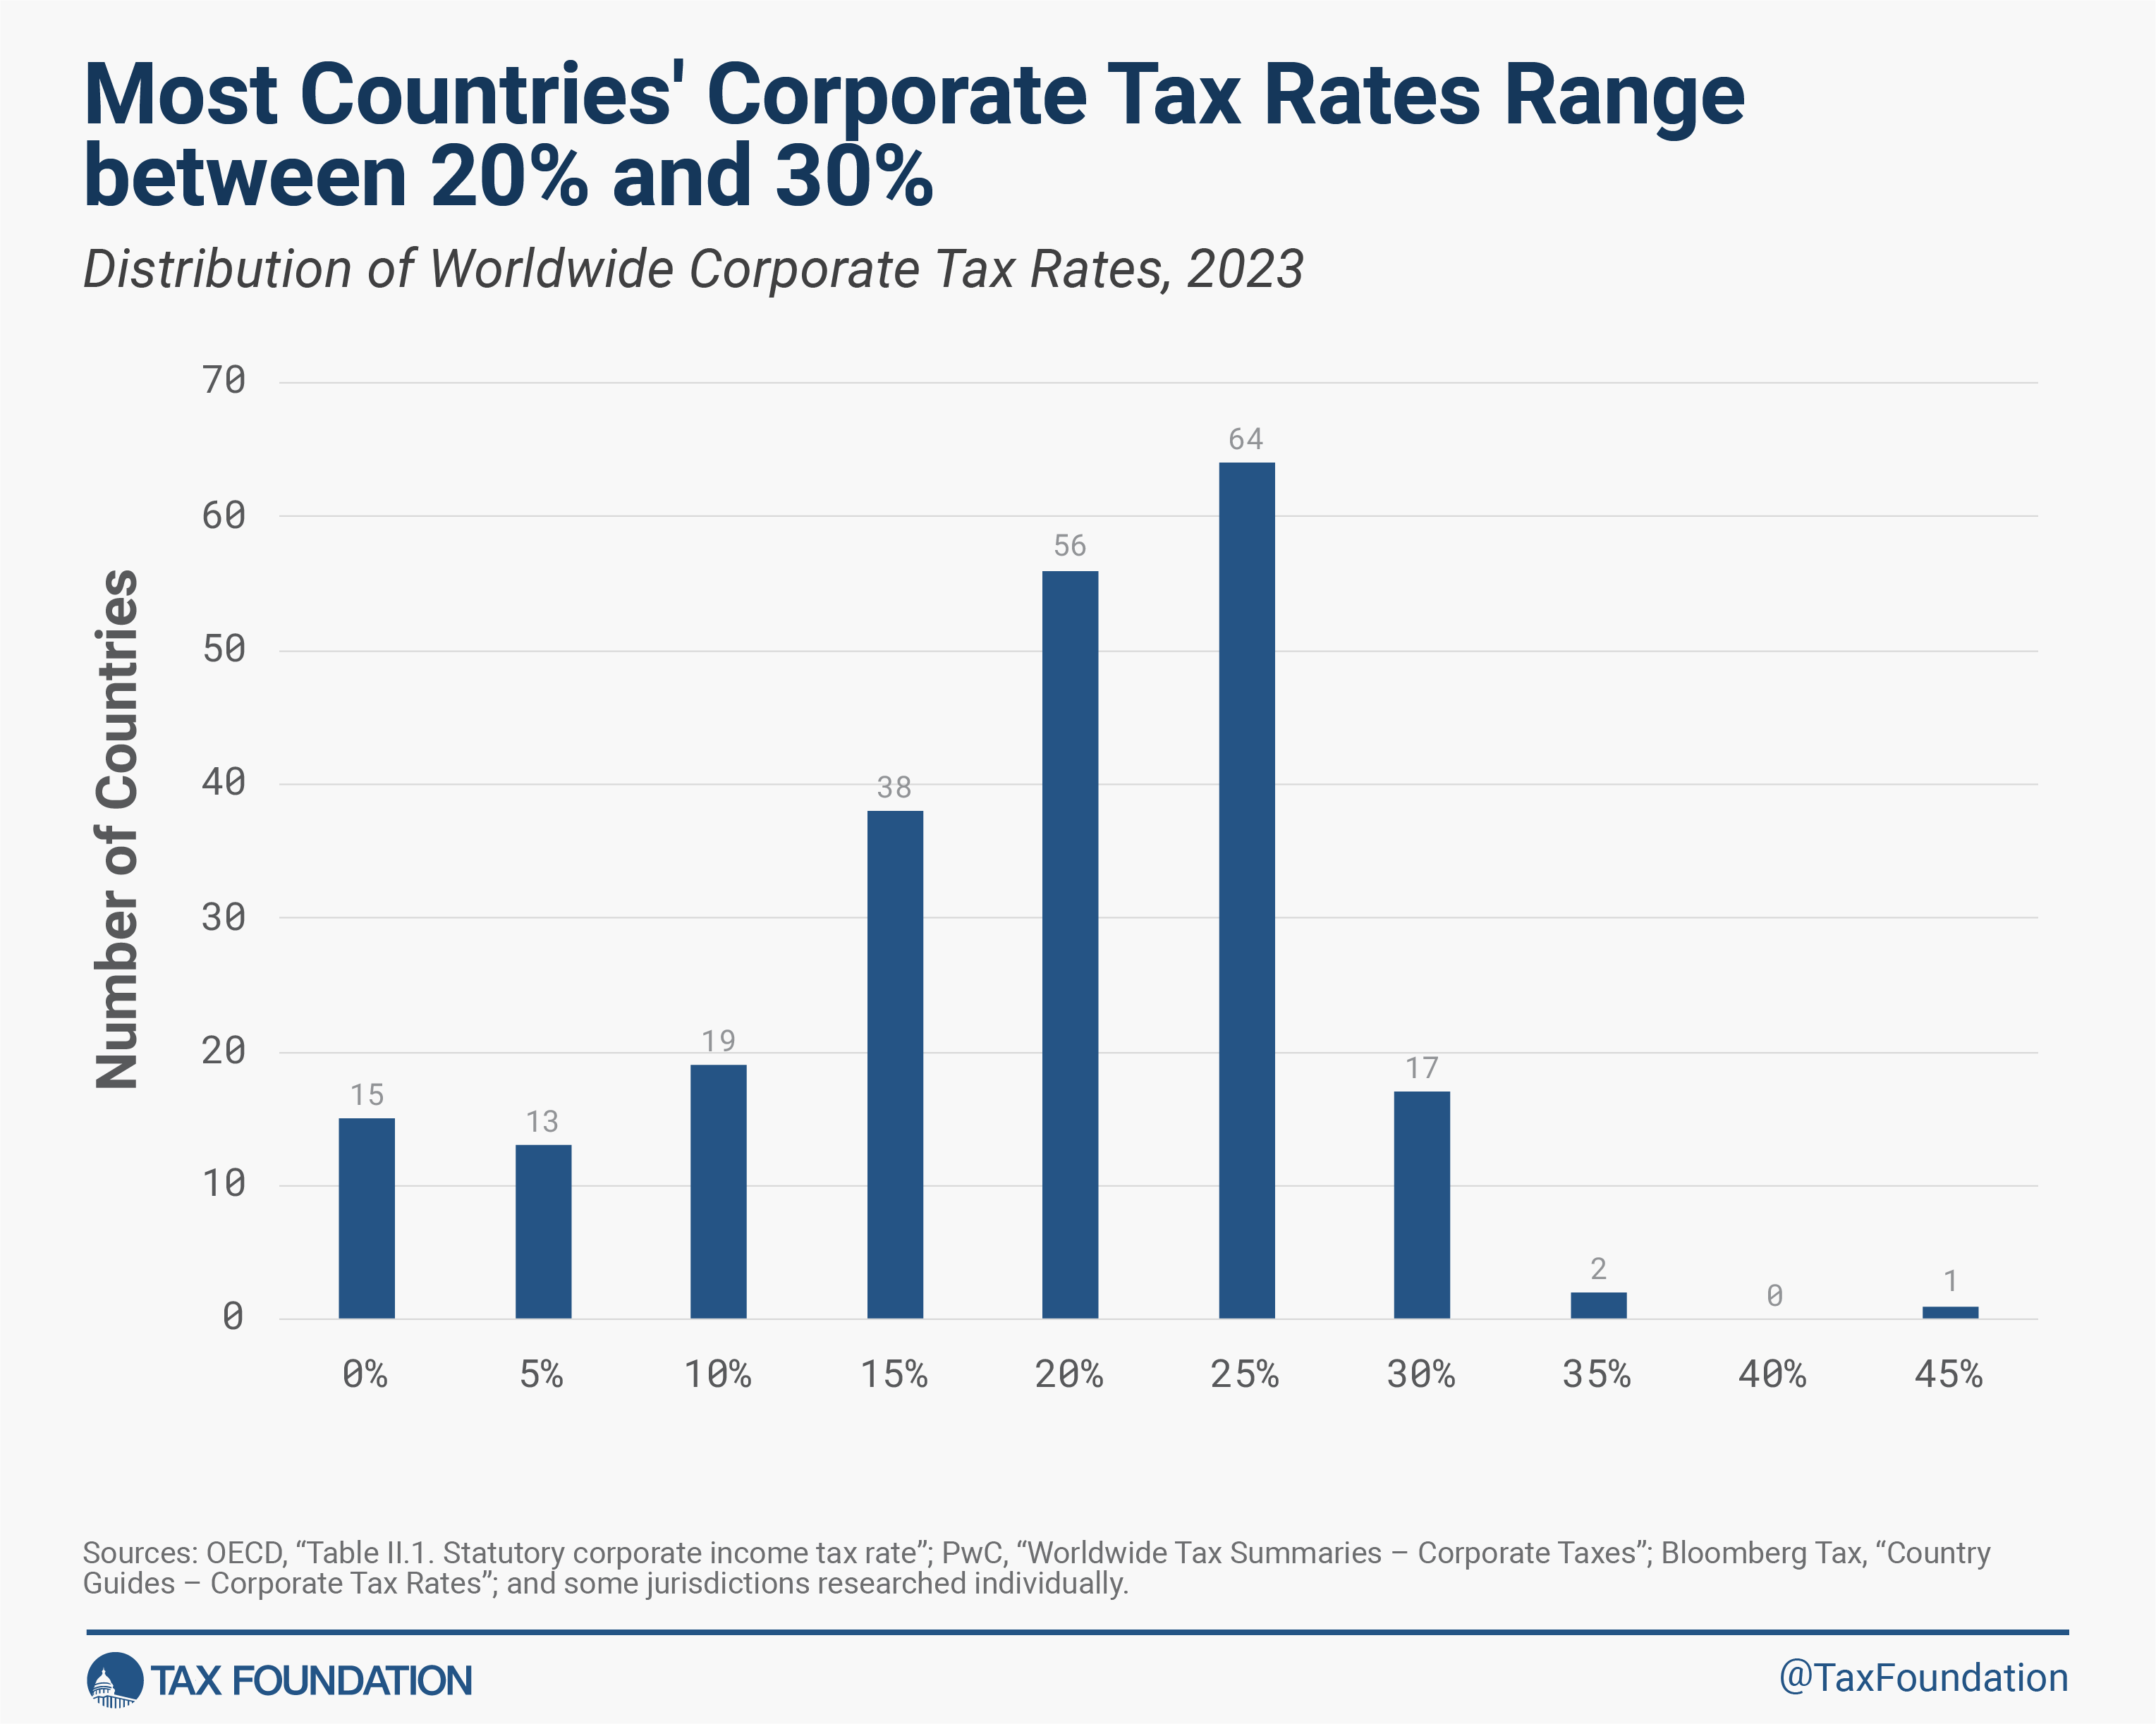
Tax systems vary as widely as the societies they fund. At one extreme, Nordic nations combine high personal income taxes—often 40-50%—with generous social benefits. At the other, Caribbean tax havens offer corporate rates as low as 0%, though their true economic impact remains debated. The OECD’s 2023 report confirms that the tax rate of countries correlates with GDP per capita—but only up to a point. Beyond 40% marginal rates, revenue growth stalls, yet cutting taxes too aggressively can hollow out public services. The relationship between tax rates and economic performance isn’t linear. Switzerland’s cantonal system, for example, blends high personal taxes in Zurich with low corporate rates in Zug—creating a patchwork that attracts both wealthy individuals and multinational HQs. Meanwhile, sub-Saharan Africa grapples with informality: in Nigeria, only about 3% of the workforce pays income tax, making revenue projections volatile. The tax rate of countries must adapt to these realities, balancing collection efficiency with citizen buy-in.The Verified Baseline
Public data paints a clear picture of global tax landscapes. The World Bank’s 2023 Doing Business report ranks Estonia’s 20% flat tax as the most business-friendly in Europe, while Denmark’s 55.9% top marginal rate remains the highest in the OECD. Corporate tax rates tell a different story: the U.S. federal rate sits at 21%, but state-level variations—from California’s 8.8% to Texas’s 0%—create a mosaic. Meanwhile, VAT rates in the EU range from Hungary’s 5% to Sweden’s 25%, reflecting divergent views on consumption taxation. What’s undeniable is the global race to the bottom in corporate taxation. Ireland’s 12.5% rate has lured Apple, Google, and Facebook, while Luxembourg’s 18% and Singapore’s 17% follow suit. The EU’s 2022 Digital Services Tax—aimed at tech giants—proves that even low-tax jurisdictions aren’t immune to pressure. These shifts aren’t just about numbers; they’re about fiscal sovereignty in an era of cross-border capital.What the Estimates Suggest
Private-sector analysis suggests that tax competition is accelerating. PwC’s 2023 World Tax Summit estimates that by 2025, at least 15 more countries will adopt territorial tax systems (taxing only domestic income), up from 10 today. This could reduce global corporate tax revenue by $100 billion annually, according to IMF projections—though the impact on GDP growth remains uncertain. Meanwhile, wealth taxes in Europe are under scrutiny: France’s 2018 abolition led to a 1.5% GDP boost, but Spain’s retention of a 3% rate on fortunes over €7 million shows persistence in progressive models. The tax rate of countries is also being reshaped by behavioral shifts. Remote work has eroded the link between residency and taxation; Portugal’s NHR program attracted €1.5 billion in foreign investment in 2022, but critics argue it benefits the wealthy while straining public services. Similarly, cryptocurrency taxation—ranging from 0% in Malta to 30%+ in South Korea—highlights how quickly tax systems must evolve to keep pace with new assets. The estimates, however, carry caveats: behavioral responses to tax changes are often unpredictable, and long-term data is scarce.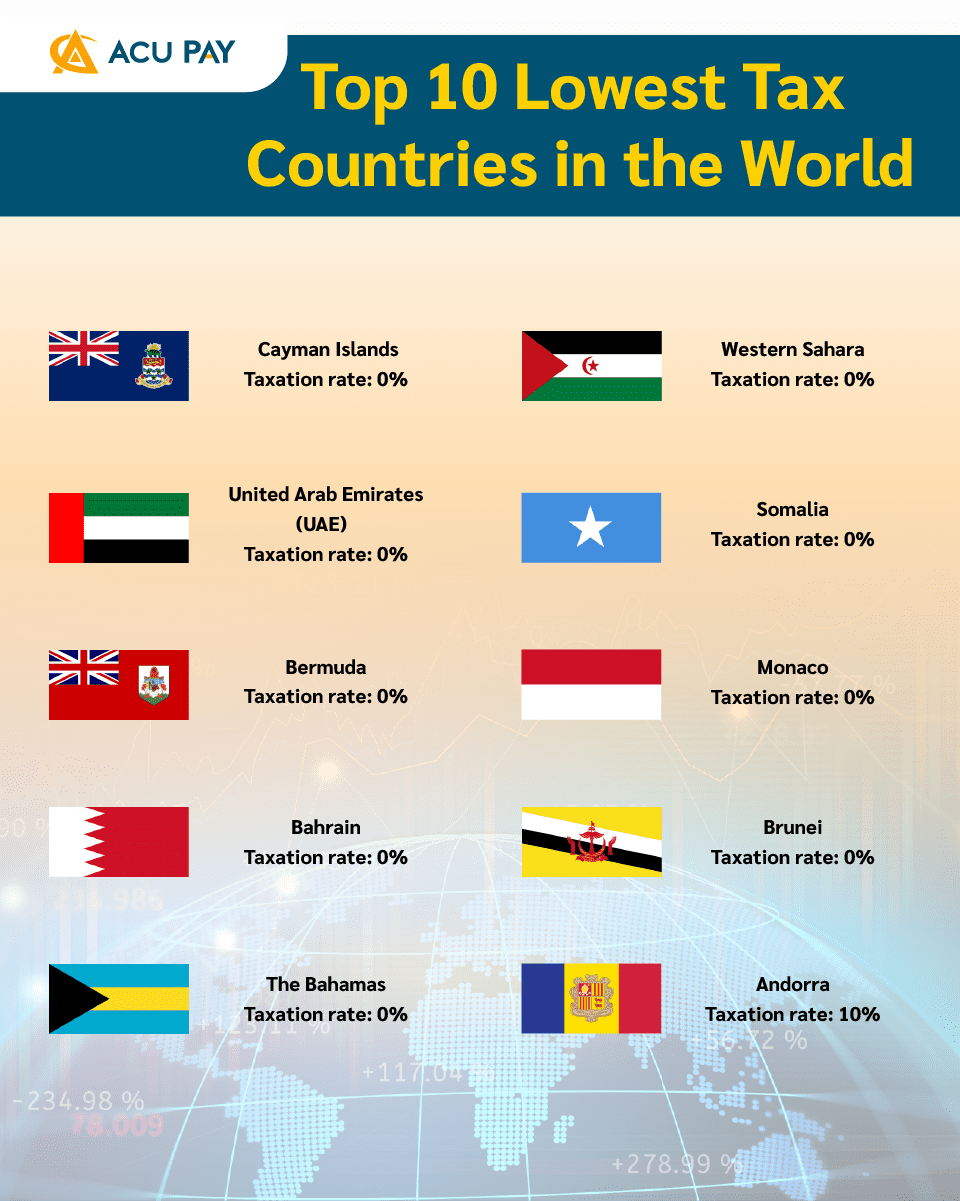
Case Study: A Closer Look
Nowhere is the tension between tax rates and national identity more visible than in Switzerland. Its cantonal system—where Zurich’s top income tax hits 43% while Zug’s corporate rate is 12.1%—creates a labyrinth that confounds outsiders. The country’s fiscal federalism allows regions to compete for capital, yet maintains social cohesion through strong local governance. This duality has made Switzerland a magnet for both ultra-wealthy individuals and multinational firms, despite its reputation as a tax haven. The trade-offs are stark. While Zug’s low corporate tax fuels its $80 billion tech sector, Zurich’s high personal taxes fund elite universities and healthcare. The system relies on explicit citizen consent: voters in each canton decide tax rates annually, ensuring transparency. Yet critics argue this fragmentation undermines national solidarity. As one Swiss economist noted:"Our system works because it’s a pact between regions—each pays for what it values. But when one canton slashes taxes to attract firms, it’s not just an economic decision; it’s a vote against redistribution." — Dr. Markus Meier, University of St. GallenThe impact of these choices is measurable, though not always linear:
| Factor | Estimated Impact |
|---|---|
| Corporate tax differential (Zug vs. Zurich) | ~$5 billion annual revenue gap; Zug’s GDP per capita is 20% higher |
| Wealth concentration in Zug | Top 1% holds ~40% of assets (vs. ~25% in Zurich); social services are leaner |
| Brain drain risk | High-skilled workers leave cantons with high income taxes; counterbalanced by elite education |
| Tourism dependency | Low-tax cantons rely more on hospitality; vulnerable to global shocks |
| Political stability | Consensus-driven; but rising inequality sparks periodic referendums on tax reforms |
What This Means Going Forward
The tax rate of countries is evolving faster than ever, driven by three megatrends. First, digitalization is eroding the link between physical presence and taxation. The EU’s 2024 proposal to tax tech giants based on user activity—rather than profits—could redefine global norms. Second, climate policy is introducing new taxes (e.g., carbon levies in Sweden) that blur the line between fiscal and environmental goals. Finally, demographic decline in aging societies (Japan, Italy) is forcing higher taxes on shrinking workforces, risking backlash. The biggest question isn’t whether tax rates will change, but how. The OECD’s 2021 global minimum tax agreement (15%) is a step toward coordination, but enforcement remains weak. Meanwhile, emerging markets—from Rwanda’s 30% corporate rate to Vietnam’s 20%—are adopting hybrid models to balance growth and equity. The tax rate of countries is no longer a static tool; it’s a dynamic variable in a high-stakes game of global competition.
Conclusion
Taxation is the ultimate reflection of a society’s priorities. The tax rate of countries reveals whether a nation values redistribution over growth, stability over innovation, or sovereignty over global integration. There’s no one-size-fits-all answer—Denmark’s high taxes fund a society most citizens defend, while Singapore’s low rates fuel a growth machine that lifts all boats. The challenge lies in adapting without losing sight of the social contract. As capital grows more mobile and governments more desperate for revenue, the old rules are breaking down. The tax rate of countries will continue to be a battleground—not just between nations, but between visions of what a fair and functional society should look like. The winners won’t be those with the lowest rates, but those that strike the most sustainable balance.Comprehensive FAQs
Q: Which country has the highest income tax rate?
The highest verified marginal income tax rate is in Denmark (55.9%), followed by Sweden (52.0%) and Norway (47.8%). However, these rates apply only to the highest brackets, and social contributions (e.g., healthcare levies) can push effective rates higher.
Q: Do low corporate tax rates always boost GDP?
Not necessarily. While Ireland’s 12.5% rate attracted multinationals, local job creation is limited—most profits are repatriated. Studies show that tax cuts beyond 20% often yield diminishing returns on GDP growth, per IMF research. The key is tax efficiency, not just low rates.
Q: How do tax havens like the Cayman Islands operate with 0% corporate tax?
They rely on financial secrecy and licensing fees rather than traditional taxation. The Cayman Islands, for example, earns ~$1.5 billion annually from offshore banking licenses—far more than corporate tax revenue would generate. These models depend on global imbalances in regulation.
Q: Can a country have both high income taxes and low corporate taxes?
Yes, but it requires careful design. Switzerland does this via cantonal autonomy, while Estonia’s flat 20% income tax (with dividends taxed at 20%) funds services without corporate tax breaks. The trade-off is reliance on consumption taxes (VAT) to plug gaps.
Q: What’s the most controversial tax policy today?
The OECD’s 15% global minimum tax is polarizing. Supporters argue it curbs race-to-the-bottom dynamics, while critics (e.g., U.S. Republicans) call it unfair interference. Enforcement remains the biggest hurdle—tax havens like Dubai and Singapore have found loopholes.
Q: How do wealth taxes compare globally?
France’s abolished wealth tax was replaced by a 3% property tax on fortunes over €1.3 million, while Spain retains a 3% rate on €7M+. The U.S. has no federal wealth tax, but New York and California impose estate taxes on multi-million-dollar inheritances. Effectiveness varies—France’s tax drove capital flight, while Spain’s is narrower in scope.
Q: What’s the biggest misconception about tax rates?
That lower taxes always mean more growth. History shows that Nordic countries (high taxes + strong services) outperform many low-tax jurisdictions in long-term productivity. The real driver is how revenue is spent—not the rate itself.
Q: How might AI change tax systems?
AI is already used for automated audits (e.g., Israel’s tax agency) and behavioral tax design (e.g., nudging compliance via apps). However, it could also exacerbate inequality if used to optimize tax avoidance for the ultra-wealthy. The EU is exploring AI-driven tax transparency tools to counter this.
