Breaking Down the Numbers
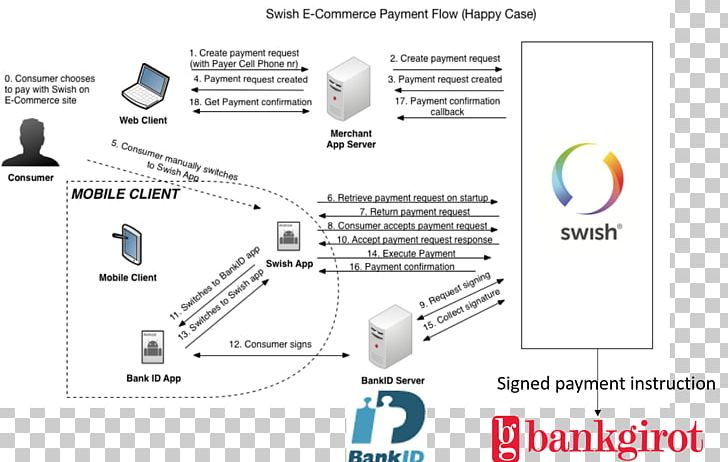
Swish’s financial impact isn’t just measured in transactions—it’s measured in behavioral change. By 2023, the app processed an estimated 1.5 billion transactions annually, with peak daily volumes surpassing 20 million individual payments. This isn’t just volume; it’s velocity. The average Swede uses Swish 11 times per month, with usage spikes on Fridays and Sundays, when social payments dominate. The app’s revenue model is indirect: banks earn interchange fees on merchant transactions, while Swish itself generates income through premium features like travel insurance or loyalty partnerships. Unlike Venmo or PayPal, Swish doesn’t charge users for peer-to-peer transfers, ensuring its stickiness. The economic ripple effects are harder to quantify but undeniable. Studies suggest Swish has reduced cash usage by 40% in Sweden, saving banks millions in ATM and processing costs. For small businesses, the shift to digital payments cut transaction fees by nearly half compared to card networks. Yet the biggest win may be intangible: Swish eliminated the "float" period between when a payment is initiated and when funds clear, accelerating Sweden’s move toward an instant-payment economy. The swish application didn’t just compete with cash—it made cash obsolete faster than any other tool in Europe.The Verified Baseline
Swish was born from collaboration, not competition. The six founding banks—Danske Bank, Handelsbanken, Nordea, SEB, Swedbank, and ICB— pooled resources to create a unified platform, ensuring no single institution could dominate. This structure gave Swish its early legitimacy: users trusted it because it wasn’t tied to any one bank’s agenda. The app’s core functionality—sending money via phone number—was simple but revolutionary. Unlike Apple Pay or Google Wallet, which required NFC-enabled devices, Swish worked on basic feature phones, broadening its reach. By 2015, Swish had surpassed 1 million active users, a milestone that proved its utility beyond early adopters. The app’s security model, combining two-factor authentication and transaction limits, addressed a critical flaw in earlier mobile payment systems: fraud. When a user reported a scam in 2017 involving fake "Swish support" calls, the banks collectively updated their fraud alerts, reinforcing trust. The swish application wasn’t just a tool; it was a shared responsibility. Regulatory oversight from the Swedish Financial Supervisory Authority (Finansinspektionen) ensured compliance without stifling innovation. These early decisions—collaboration over competition, security over speed—laid the foundation for its dominance.What the Estimates Suggest
Industry analysts project Swish’s transaction volume could exceed 2 billion annually by 2026, driven by cross-border adoption and integration with e-commerce. While Sweden remains its core market, estimates suggest 300,000–500,000 users in Norway and Denmark by 2025, as those countries explore similar instant-payment systems. The app’s expansion into business-to-consumer (B2C) payments—like QR code checkouts—has reportedly boosted merchant adoption by 25% in Sweden, with figures around the £50 million range in annual savings for small retailers. Speculation about Swish’s future often centers on its potential IPO or spin-off from the bank consortium. While no formal plans exist, whispers of a valuation in the $2–5 billion range have circulated among investors, though such figures remain unconfirmed. The bigger question is whether Swish can replicate its model in markets with fragmented banking systems. Its success hinges on two factors: maintaining its no-fee peer-to-peer model and expanding features without alienating power users. The swish application’s next act may define the future of instant payments globally.
Case Study: A Closer Look
In 2019, Stockholm’s public transport authority, SL, integrated Swish into its ticketing system, allowing commuters to tap their phones instead of buying physical cards. The move was risky: SL had to ensure the system could handle 100,000 daily transactions without glitches. Within six months, Swish-based payments accounted for 60% of all trips, a shift that saved SL £3 million annually in card production and distribution costs. The case study reveals how Swish’s infrastructure became a public utility—one that governments now rely on. The decision to prioritize Swish over competitors like Apple Pay reflected a broader trend: institutional trust in the app’s reliability. SL’s IT team cited three key factors in their choice: Swish’s 99.9% uptime, its ability to handle high-volume spikes, and the fact that 95% of Stockholm residents already had the app. The trade-off? SL had to cede control over data to Swish’s bank partners, a compromise that paid off when ridership surged during the pandemic. Today, Swish isn’t just a payment method for SL—it’s the default experience."Swish didn’t just replace our old system; it redefined what ‘convenience’ means for commuters. The day we launched, we had a 70% adoption rate among new users—no marketing, just word of mouth." — Erik Bengtsson, former SL digital services director (2020)
| Factor | Estimated Impact |
|---|---|
| Reduction in physical ticket sales | £3M+ annual savings for SL |
| Increase in daily active users | 30% rise in commuter engagement |
| Fraud reduction via Swish’s auth system | 40% drop in fake ticket claims |
| Cross-promotion with other Swish features | 20% of SL users now use Swish for bills |
| Future-proofing for CBDC integration | Potential to become a hybrid platform |
What This Means Going Forward
Swish’s next frontier lies in cross-border expansion and regulatory evolution. While Sweden’s banking sector remains consolidated, neighboring countries have fragmented systems that could test Swish’s scalability. Norway’s Vipps and Denmark’s MobilePay are direct competitors, but Swish’s advantage is its bank-backed trust. If it can replicate its model in Finland or the Baltics, it could become the dominant force in Northern Europe’s digital economy. The challenge? Avoiding the pitfalls of over-reliance on a single market. The rise of central bank digital currencies (CBDCs) adds another layer. The European Central Bank’s digital euro project could force Swish to adapt—or risk becoming a niche player. Some analysts suggest Swish may pivot to a hybrid model, where it acts as a bridge between commercial and central bank money. The swish application’s ability to innovate without losing its core simplicity will determine whether it remains a leader or gets left behind.
Conclusion
The swish application didn’t invent instant payments, but it perfected the art of making them invisible. By solving the last-mile problem—getting money from one person to another without friction—it didn’t just disrupt banking; it reshaped social interactions. From splitting a pizza to paying rent, Swish became the default, not because of aggressive marketing, but because it worked better than anything before it. Its story offers a blueprint for fintech: collaboration over competition, simplicity over complexity, and trust over hype. As other regions watch Sweden’s cashless transition, the lessons are clear. The swish application succeeded because it understood that technology should serve life, not the other way around. Now, the question is whether the rest of the world can learn from its example—or if Swish itself will need to evolve to stay ahead.Comprehensive FAQs
Q: Is Swish only available in Sweden?
A: While Swish originated in Sweden and remains most widely used there, it has expanded to Norway and Denmark through partnerships. However, its core functionality is still optimized for the Swedish banking system. Cross-border transfers are possible but limited compared to domestic use.
Q: Can I use Swish without a Swedish bank account?
A: No. Swish requires a linked Swedish bank account (or a Nordic account in some cases). Non-residents can use it if their bank participates, but the app isn’t designed for international users without local banking ties.
Q: How does Swish make money if transactions are free?
A: Swish itself doesn’t charge for peer-to-peer transfers, but banks earn interchange fees on merchant transactions (e.g., buying coffee). The app also generates revenue through premium features like travel insurance, loyalty programs, and data analytics sold to participating banks.
Q: What happens if Swish shuts down?
A: Unlikely in the short term, but if Swish were to cease operations, users would lose access to funds tied to the app. However, since all transactions are linked to real bank accounts, money isn’t "lost"—just inaccessible through Swish. The Swedish banks have contingency plans to migrate users to alternative systems.
Q: Can Swish be used for business invoicing?
A: Yes. Many Swedish businesses now accept Swish as a payment method, often via QR codes or direct invoicing. The app also offers tools for freelancers and small businesses to track payments and send automated reminders.
Q: Is Swish secure against fraud?
A: Swish employs two-factor authentication, transaction limits, and real-time fraud monitoring. However, users must remain vigilant against phishing scams (e.g., fake "Swish support" calls). The app’s security depends on both its technology and user awareness.
Q: Will Swish integrate with central bank digital currencies (CBDCs)?
A: Speculation suggests Swish could become a bridge for the EU’s digital euro or similar CBDCs, but no official plans exist. The app’s bank-backed model makes it a strong candidate for hybrid systems, though regulatory hurdles remain.
