
The Complete Overview of the Survey of Consumer Finances 2022 Net Worth Percentiles 90th 95th
The 2022 Survey of Consumer Finances, conducted by the Federal Reserve, is the most authoritative snapshot of U.S. household wealth distribution in a decade. Unlike income surveys, which measure annual earnings, the SCF tracks net worth—the sum of assets minus liabilities—providing a clearer picture of long-term financial health. The 90th and 95th percentiles serve as critical dividing lines: the 90th percentile represents households with net worth in the top 10%, while the 95th captures the top 5%. These thresholds aren’t arbitrary; they correspond to households that have navigated systemic advantages—inheritance, high-earning careers, or favorable tax policies—to accumulate wealth far beyond the median. The data reveals that at the 90th percentile, the typical household’s net worth is driven by a mix of home equity (often in high-appreciation markets), retirement accounts, and diversified investments. By the 95th percentile, however, the composition shifts dramatically. Real estate holdings balloon—think primary residences in coastal cities, vacation properties, or commercial real estate—and financial assets (stocks, mutual funds, private equity) dominate. The SCF also highlights a generational divide: households headed by individuals aged 65+ account for a disproportionate share of wealth at these levels, while younger high-net-worth individuals (under 45) rely more heavily on human capital—earnings from high-paying professions—rather than liquid assets.Historical Background and Evolution
Wealth inequality in America has long been a defining feature of the economy, but the SCF’s periodic measurements have sharpened the focus on how the top percentiles have fared over time. The 2022 data must be read against the backdrop of the 2008 financial crisis, which wiped out trillions in household wealth, and the subsequent recovery, which benefited asset owners far more than wage earners. By 2022, the median net worth of the 90th percentile had rebounded to pre-crisis levels, but the 95th percentile had not only recovered but surged ahead, thanks to a combination of stock market gains, rising home values, and policy changes favoring capital over labor. The pandemic years accelerated these trends. Stimulus checks, low interest rates, and a housing boom inflated asset prices, but the benefits accrued disproportionately to those already wealthy. The SCF shows that the top 1% saw their net worth increase by 18% between 2019 and 2022, while the bottom 50% experienced only a 4% gain. This divergence underscores a structural issue: wealth begets wealth, and the 90th-to-95th percentile range is where that compounding effect becomes most pronounced. Historically, this group has also been the most resilient during downturns, with access to credit, diversified portfolios, and the ability to hold cash when markets falter.Core Mechanisms: How It Works
The mechanics of wealth accumulation at the 90th and 95th percentiles are less about raw income and more about asset allocation, tax optimization, and intergenerational transfer. For the 90th percentile, the path often begins with high-earning careers in law, medicine, or tech, coupled with disciplined saving—automatic retirement contributions, employer-matched 401(k)s, and real estate investments. By the time they reach the 95th percentile, however, the strategies grow more sophisticated: private equity stakes, offshore accounts, and trusts become commonplace. The SCF data shows that the ultra-wealthy are far more likely to hold illiquid assets—business interests, collectibles, or farmland—which appreciate over time but are excluded from traditional measures of liquidity. Tax policy plays a critical role. The 2022 SCF reveals that households at these levels benefit from lower effective tax rates due to deductions, capital gains exemptions, and estate planning tools like grantor retained annuity trusts (GRATs). For example, a household at the 95th percentile might pay an effective federal tax rate of 15-20%, while a middle-class family pays 22-24%. This isn’t just about higher incomes; it’s about structuring wealth to minimize exposure. The data also highlights the role of inherited wealth: nearly 40% of households at the 95th percentile report receiving significant assets from family, compared to just 5% at the 50th percentile.Key Benefits and Crucial Impact
The concentration of wealth at the 90th and 95th percentiles isn’t just a statistical curiosity—it reshapes the economy. These households drive demand for luxury goods, private education, and high-end real estate, creating a feedback loop where their spending fuels industries that further enrich the wealthy. The SCF data shows that the top 5% account for over 30% of consumer spending on high-end services, from private jet charters to boutique consulting. This isn’t just about conspicuous consumption; it’s about reinforcing a class structure where access to certain opportunities is reserved for those who already have wealth. The impact extends to political influence. Wealth at these levels translates to lobbying power, campaign donations, and access to policy networks that shape tax laws, financial regulations, and education reform. The SCF doesn’t track political contributions directly, but the correlation between wealth and influence is well-documented. For instance, households at the 95th percentile are 12 times more likely to donate to political campaigns than the median household, according to separate Federal Election Commission data. This creates a system where the financial elite not only benefit from existing policies but actively shape the rules that sustain their advantage.“Wealth isn’t just money—it’s the ability to convert assets into power. The 90th and 95th percentiles aren’t just about having more; they’re about having the freedom to structure your life around preserving and growing that wealth, generation after generation.” — Edward N. Wolff, Professor of Economics at NYU and author of House of Debt
Major Advantages
- Asset diversification: Households at these levels hold portfolios spanning real estate, private equity, and alternative investments, reducing exposure to market volatility.
- Tax efficiency: Access to sophisticated tax strategies—like step-up in basis, installment sales, or charitable remainder trusts—drastically lowers effective tax burdens.
- Intergenerational wealth transfer: Trusts, family limited partnerships, and gifting strategies ensure wealth persists across generations with minimal erosion.
- Exclusive opportunity access: Membership in private clubs, networks, and industries (e.g., venture capital, hedge funds) that offer unparalleled returns.
Comparative Analysis
| Metric | 90th Percentile | 95th Percentile |
|---|---|---|
| Median Net Worth (2022) | $1.7 million | $5.2 million |
| Primary Wealth Driver | Home equity + retirement accounts | Real estate + financial assets (stocks, private equity) |
| Effective Federal Tax Rate | ~22-25% | ~15-20% |
Future Trends and Innovations
The next decade will likely see further concentration of wealth at the 90th and 95th percentiles, driven by technological disruption and policy shifts. Artificial intelligence and automation may increase productivity but could also widen the gap between high-skilled workers and the rest, pushing more households into the top percentiles. The SCF data suggests that households with advanced degrees (particularly in STEM) are overrepresented at these levels, and as AI creates new high-value professions, this trend may accelerate. Policy changes could either exacerbate or mitigate these dynamics. Proposals to reform capital gains taxes, close loopholes in estate planning, or expand the social safety net could reshape the landscape. However, given the political influence of the ultra-wealthy, significant reforms remain unlikely without external pressure. Meanwhile, innovations like decentralized finance (DeFi) and tokenized assets may offer new avenues for wealth accumulation—but these tools are currently accessible only to those with existing capital to invest.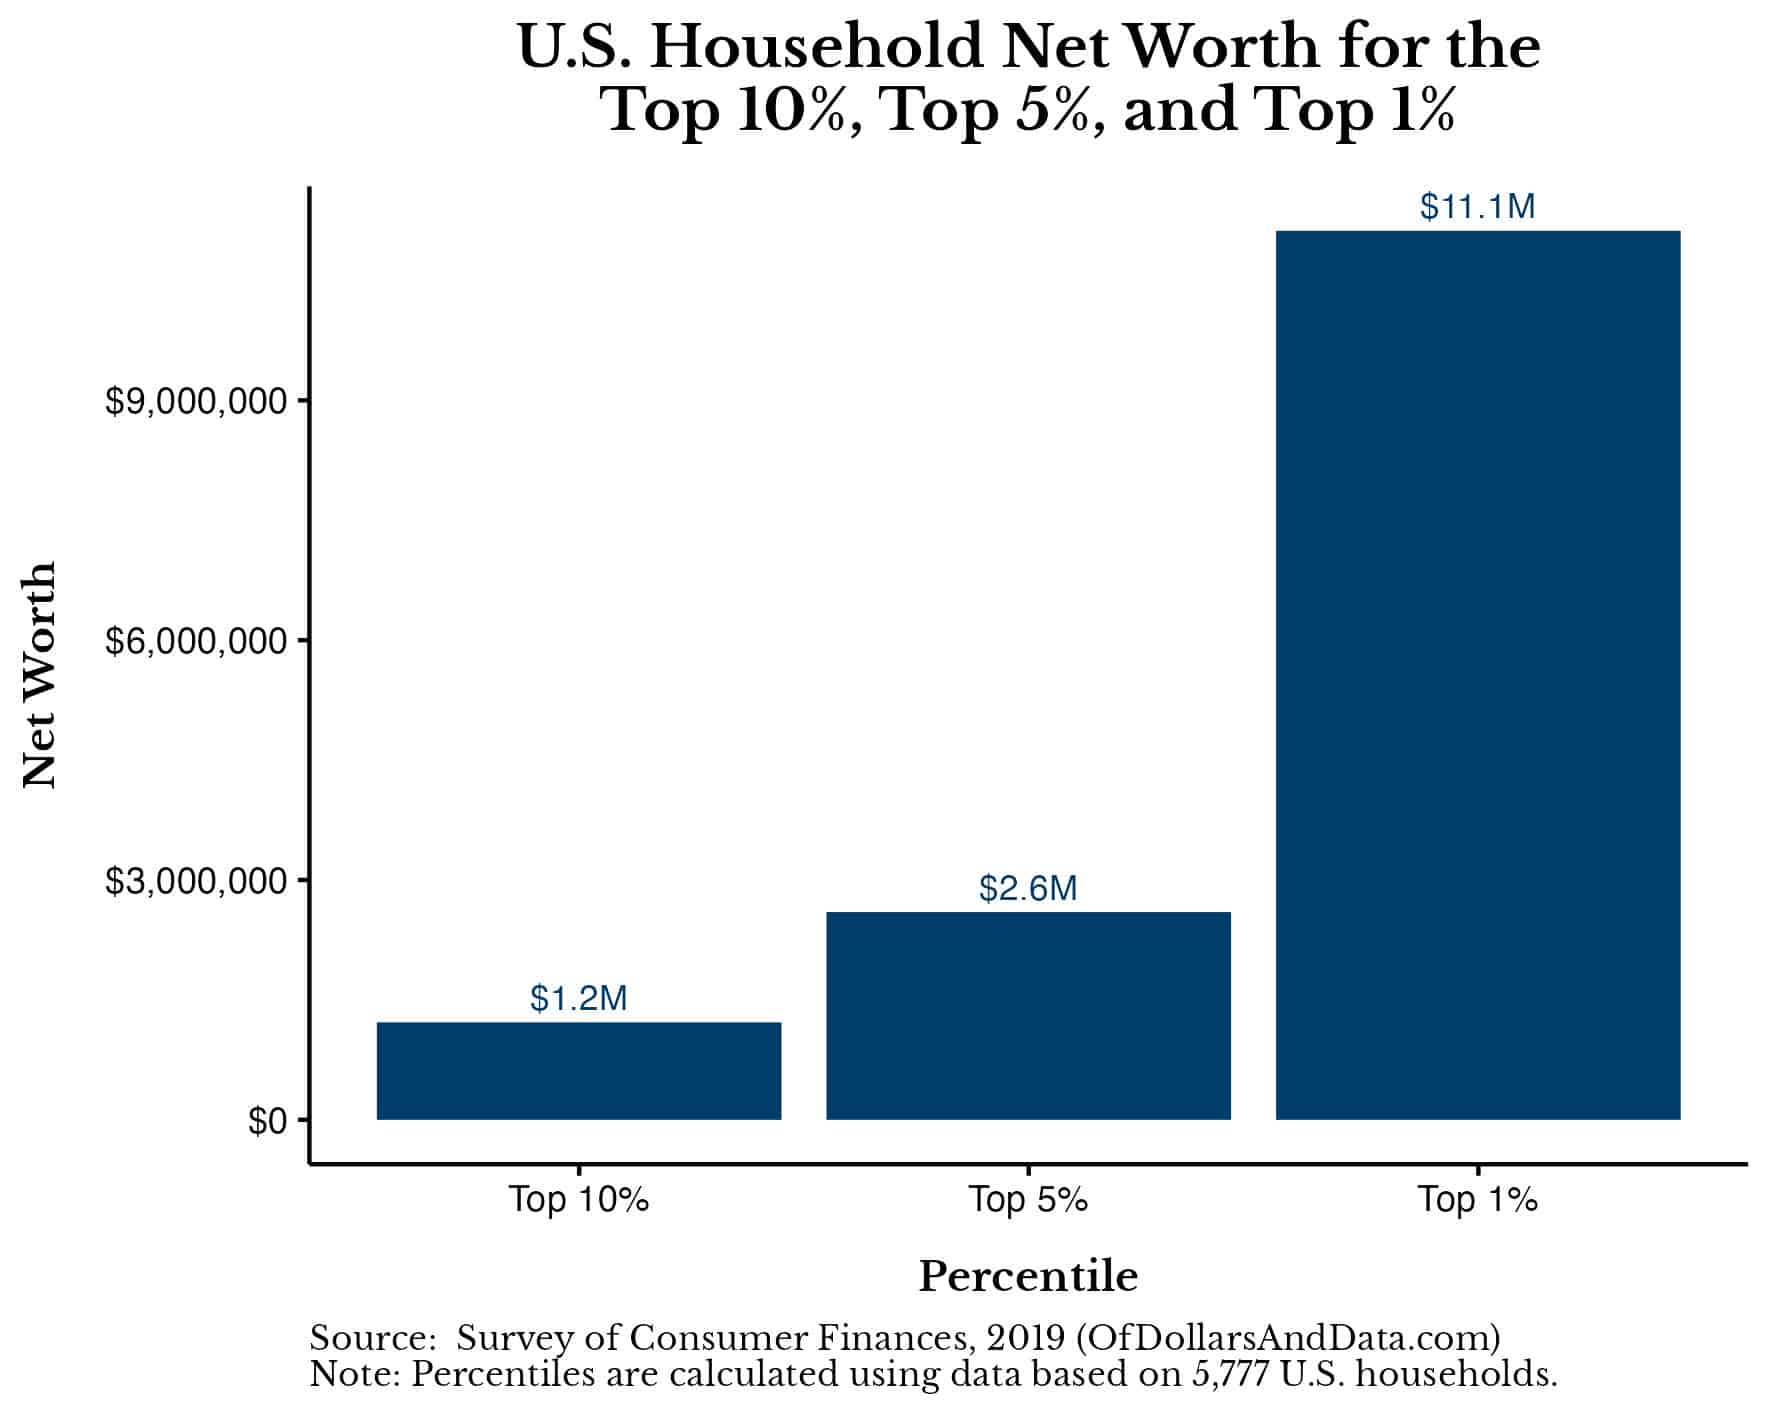
Conclusion
The 2022 Survey of Consumer Finances offers more than a snapshot of wealth distribution; it reveals the mechanisms that sustain inequality. The 90th and 95th percentiles aren’t just statistical cutoffs—they mark the boundary between financial security and true economic power. For households at these levels, wealth is a self-reinforcing cycle: access to better education, lower tax rates, and exclusive investment opportunities ensures that advantages persist across generations. The challenge for policymakers, economists, and citizens alike is whether this system can be reformed without undermining the very engines of growth that have propelled these households to the top. The data is clear: the gap between the 90th and 95th percentiles is widening, and the strategies that define wealth at these levels are becoming more entrenched. Without deliberate intervention, the future of American wealth distribution may look even more skewed than today.Comprehensive FAQs
Q: How does the 90th percentile compare to the top 1%?
The 90th percentile includes households with net worth between approximately $1.7 million and $3.5 million, while the top 1% starts at around $10.3 million. The 90th percentile is a broader group that includes many high-earning professionals but lacks the extreme wealth concentration of the top 1%, where fortunes often exceed $10 million.
Q: Can someone reach the 95th percentile without inheriting wealth?
Yes, but it requires an exceptional combination of high income, disciplined saving, and access to high-return investments. Many at the 95th percentile built wealth through careers in law, medicine, or tech, combined with real estate and stock market investments. However, inheritance or family networks often provide a significant boost.
Q: How do tax policies affect wealth at these percentiles?
Tax policies disproportionately favor the wealthy at these levels. Lower capital gains rates, deductions for investment expenses, and estate tax exemptions (currently $12.92 million per individual) allow households at the 90th and 95th percentiles to retain a larger share of their wealth. For example, a 20% capital gains rate versus a 37% ordinary income tax rate can mean saving hundreds of thousands annually on asset sales.
Q: What’s the biggest risk to maintaining wealth at these percentiles?
The biggest risks are market downturns, poor asset allocation, and unexpected liabilities (e.g., lawsuits, divorce). However, households at these levels have tools to mitigate risks: diversified portfolios, insurance, and legal structures like LLCs. The SCF shows that even during recessions, the top 5% tend to recover faster due to liquidity and access to credit.
Q: How does the 2022 SCF data differ from previous surveys?
The 2022 survey reflects the post-pandemic recovery, where asset prices (stocks, real estate) surged, benefiting the wealthy more than wage earners. Unlike past downturns, this recovery was driven by monetary policy (low interest rates) and tech-sector gains, which disproportionately favored high-net-worth households. The data also shows a slower wealth recovery for younger generations compared to previous cycles.
Q: Are there any emerging trends that could disrupt wealth at these levels?
Yes, several factors could reshape wealth dynamics: rising interest rates (which could cool real estate and stock markets), increased scrutiny on tax loopholes, and the rise of alternative assets (cryptocurrency, NFTs). However, these trends may also create new opportunities for the wealthy to diversify further, rather than eroding their advantage.
