Common Myths About Personal Capital App Net Worth
The first myth is that Personal Capital’s net worth calculation is an exact science. In reality, the app’s figures are a blend of hard data (verified account balances) and educated guesses (estimated home values, retirement projections). Users often assume that if their 401(k) shows $250,000 in the app, that’s the precise amount—but behind the scenes, Personal Capital may be applying internal assumptions about asset allocation or future growth rates. These estimates can shift based on market conditions, yet the app presents them as static benchmarks. The second misconception is that a higher net worth number automatically means better financial health. A six-figure net worth could stem from a single overvalued asset (like a home in a hot market) while liquidity remains dangerously low. The app doesn’t distinguish between useful wealth (cash, low-cost investments) and illusionary wealth (high-maintenance assets). Another persistent belief is that Personal Capital’s net worth tracker is free. While the basic app is indeed free to use, the company monetizes access to its financial advisors—a service that can cost thousands annually. Users who rely solely on the net worth feature may not realize they’re opting into a funnel designed to upsell them. Even the "free" version requires linking bank accounts, which some view as an invasion of privacy. The app’s terms of service allow it to share anonymized (or sometimes not-so-anonymized) data with third parties, raising questions about who truly owns the insights generated by the net worth dashboard.Myth 1: The net worth figure is always accurate
Personal Capital’s net worth isn’t a bank statement—it’s a composite. For verified accounts (like brokerage or retirement holdings), the numbers are pulled directly from financial institutions, but for assets like real estate, the app relies on user-reported values or automated estimates. These estimates can drift over time, especially in volatile markets. For example, a user might input their home’s purchase price in 2015, but Personal Capital’s algorithm may adjust the valuation based on Zillow data or local trends. The result? A net worth figure that feels authoritative but isn’t set in stone. The inaccuracy extends to retirement projections. Personal Capital’s "retirement planner" uses assumptions like a 7% annual return—an average that doesn’t account for sequence-of-returns risk or inflation spikes. Users who take these projections at face value may overestimate their future wealth, only to face reality when markets underperform. The app doesn’t disclose the full range of possible outcomes, leaving users to assume the best-case scenario is the most likely.Myth 2: A rising net worth means you’re doing everything right
A net worth increase doesn’t necessarily reflect smart financial decisions. It could simply mean you bought a more expensive home or saw a stock market rally. Personal Capital’s dashboard doesn’t contextualize why the number changed—whether it’s due to disciplined saving, a one-time windfall, or leverage (like a mortgage). Without this context, users might feel compelled to chase higher returns or take on debt to inflate their net worth, which can backfire. The app also ignores non-financial factors that affect wealth, such as health, career stability, or family obligations. A user with a high net worth but no emergency fund might feel secure, only to face a liquidity crisis. Personal Capital’s net worth metric treats wealth as a monolith, not a collection of assets with different risk profiles. This oversimplification can lead to poor decisions, like selling investments during a downturn to "protect" the net worth number.Myth 3: The app is neutral—it just shows the numbers
Personal Capital’s design is deliberately persuasive. The app highlights gains in green, nudges users toward "optimal" asset allocations, and even suggests when to take action (like rebalancing or rolling over a 401(k)). These features aren’t neutral—they’re shaped by the company’s incentives. For instance, the app may recommend consolidating accounts to reduce fees, but doing so could limit access to certain investment options or perks tied to specific institutions. Privacy is another area where neutrality breaks down. While Personal Capital claims to encrypt data, users must trust the company to handle sensitive financial details responsibly. There have been instances where third-party vendors (used by Personal Capital) have exposed user data, raising questions about who has access to the net worth insights generated by the app. The illusion of objectivity is further eroded by the fact that the free version is essentially a lead generator for paid advisory services.
What Holds Up to Scrutiny
At its core, Personal Capital’s net worth feature excels at aggregation. Few tools can pull together disparate accounts—from HSA balances to private business holdings—into a single, real-time figure. This is particularly useful for users with complex financial lives, such as entrepreneurs or those with multiple retirement accounts. The app’s ability to track progress over time (via historical net worth charts) also provides a clear visual of how lifestyle choices, investments, and market conditions interact. What’s less debated is the app’s utility for tax-loss harvesting and fee analysis. Personal Capital’s tools can identify high-fee investments or suggest tax-efficient strategies, which are tangible benefits beyond the net worth dashboard. For users who treat the app as a financial coach rather than a gospel, these features add real value. The key is recognizing that the net worth number is a starting point, not an endpoint."The net worth figure is like a car’s speedometer—it tells you where you are, but not whether you’re on the right road. The real question is what you do with that number." —Certified Financial Planner (CFP®) reviewing Personal Capital’s tools
| Common Belief | What the Evidence Says |
|---|---|
| The net worth number is precise. | It’s accurate for verified accounts but relies on estimates for assets like real estate. |
| Checking net worth daily improves financial health. | Frequent monitoring can increase stress; quarterly reviews are often sufficient. |
| Personal Capital’s projections are reliable. | They’re based on assumptions that may not hold in downturns or high-inflation periods. |
| The app is free and unbiased. | It monetizes users through advisory services and may nudge behavior toward paid offerings. |
Why the Confusion Persists
The primary reason for confusion is Personal Capital’s dual role as both a tool and a service provider. The app’s free tier offers powerful features, but the underlying business model is built on converting users to paid advisory—creating a conflict of interest that’s easy to overlook. Users assume the net worth dashboard is purely informational, when in reality, it’s part of a larger ecosystem designed to keep them engaged (and potentially paying). Cultural factors also play a role. In an era where personal finance is increasingly gamified (think: "leveling up" your net worth), apps like Personal Capital tap into the desire for instant gratification. The net worth number becomes a status symbol, reinforcing the idea that wealth is something to be chased rather than managed. This mindset ignores the fact that financial health is multi-dimensional—debt levels, cash flow, and risk tolerance matter just as much as the bottom-line figure.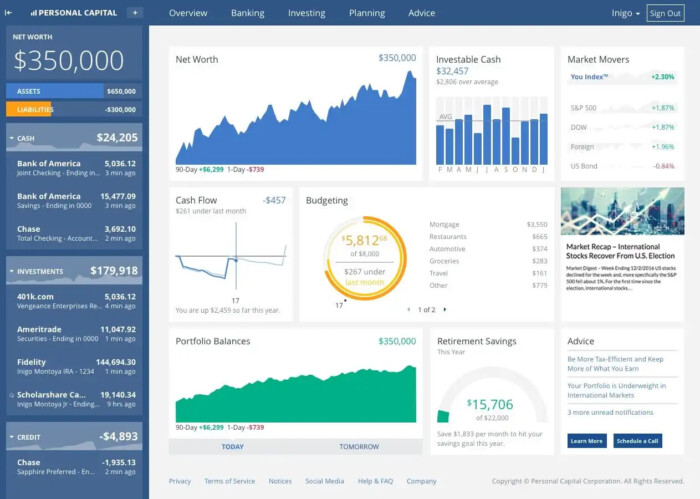
Conclusion
Personal Capital’s net worth feature is a double-edged sword. On one hand, it democratizes access to financial insights that were once reserved for high-net-worth clients. On the other, it risks turning wealth management into a numbers game, where the focus shifts from goals to metrics. The app’s strength lies in its ability to surface data; its weakness is in how that data is presented—and what it leaves unsaid. For users who treat the net worth figure as a tool for reflection rather than a measure of success, Personal Capital can be invaluable. But those who fixate on the number itself may find themselves chasing an illusion. The best approach? Use the app to track progress, but don’t let it dictate your financial psychology. After all, a net worth is only as meaningful as the decisions it inspires—and the ones it obscures.Comprehensive FAQs
Q: How often does Personal Capital update net worth?
Net worth updates in real time for linked accounts (like brokerage or bank balances), but estimated values (such as home equity) may refresh weekly or monthly, depending on data sources. Market fluctuations can trigger immediate recalculations for investment-heavy portfolios.
Q: Can I exclude certain accounts from my net worth calculation?
Yes. Personal Capital allows users to hide specific accounts (e.g., a high-fee investment or a loan they don’t want to track). However, excluded accounts won’t appear in the dashboard, which could skew the overall picture if not managed carefully.
Q: Does Personal Capital’s net worth include cryptocurrency?
No. The app doesn’t natively support crypto holdings, though users can manually add them as "other assets." This creates a gap for those with significant digital asset portfolios, as the net worth figure won’t reflect real-time crypto valuations.
Q: How does Personal Capital handle joint accounts?
Joint accounts are aggregated into a single net worth figure by default, which can be useful for couples but may obscure individual financial health. Users can opt to view separate net worth calculations for each person linked to the account.
Q: Is Personal Capital’s net worth tax-adjustable?
The app doesn’t factor in tax liabilities (like capital gains or property taxes) into the net worth calculation. Users must manually adjust for taxes if they want a more accurate "after-tax" net worth figure, especially for high-value assets.
Q: Can I use Personal Capital’s net worth tool without linking my bank?
Technically yes, but the app’s functionality is severely limited. Without linked accounts, you’ll only see manually entered data, losing access to features like fee analysis, retirement planning, and real-time balance tracking.
Q: Does Personal Capital’s net worth include debts like student loans?
Yes, but only if you manually input them. The app doesn’t pull student loan balances directly from lenders, so users must add these liabilities separately to ensure an accurate net worth calculation.
Q: How does Personal Capital’s net worth compare to Mint or YNAB?
Unlike Mint (which focuses on budgeting) or YNAB (which emphasizes cash flow), Personal Capital’s net worth tool is designed for investors and high-net-worth individuals. It offers deeper asset analysis and retirement planning, but lacks the granular expense tracking found in other apps.
