The Complete Overview of the Net Worth of Average 30-Year-Olds
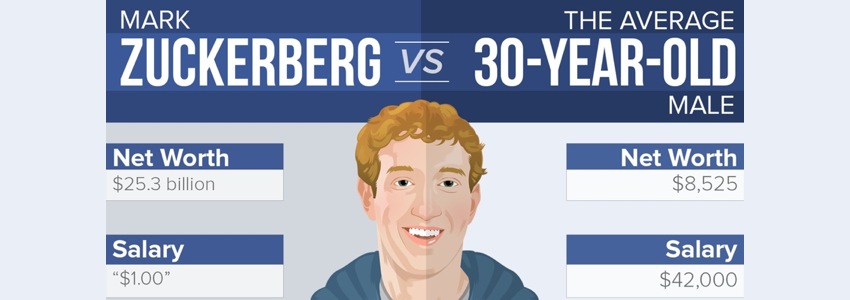
The net worth of average 30-year-olds is a barometer of economic health, reflecting not just individual financial habits but systemic forces that stretch back generations. In the U.S., Federal Reserve data suggests that by age 30, the median net worth sits at roughly $80,000, with the top 10% nearing $300,000+. However, these figures mask critical divides: Black and Hispanic 30-year-olds, for instance, have median net worths half that of white peers, a disparity rooted in historical redlining, wealth gaps, and unequal access to education and credit. Globally, the picture shifts dramatically—while a 30-year-old in Germany might have net worth figures around €120,000, their counterpart in Brazil could struggle with negative net worth due to inflation and currency volatility. What’s often overlooked is how liquidity and asset types distort these numbers. A 30-year-old with a paid-off home in a depreciating market might appear wealthier on paper than one with student loans but a diversified investment portfolio. The net worth of average 30-year-olds is also a moving target: in 2000, a 30-year-old’s median net worth was nearly 50% higher in real terms than today, adjusted for inflation. The decline traces back to the dot-com crash, the 2008 crisis, and the subsequent erosion of middle-class wages—factors that have reshaped what “average” even means.Historical Background and Evolution
The trajectory of the net worth of average 30-year-olds has been shaped by three seismic economic shifts. The first came in the 1980s, when deregulation and financialization created asset bubbles that disproportionately benefited older generations. By the time millennials turned 30 in the 2010s, they inherited an economy where homeownership rates for young adults had plummeted from 49% in 1980 to 36% by 2020. The second blow was the 2008 crisis, which wiped out trillions in household wealth and left a generation entering the workforce during a period of mass unemployment. The third, more insidious trend, was the student debt explosion: today, over 70% of 30-year-olds in the U.S. hold student loans, with average balances exceeding $30,000, a figure that directly siphons from potential net worth accumulation. Internationally, the story varies. In Nordic countries, strong social safety nets and universal education have allowed 30-year-olds to build net worth through public sector jobs, real estate, and pension contributions—median figures often exceed $150,000. Meanwhile, in emerging markets, the net worth of average 30-year-olds is frequently tied to informal economies, remittances, or family wealth, where traditional financial metrics fail to capture true economic agency. The post-2020 recovery, marked by pandemic stimulus and remote work flexibility, has created a two-tiered recovery: those in tech, healthcare, or skilled trades saw net worth surge, while service workers and gig economy participants stagnated.Core Mechanisms: How It Works
The net worth of average 30-year-olds isn’t determined by salary alone but by a triad of factors: income volatility, debt leverage, and asset allocation. Take income: a 30-year-old earning $70,000 in Texas may have a higher net worth than a $90,000 earner in California due to housing costs and tax burdens. Then there’s debt—student loans, auto payments, and credit card balances can erode net worth by 20–40% for this demographic. Finally, asset choices matter: those who’ve invested in index funds, real estate, or side businesses see compounding effects, while others remain stuck in liquidity traps like high-yield savings accounts or underperforming retirement plans. The mechanics also differ by gender. Women, on average, enter their 30s with 30% less net worth than men, a gap attributed to the wage gap, career interruptions for childcare, and longer lifespans that reduce retirement savings windows. For LGBTQ+ individuals, the picture is even more fragmented: those who came out later in life may face discrimination in hiring or promotions, while early-career transitions can disrupt wealth-building trajectories. The net worth of average 30-year-olds, then, is less about individual failure than structural barriers that vary by identity, geography, and economic context.Key Benefits and Crucial Impact
Understanding the net worth of average 30-year-olds isn’t just an academic exercise—it’s a lens into the health of an economy. When this cohort’s wealth stagnates, it signals broader issues: declining social mobility, eroding middle-class stability, and the hollowing out of traditional wealth vehicles. Policymakers and economists track these figures to gauge whether interventions—like student debt relief or first-time homebuyer programs—are working. For individuals, it’s a wake-up call: if the median net worth at 30 is shrinking, it means delaying life milestones (marriage, kids, retirement) is no longer optional but necessary. The impact extends beyond personal finance. Cities with high concentrations of 30-year-olds with low net worth often see lower voter turnout, higher crime rates, and slower economic growth—a feedback loop where financial stress breeds civic disengagement. Conversely, regions where this demographic thrives—like Austin, Berlin, or Singapore—attract talent, spur innovation, and see higher entrepreneurship rates. The net worth of average 30-year-olds, in short, is a leading indicator of societal resilience.“Net worth at 30 isn’t just about money—it’s about agency. If you’re not building wealth by then, you’re not just poor; you’re disempowered in ways that ripple across generations.” — Rachel Schneider, economist and author of The Wealth Divide
Major Advantages
Despite the challenges, the net worth of average 30-year-olds offers critical insights for those who act on them:- Time is the ultimate compounding tool. A 30-year-old with $50,000 in net worth who invests $500/month in index funds could see that grow to $1.2 million by 65, assuming 7% annual returns. The math favors early starters.
- Debt restructuring is possible. Strategies like refinancing student loans or negotiating medical debt can free up $200–$500/month, accelerating net worth growth.
- Alternative assets outperform traditional ones. For those priced out of real estate, peer-to-peer lending, fractional investing, or rental arbitrage can build wealth faster than savings accounts.
- Geographic arbitrage works. Moving to a lower-cost area (or even a different country) can double disposable income, directly boosting net worth.
- Side hustles scale. The net worth of average 30-year-olds in gig economies often outpaces traditional 9-to-5 earners—freelancers and digital nomads frequently see 20–50% higher net worth growth than their salaried peers.
- Network effects matter. Wealth begets wealth. A 30-year-old with one high-net-worth mentor is more likely to access investment opportunities, job referrals, and financial education that others miss.

Comparative Analysis
| Metric | U.S. (Median) | Germany (Median) | India (Urban, Median) | Singapore (Median) |
|---|---|---|---|---|
| Net Worth at 30 | $80,000–$100,000 | €120,000–€150,000 | ₹10–₹20 lakh (~$1,200–$2,400) | $150,000–$200,000 |
| Primary Wealth Driver | Homeownership (if possible), stocks | Public pensions, real estate | Family wealth, remittances | CPF savings, real estate |
| Biggest Wealth Drag | Student debt, healthcare costs | High taxes, low wage growth | Inflation, job instability | Housing costs, education fees |
| Outlier Strategy | Tech equity, side hustles | Public sector jobs, inheritance | Family business, real estate | Government bonds, ETFs |
Future Trends and Innovations
The net worth of average 30-year-olds is poised for disruption from three fronts: technology, policy, and cultural shifts. AI and automation will polarize earnings—those with high-skill tech roles may see net worth surge, while others face job obsolescence, widening the gap. Policy-wise, universal basic income experiments and student debt jubilees could either level the playing field or deepen dependency on government handouts. Culturally, the rise of “financial independence” movements (FIRE) is pushing 30-year-olds to retire early, but this remains accessible only to the top 10% of earners. What’s less discussed is how decentralized finance (DeFi) and crypto might reshape wealth accumulation. For early adopters, tokenized assets and yield farming could outpace traditional investments—but the risk of volatility remains high. Meanwhile, climate migration may force 30-year-olds to relocate for economic survival, creating a new class of “eco-nomads” whose net worth is tied to adaptability over geography. The biggest unknown? Whether corporate wage stagnation will persist, or if the labor shortage finally forces employers to restore mid-career wage growth.
Conclusion
The net worth of average 30-year-olds is a report card on economic opportunity—one that grades societies as much as individuals. The data shows a generation caught between legacy systems that no longer serve them and new tools they’re still learning to wield. The good news? The rules aren’t fixed. A 30-year-old today has more financial tools, global mobility, and alternative income streams than any previous generation. The bad news? Access to these tools is uneven, and the cost of failure—lost decades, eroded savings, or lifelong debt—has never been higher. The path forward isn’t about hitting arbitrary net worth targets but about redefining what wealth means. For some, it’s homeownership; for others, financial freedom before 40; for many more, it’s simply avoiding poverty. The net worth of average 30-year-olds will keep evolving—but whether it trends upward or downward depends on policy choices, technological access, and collective action. The clock is ticking.Comprehensive FAQs
Q: What’s the biggest mistake 30-year-olds make when tracking net worth?
The most common error is ignoring illiquid assets—like a home or retirement accounts—while fixating on liquid cash. Many also underestimate debt, counting only credit cards but overlooking student loans or medical debt. Finally, not adjusting for inflation leads to a false sense of progress if wages stagnate while costs rise.
Q: Can a 30-year-old with no savings start building net worth?
Absolutely—but the strategy shifts. Focus on high-ROI debt elimination (e.g., refinancing loans), micro-investing (apps like Acorns or Stash), and skill-based side income (freelancing, tutoring). Even $50/month invested in low-cost index funds can grow to $100,000+ by 60 with compounding. The key is consistency over amount.
Q: Does getting married or having kids at 30 hurt net worth?
Not necessarily—it depends on the partnership’s financial habits. Couples who combine incomes, share expenses, and invest jointly often see higher net worth growth than single peers. Kids, however, delay wealth accumulation for many due to childcare costs and career interruptions. The net worth of average 30-year-olds with children is 20–30% lower than childless peers, but this gap narrows over time if savings strategies adapt.
Q: How does student debt impact the net worth of average 30-year-olds?
Student loans directly reduce net worth by $30,000–$50,000 on average, but the indirect effects are worse. Borrowers save less for retirement, delay home purchases, and earn less due to lower credit scores. A 30-year-old with $40,000 in student debt may have half the net worth of a peer with no debt, even if their salaries are similar. Income-driven repayment plans can help, but they extend payment timelines to 20–25 years.
Q: Can you build meaningful net worth without a college degree?
Yes—but the path is skill-dependent and riskier. Tradespeople, tech bootcamp grads, and entrepreneurs often outpace college grads in net worth by age 30 if they monetize high-demand skills (e.g., coding, electrician work, sales). However, job stability and benefits (healthcare, retirement matching) are harder to secure without a degree. The net worth of average 30-year-olds without degrees is 15–25% lower, but outliers in real estate flipping, freelancing, or niche crafts can surpass peers with degrees.
Q: How does geography affect the net worth of average 30-year-olds?
Location is the single biggest variable. A 30-year-old in Houston or Dallas may have 30% higher net worth than one in San Francisco or New York due to housing costs. Rural areas offer lower expenses but fewer opportunities, while global cities concentrate wealth but require higher earnings to break even. Remote work has compressed this gap, but tax burdens, local wage laws, and cost of living still dictate whether a $60,000 salary translates to $80,000 in net worth (e.g., Midwest) or $40,000 (e.g., coastal cities).
Q: What’s the fastest way to increase net worth by age 30?
Combine debt destruction, income scaling, and asset leverage:
- Eliminate high-interest debt (credit cards, payday loans) first.
- Increase income by 20–30% via promotions, side gigs, or upskilling.
- Invest aggressively—even $300/month in a tax-advantaged account can grow to $200,000+ by 60.
- Leverage real estate (house hacking, rental properties) if local markets allow.
- Avoid lifestyle inflation—live below your means even as income rises.
