
Where It All Began
The origins of the net worth net worth calculator trace back to the late 1990s, when personal finance software like Quicken and Microsoft Money introduced basic asset-debt tracking. These programs were bulky, required manual data entry, and were primarily used by accountants or finance enthusiasts. The concept of a "net worth" had existed for decades—it was a staple in financial planning—but the idea of a digital tool to calculate it in real time was novel. Early versions were little more than glorified ledgers, but they planted the seed for what would become a cornerstone of modern financial literacy. The real breakthrough came in the mid-2000s, when bloggers and DIY finance communities started sharing customizable spreadsheets. These weren’t corporate products; they were user-generated hacks, often built on Google Sheets or Excel templates. One of the most influential early examples was a template created by a finance blogger who went by the pseudonym "Mr. Money Mustache." His calculator wasn’t just functional—it was a manifesto. It included fields for "liquid net worth" and "illiquid net worth," forcing users to think critically about what truly mattered. By 2007, these tools had spread to niche forums, where users debated everything from how to value a home to whether to include a wedding ring in the calculation.The Early Signs
The first net worth net worth calculator wasn’t designed for the masses—it was built for the curious. Early adopters were often in their 30s, already frustrated with traditional banking systems. They saw the calculator as a way to hold themselves accountable, a digital ledger that wouldn’t judge them for overspending on avocado toast. The tool’s simplicity was its strength: no jargon, no hidden fees, just a clear snapshot of where you stood. What surprised even its creators was how quickly the calculator became a social tool. Users began posting their net worth updates in forums, not to brag, but to seek advice. A $50,000 net worth might sound impressive to one person and disheartening to another, depending on their location and lifestyle. The calculator didn’t just track numbers—it created a sense of community. For the first time, people realized they weren’t alone in their financial struggles or successes. The tool had evolved from a personal utility into a shared language.The Turning Point
The moment the net worth net worth calculator became mainstream was when it stopped being a niche tool and started being a default feature in financial apps. In 2014, Mint acquired Credit Karma and integrated net worth tracking into its platform, exposing millions to the concept. Suddenly, checking your net worth was as easy as checking your email. The shift from manual input to automated syncing was seismic. Users no longer had to remember to update their calculator—their bank and investment accounts did it for them. This wasn’t just about convenience; it was about normalization. A net worth of $200,000 that once seemed unattainable now had a benchmark. The calculator had moved from the fringes of finance forums to the center of everyday money conversations. It wasn’t just for the wealthy or the frugal—it was for everyone. The turning point wasn’t the tool itself, but the realization that tracking wealth wasn’t just for experts. It was for anyone who wanted to understand their financial health."The first time I saw my net worth update in real time, I felt like I was looking at my life through a different lens. It wasn’t about the number—it was about the story behind it." — A former Mint user, 2015
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1998–2005 | Early personal finance software (Quicken, Money) introduces basic net worth tracking. Manual entry required; primarily used by accountants. |
| 2006–2010 | DIY finance communities share customizable spreadsheets. Net worth calculators become a tool for financial independence bloggers. |
| 2011–2015 | Mobile apps (Mint, Personal Capital) integrate automated net worth tracking. The tool shifts from manual to real-time updates. |
| 2016–Present | AI-driven projections and goal-setting features added. Net worth calculators become embedded in robo-advisors and budgeting apps. |
Lessons From the Journey
- Transparency over secrecy: The rise of the net worth net worth calculator reflected a cultural shift toward open discussions about money, especially among younger generations.
- Automation changed behavior: Real-time updates made tracking habitual, turning what was once a yearly task into a monthly or even weekly check-in.
- Community over isolation: Users began sharing their net worth progress publicly, creating accountability and reducing financial shame.
- Tools evolved with user needs: Early calculators were static; today’s versions predict future growth, align with goals, and even suggest adjustments.
Where Things Stand Today
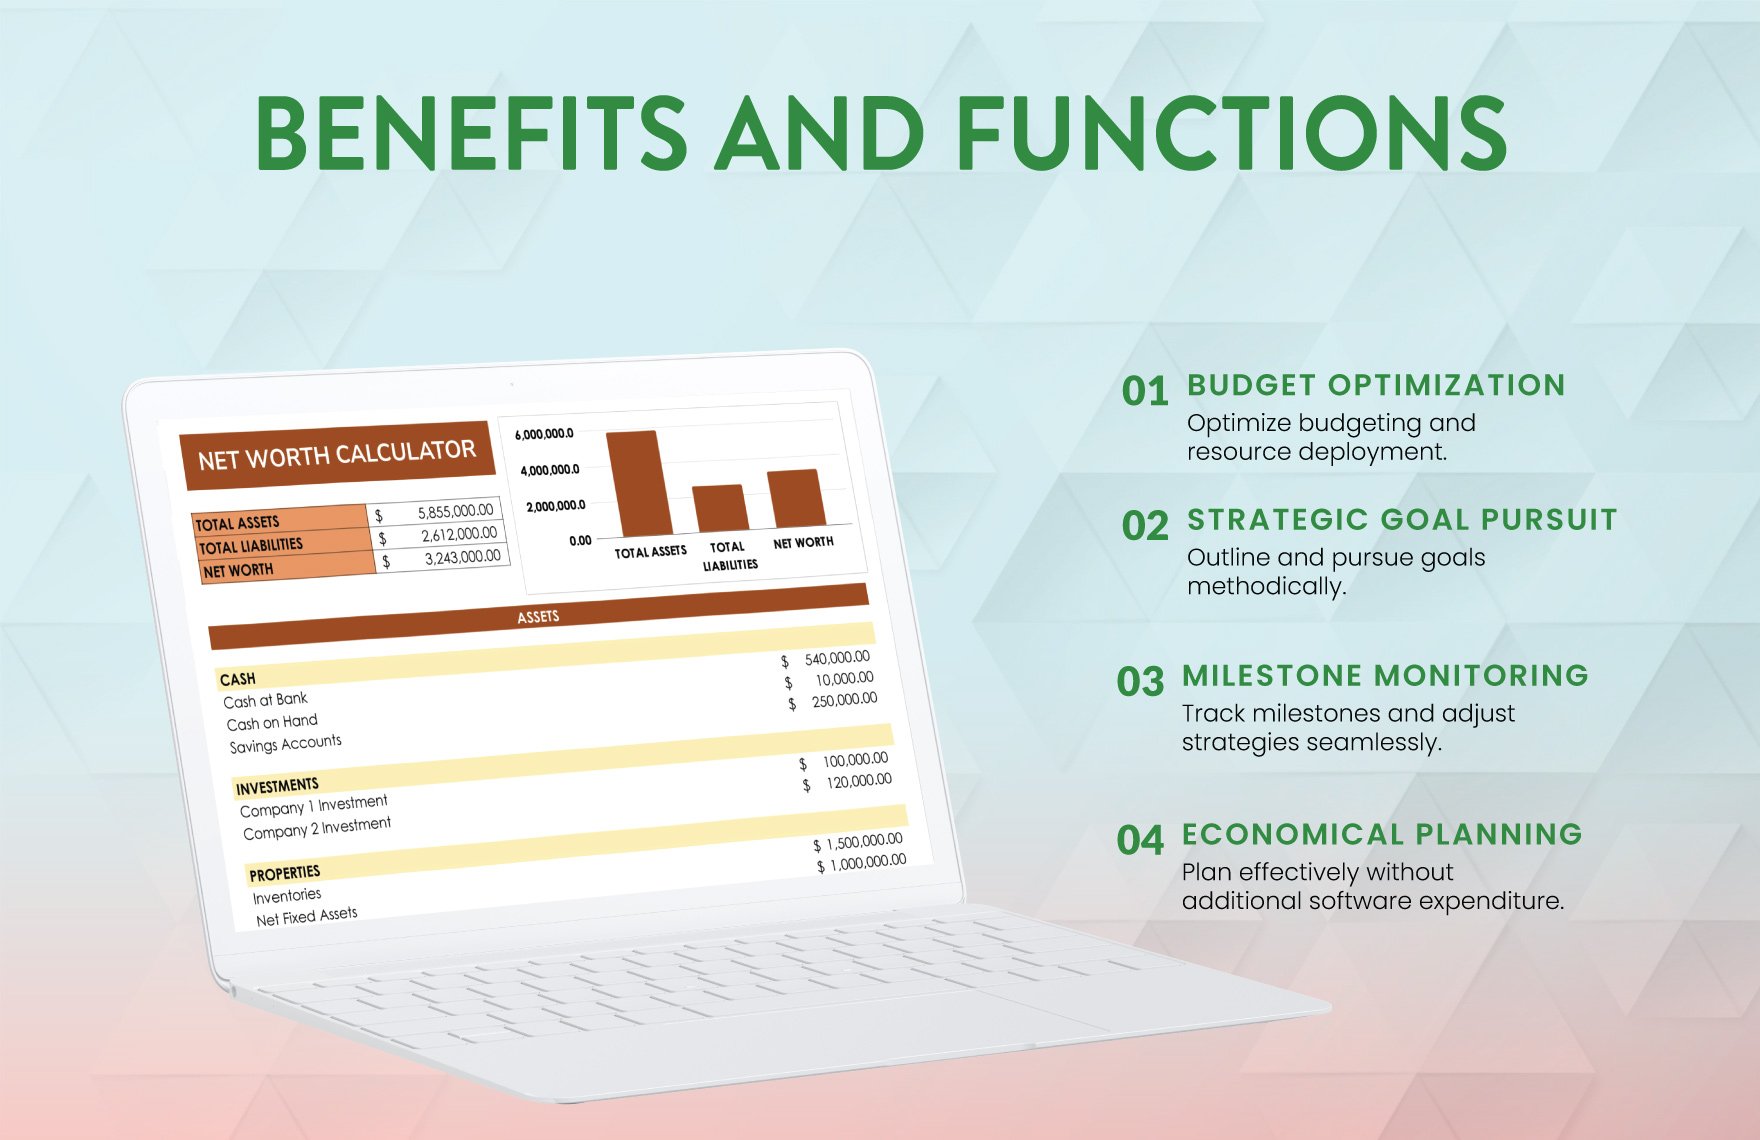
Today’s net worth net worth calculator is unrecognizable from its early days. The tools now integrate with bank accounts, cryptocurrency wallets, and even side hustle income streams. Apps like YNAB (You Need A Budget) and EveryDollar use net worth tracking as a core feature, while robo-advisors like Wealthfront provide personalized insights based on your calculated net worth. The calculator has become so ingrained in financial planning that it’s now a default setting in many budgeting apps. What’s most striking is how the tool has adapted to different lifestyles. For a freelancer, it might track project-based income; for a homeowner, it could factor in property appreciation. The net worth net worth calculator is no longer a one-size-fits-all tool—it’s a customizable dashboard that reflects how people live today. The shift from a simple asset-debt calculation to a dynamic financial snapshot mirrors broader changes in how we think about money: less about what you own, more about what you can do with it.
Conclusion
The evolution of the net worth net worth calculator is more than a story about numbers—it’s about how technology has reshaped our relationship with money. What began as a DIY spreadsheet has become a cornerstone of financial wellness, influencing everything from savings habits to investment decisions. The tool’s journey reflects larger trends: the move toward transparency, the rise of personalized finance, and the democratization of wealth tracking. As these calculators become more sophisticated, the question isn’t just what they can track, but how they can inspire action. The best net worth net worth calculator today doesn’t just show you where you stand—it challenges you to think about where you’re going. And that, more than any feature, is what makes it indispensable.Comprehensive FAQs
Q: How accurate are net worth net worth calculator tools?
The accuracy depends on how well you input your data. Automated tools sync with bank accounts, reducing human error, but they may miss assets like physical property or cryptocurrency unless manually added. For the most precise results, combine automated syncing with periodic manual updates.
Q: Can a net worth net worth calculator help with debt management?
Yes. By tracking both assets and liabilities in real time, these tools highlight debt-to-asset ratios, making it easier to identify areas for improvement. Some calculators even suggest repayment strategies based on your net worth growth.
Q: Are there free net worth net worth calculator options?
Absolutely. Many budgeting apps (e.g., Mint, Personal Capital) offer free versions with basic net worth tracking. For more advanced features, paid tools like YNAB or specialized calculators may be worth the investment.
Q: How often should I update my net worth net worth calculator?
Ideally, monthly—especially if your financial situation changes frequently (e.g., new investments, loans, or income streams). Automated tools make this effortless, but manual users should set reminders.
Q: Can a net worth net worth calculator predict future wealth?
Some modern tools use AI to project potential net worth based on current trends, but these are estimates, not guarantees. For realistic projections, combine calculator data with professional financial advice.
Q: Is tracking net worth only for the wealthy?
No. A net worth net worth calculator is useful at any income level. It helps individuals at all stages—whether saving for a home, paying off student loans, or planning retirement—by providing clarity on their financial progress.
Q: How do I value non-liquid assets (e.g., a home, art collection) in a net worth net worth calculator?
Use current market estimates for liquidation value. For a home, check recent comparable sales; for collectibles, consult appraisals. Some calculators allow custom fields for non-standard assets.
Q: Can a net worth net worth calculator integrate with crypto wallets?
Some newer tools (e.g., Delta, CoinTracker) now sync with crypto exchanges and wallets, automatically updating your net worth as digital asset values fluctuate. Always verify security measures before linking accounts.
