The Short Answers
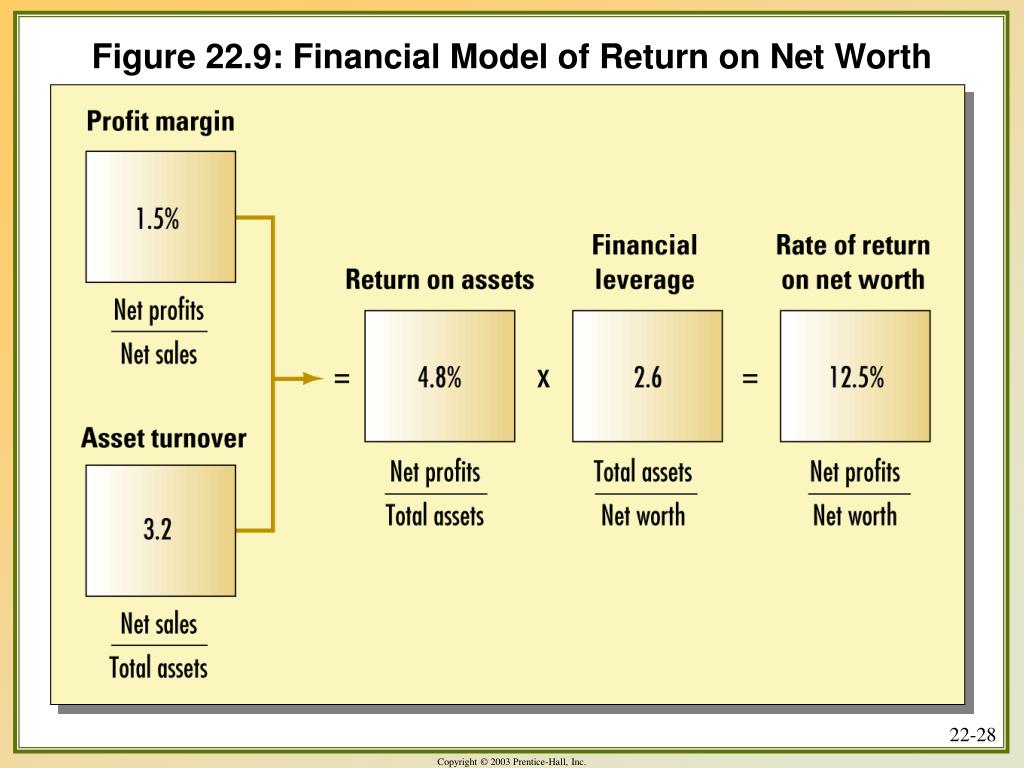
- The net worth model financial is a snapshot of your financial health, calculated by subtracting liabilities from assets.
- It’s used by investors, entrepreneurs, and planners to track progress, optimize taxes, and make high-stakes decisions.
- Your net worth can fluctuate daily due to market changes, but the model’s value lies in long-term trends.
- No single "good" net worth exists—context matters. A $5 million net worth in real estate may differ from $5 million in cash equivalents.

Deep Dive: The Full Picture
The net worth model financial operates on two core principles: transparency and leverage. Transparency forces you to confront what you truly own. A celebrity’s reported net worth might exclude their future earnings or brand deals, painting an incomplete picture. Leverage, meanwhile, amplifies both gains and risks. A real estate investor with high mortgage debt might see their net worth swing wildly with interest rates, while a cash-rich retiree enjoys stability. The model doesn’t judge—it reveals. Its utility extends beyond personal finance. Corporations use variations of it to assess M&A targets, and governments evaluate national wealth through similar frameworks. Even cryptocurrency enthusiasts track their holdings via net worth models, though volatility makes the numbers less reliable. The key is consistency: whether you’re a day trader or a trust-fund heir, the model’s rigor ensures you’re not flying blind.The Context You Need
The rise of the net worth model financial parallels the democratization of financial data. Before the internet, calculating net worth required manual record-keeping—today, apps like Personal Capital or Mint automate the process. This accessibility has shifted the power dynamic: individuals now scrutinize their finances with the same tools once reserved for hedge funds. The model’s popularity also reflects a cultural shift toward financial literacy as a status symbol. Post-2008, the Great Recession exposed the fragility of debt-fueled lifestyles, and the net worth model became a tool for resilience. Yet context is everything. A software engineer in San Francisco with a $2 million net worth faces different challenges than a farmer in Iowa with the same figure. The model’s strength lies in its adaptability—whether you’re optimizing for retirement, an exit strategy, or generational wealth transfer. The critical question isn’t just what’s your net worth? but how does it align with your goals?The Mechanics
At its core, the net worth model financial is a balance sheet. Assets include cash, investments, property, and even intangibles like patents or royalties. Liabilities cover mortgages, student loans, credit card debt, and unfunded liabilities (e.g., future college tuition). The difference is your net worth. But the real work begins in the classification phase. Is a timeshare an asset or a sunk cost? How do you value a startup stake when it’s not publicly traded? These judgments require discipline. The model’s predictive power emerges when paired with time-series data. Tracking net worth over decades reveals patterns: a steady climb suggests disciplined saving, while erratic fluctuations may signal poor risk management. High-net-worth individuals often segment their net worth by asset class—cash, stocks, real estate—to identify imbalances. For example, if 80% of your net worth is tied to a single stock, the model flags concentration risk. The goal isn’t perfection but awareness.Details That Change the Picture
The net worth model financial gains depth when layered with qualitative factors. A $10 million net worth in a declining industry (e.g., coal) differs from $10 million in tech equity. The model alone won’t tell you whether your assets are liquid, diversified, or exposed to systemic risks. That’s where scenario planning comes in. What if a recession hits? What if your primary income source vanishes? The best net worth strategies account for these "what-ifs." Tax implications further complicate the picture. A $5 million net worth in a tax-advantaged account (e.g., a 401(k)) isn’t the same as $5 million in a brokerage account. The model must integrate estate planning: will your heirs inherit a burden of debt or a clean transfer of wealth? These nuances separate the theoretically rich from the practically secure."Net worth is vanity, but the model is utility. It’s the difference between knowing your balance sheet and knowing your business." — A former CFO of a Fortune 500 company
| Asset Class | Key Consideration |
|---|---|
| Real Estate | Liquidity risk (short sales vs. rentals), property taxes, and depreciation. |
| Public Stocks | Market volatility, dividend stability, and concentration risk. |
| Private Equity | Illiquidity, valuation uncertainty, and founder risk. |
Conclusion
The net worth model financial is more than a number—it’s a lens. It doesn’t tell you how to get rich, only whether your current path is sustainable. The most successful individuals use it as a stress test: if your net worth drops 20% in a downturn, can you weather it? If not, the model exposes the need for diversification or debt reduction. Its limitations—ignoring human capital, lifestyle inflation, or emotional biases—are well-documented, but those flaws are outweighed by its clarity. The future of the net worth model financial lies in integration. As AI and big data refine predictive analytics, the model will evolve from a static snapshot to a dynamic forecast. Already, tools like Wealthfront or Betterment use net worth data to suggest allocations. The next frontier? Behavioral net worth modeling—where the system accounts for your spending triggers, risk tolerance, and life stages. Until then, the model remains the most reliable compass for financial navigation.Comprehensive FAQs
Q: How often should I update my net worth?
A: Monthly for active investors, quarterly for most individuals, and annually for retirees. The frequency depends on asset volatility—cryptocurrency holders may need weekly updates, while a pensioner’s net worth changes slowly.
Q: Does my net worth include my home’s equity?
A: Yes, but only if it’s your primary residence or an investment property. Exclude vacation homes if they’re financed heavily, as their value may not reflect true liquidity.
Q: Can a negative net worth be useful?
A: Absolutely. A negative net worth signals financial distress but also highlights where to focus—paying down debt, increasing income, or liquidating non-essential assets. It’s a red flag, not a death sentence.
Q: How do I account for illiquid assets like a business stake?
A: Use a fair market valuation (e.g., recent sales of similar businesses, earnings multiples). For private companies, this often requires an appraiser. The key is consistency—don’t inflate values arbitrarily.
Q: Does the net worth model financial work for freelancers?
A: Yes, but with adjustments. Freelancers must account for human capital (future earning potential) and revenue volatility. A freelancer’s net worth might include their client list as an intangible asset, though it’s hard to quantify.
Q: What’s the difference between net worth and cash flow?
A: Net worth is a snapshot of assets minus liabilities; cash flow is a stream of income minus expenses. A high net worth with negative cash flow (e.g., living off loans) is unsustainable. Both metrics are critical.
Q: Can I use the net worth model financial for estate planning?
A: Indirectly. The model helps identify assets that need to be structured for inheritance (e.g., trusts, life insurance). However, estate planning requires additional tools like wills, power of attorney, and tax-efficient transfers.
Q: What’s the biggest mistake people make with this model?
A: Overvaluing assets (e.g., assuming a home’s worth hasn’t changed in years) or underestimating liabilities (e.g., ignoring future medical costs). The model is only as good as the data input.
