
The Short Answers
- A net present worth table converts future cash flows into today’s dollars using a discount rate, making apples-to-apples comparisons possible.
- It’s widely used in corporate finance, real estate, and public sector projects to justify investments with long payback periods.
- Common pitfalls include overestimating future returns or underestimating discount rates, leading to flawed decisions.
- Software like Excel or specialized tools automate calculations, but manual adjustments are often needed for accuracy.
- The table’s reliability hinges on the quality of input data—garbage in yields garbage out, even with perfect formulas.
Deep Dive: The Full Picture
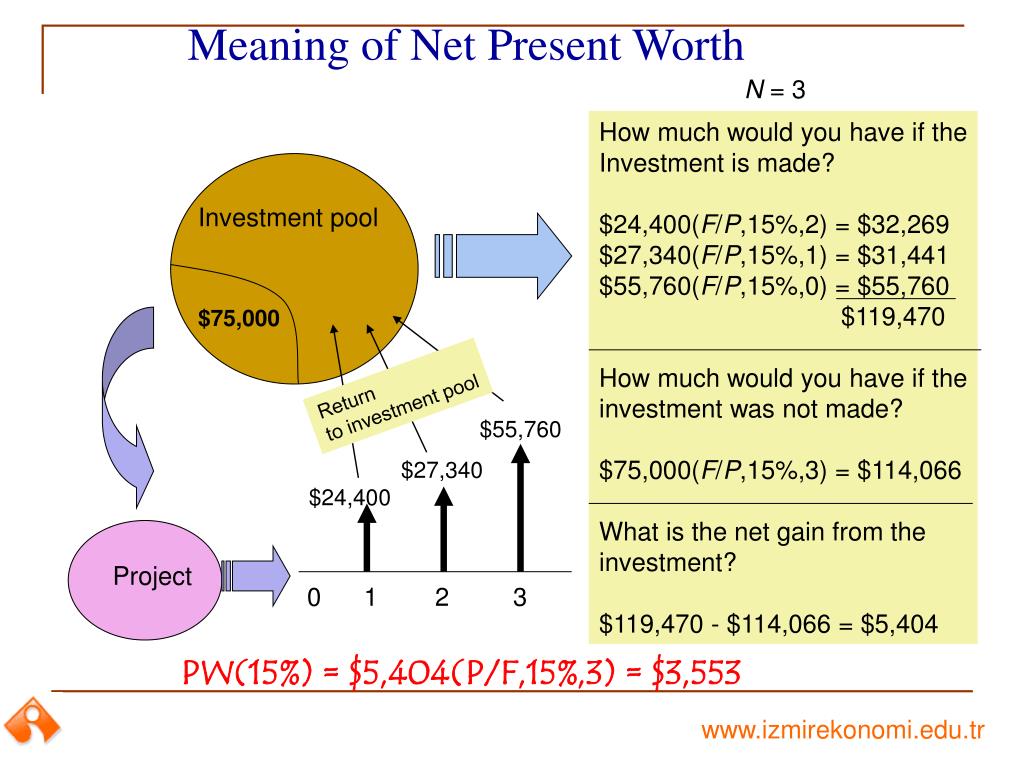
The net present worth table operates on a deceptively straightforward premise: money today is worth more than money tomorrow. This isn’t just about inflation—it’s about the ability to invest, spend, or mitigate risk with funds available now. A project generating £100,000 in five years isn’t equivalent to £100,000 today because that £100,000 could earn additional returns if deployed elsewhere. The table quantifies this difference by applying a discount rate, typically tied to the cost of capital or risk-free rates adjusted for volatility. The result? A single figure that summarizes an investment’s true economic contribution. Its versatility extends beyond corporate boardrooms. Private equity firms use it to assess acquisition targets, while individuals might apply it to weigh the costs of education against lifetime earnings. Even governments rely on net present worth tables to prioritize infrastructure spending—though political pressures often distort the math. The table’s strength lies in its flexibility: it can handle irregular cash flows, incorporate tax implications, or factor in inflation, provided the inputs are rigorously vetted.The Context You Need
Financial theory often treats the net present worth table as a solved problem, but real-world applications reveal its limitations. For instance, startups with unpredictable revenue streams may struggle to assign accurate discount rates. A tech company’s valuation might hinge on speculative growth projections, making the table’s output less a prediction and more a snapshot of assumptions. Similarly, public projects—like a new subway line—face challenges in quantifying intangible benefits, such as reduced traffic congestion or improved quality of life. The table’s role also shifts depending on the stakeholder. Investors prioritize returns, while policymakers may weigh social costs. This divergence explains why some projects pass muster under one framework but fail under another. For example, a renewable energy plant might show a negative net present worth under private sector discount rates but a positive one when government subsidies are factored in. The table doesn’t resolve these conflicts—it surfaces them.The Mechanics
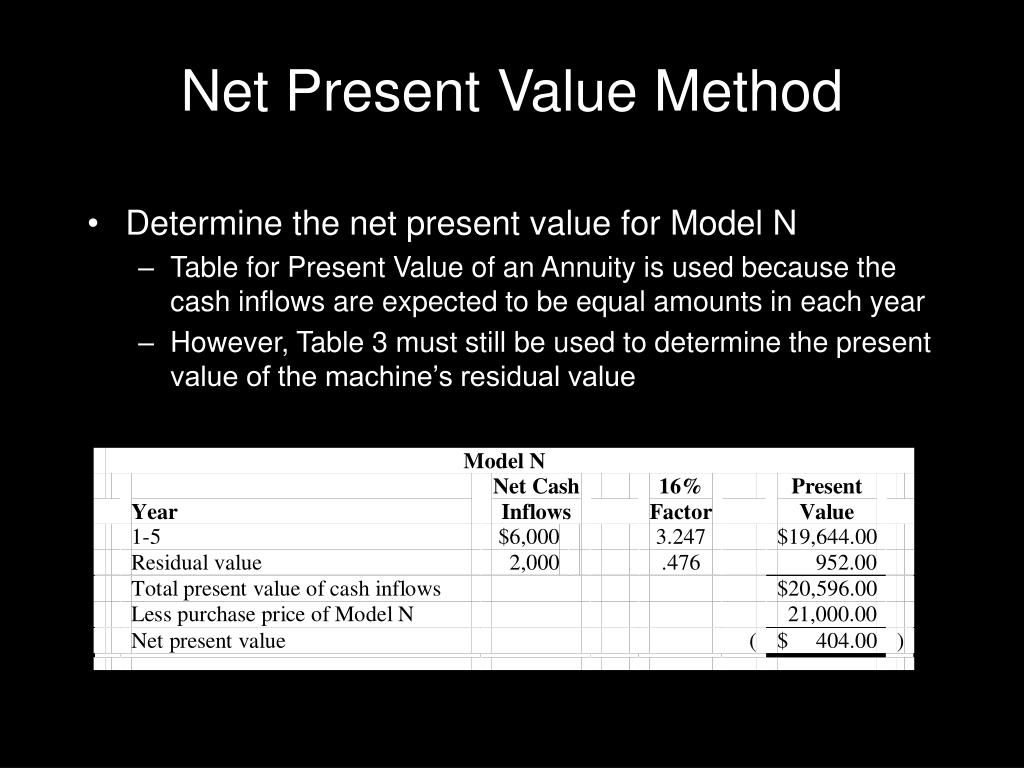
At its core, the net present worth table is built on three pillars: cash flow estimation, discount rate selection, and time horizon. Cash flows must account for all relevant inflows and outflows, including operational costs, taxes, and working capital changes. The discount rate, often derived from the weighted average cost of capital (WACC), reflects the risk associated with the investment. A higher rate penalizes riskier projects, while a lower rate favors safer bets. The time horizon determines how far into the future cash flows are projected—too short, and long-term benefits vanish; too long, and projections become unreliable. Software like Excel’s NPV function automates calculations, but manual adjustments are critical. For instance, a real estate developer might adjust the discount rate for market volatility or incorporate hold periods beyond standard models. The table’s output—a net present value (NPV)—tells the story: positive NPV indicates value creation, negative NPV signals a drain on capital. Yet interpreting the result requires context. A £500,000 NPV might be stellar for a small business but negligible for a multinational.Details That Change the Picture
The net present worth table’s utility hinges on two often-overlooked factors: sensitivity analysis and alternative scenarios. A single NPV figure is a snapshot, not a forecast. By testing how changes in discount rates, cash flow timing, or project duration affect the outcome, decision-makers uncover vulnerabilities. For example, a mining project’s NPV might drop sharply if commodity prices fall 10%, revealing exposure that a static table obscures. Similarly, comparing NPVs across scenarios—best-case, worst-case, and most-likely—helps prioritize resilience over optimism. Inflation and currency risk further complicate the picture. A project in a high-inflation economy may require adjusting discount rates or cash flows to reflect local conditions. Multinational corporations face additional layers, such as exchange rate fluctuations or regulatory changes, which standard tables don’t address. These nuances explain why financial models are rarely static—they evolve as new data emerges."The net present worth table is a mirror—it reflects the assumptions you feed it. If you’re optimistic about growth but pessimistic about risks, the table will show it. The challenge isn’t the math; it’s the discipline to confront what it reveals." — Mark R. Kamlet, former CFO of a Fortune 500 energy firm
| Scenario | Net Present Worth (£) |
|---|---|
| Base Case (5% discount rate) | +£1,245,000 |
| Optimistic (3% discount rate) | +£1,890,000 |
| Conservative (7% discount rate) | +£620,000 |
| Worst-Case (9% discount rate, delayed cash flows) | -£180,000 |
Conclusion
The net present worth table remains one of the most powerful yet underappreciated tools in finance. Its ability to distill complex cash flows into a single, actionable metric is unmatched—provided the user understands its boundaries. The table doesn’t predict the future; it clarifies the implications of today’s choices. Whether applied to a corporate merger, a personal savings plan, or a government stimulus package, its role is to expose trade-offs rather than eliminate them. The real test lies in execution. A well-constructed net present worth table isn’t just a spreadsheet—it’s a conversation starter. It forces stakeholders to align on assumptions, challenge projections, and confront uncertainty. In an era where data is abundant but wisdom is scarce, the table’s value isn’t in the numbers alone but in the discipline they demand.Comprehensive FAQs
Q: How do I choose the right discount rate for my net present worth table?
The discount rate should reflect the opportunity cost of capital and the project’s risk profile. For corporate projects, the weighted average cost of capital (WACC) is common. Private investors might use their required rate of return. Always justify the choice—an arbitrary rate undermines the table’s credibility.
Q: Can a net present worth table account for non-financial benefits, like employee morale or environmental impact?
Indirectly. Non-financial factors can be monetized (e.g., assigning a value to reduced turnover or carbon credits) or included as qualitative notes alongside the table. Some frameworks, like social return on investment (SROI), attempt this, but the results are often subjective.
Q: Why might two analysts arrive at different net present worth figures for the same project?
Discrepancies arise from differences in cash flow projections, discount rates, or time horizons. One analyst might assume a 5% discount rate; another, 7%. Even small variations in assumptions can lead to vastly different NPVs. Transparency in methodology is critical.
Q: Is a positive net present worth always a good sign?
Not necessarily. A positive NPV indicates value creation under the given assumptions, but it doesn’t guarantee execution success. External factors—regulatory changes, market shifts, or operational failures—can override the model’s projections.
Q: How often should I update my net present worth table?
Regularly. Cash flows, discount rates, and market conditions evolve. A table built on outdated assumptions becomes a liability. Quarterly or annual reviews are standard for dynamic projects; static ones may require updates only when major changes occur.
