
Breaking Down the Numbers
The middle class has long been defined by its ability to maintain a balance between stability and opportunity. By 2025, that balance will be tested by forces beyond individual control: geopolitical tensions, technological disruption, and shifting labor markets. The middle-class net worth 2025 projections must account for these variables, starting with the baseline of what’s already observable. Public data from the U.S. Census Bureau and Federal Reserve provides a starting point. As of 2023, the median net worth for middle-income households (defined as those earning between $50,000 and $150,000 annually) was approximately $165,000. This figure includes primary residences, retirement accounts, and liquid assets. However, the composition of that net worth has shifted. Homeownership rates have dipped slightly, while student loan debt remains a drag on younger cohorts. By 2025, the middle-class net worth is expected to reflect these trends, with home equity contributing less to total wealth than in previous decades.The Verified Baseline
The most concrete data comes from longitudinal studies tracking household wealth over time. For example, the Survey of Consumer Finances (SCF) has consistently shown that the middle class’s net worth growth lags behind the top 10% by a margin of roughly 2:1. In 2022, the median net worth for the top decile was $1.1 million, compared to $165,000 for the middle quintile. Extrapolating this ratio forward, the middle-class net worth 2025 could reasonably be projected to hover around $180,000 to $200,000, barring economic shocks. What’s less certain is how this wealth is distributed. Regional disparities will widen: coastal cities may see stagnation due to high living costs, while Sun Belt states could experience faster growth from migration and lower expenses. The middle-class net worth 2025 will thus vary significantly by geography, with urban centers potentially underperforming relative to suburban and rural areas.What the Estimates Suggest
Private sector analyses offer a glimpse into potential scenarios. According to a 2024 report by the Urban Institute, middle-class households could see a 5% to 7% annualized growth in net worth if inflation remains subdued and wage growth outpaces price increases. However, this assumes no major policy changes—such as tax reforms or social safety net adjustments—that could either bolster or erode wealth accumulation. The estimates also highlight the role of alternative assets. Traditional retirement accounts (401(k)s, IRAs) will still be critical, but younger middle-class earners are increasingly turning to index funds, real estate crowdfunding, and peer-to-peer lending to supplement their portfolios. By 2025, these non-traditional holdings could account for 10% to 15% of the average middle-class net worth, up from roughly 5% in 2020. The shift reflects a broader trend: the middle-class net worth 2025 will be less reliant on employer-sponsored plans and more diversified across asset classes.
Case Study: A Closer Look
Consider the experience of the Smith family, a middle-class household in Austin, Texas, with two incomes and no children. In 2020, their net worth was $175,000, primarily in home equity and retirement accounts. By 2023, rising home values and a modest stock market recovery had pushed their net worth to $220,000. However, their financial strategy shifted in response to economic signals: they allocated a portion of their savings to short-term Treasury bonds to hedge against inflation, while also contributing to a health savings account (HSA) for tax-advantaged growth. Their case illustrates how the middle-class net worth 2025 will depend on proactive adjustments. Had they remained passive—relying solely on employer matches and static savings rates—their growth would have lagged behind peers who diversified. The Smiths’ story underscores a key takeaway: the middle-class net worth trajectory in 2025 will favor those who treat wealth accumulation as an active process, not a passive outcome."We used to think saving 10% of our income was enough. Now, we’re treating our net worth like a business—diversifying, hedging, and staying liquid. The middle class in 2025 won’t just have more; they’ll have smarter." — James Smith, Austin-based financial planner
| Factor | Estimated Impact on Net Worth Growth (2025) |
|---|---|
| Home Equity | Moderate growth (2%–4% annually), with regional variations |
| Retirement Accounts (401(k)/IRA) | Steady growth (5%–7% annually), assuming market returns |
| Alternative Investments (Crypto, P2P Lending, etc.) | Volatile but potentially high returns (–10% to +20%) |
| Student Loan Debt Repayment | Negative impact if prioritized over investments; neutral if managed |
| Inflation Hedging (Treasuries, TIPS, etc.) | Stabilizing effect (1%–3% additional growth) |
What This Means Going Forward
The middle-class net worth 2025 will not be a static number but a dynamic metric reflecting how households navigate uncertainty. The traditional playbook—save aggressively, buy a home, retire at 65—is being rewritten. Younger middle-class earners, in particular, will need to embrace flexible retirement timelines and lifelong learning to stay competitive in a labor market where skills depreciate faster than ever. Policy will play a decisive role. If student loan forgiveness or expanded childcare subsidies materialize, the middle-class net worth 2025 could see a boost from reduced debt burdens. Conversely, if tax policies favor capital gains over wage income, the wealth gap may widen further. The middle class’s ability to adapt will hinge on access to financial literacy resources and tools that demystify complex asset classes.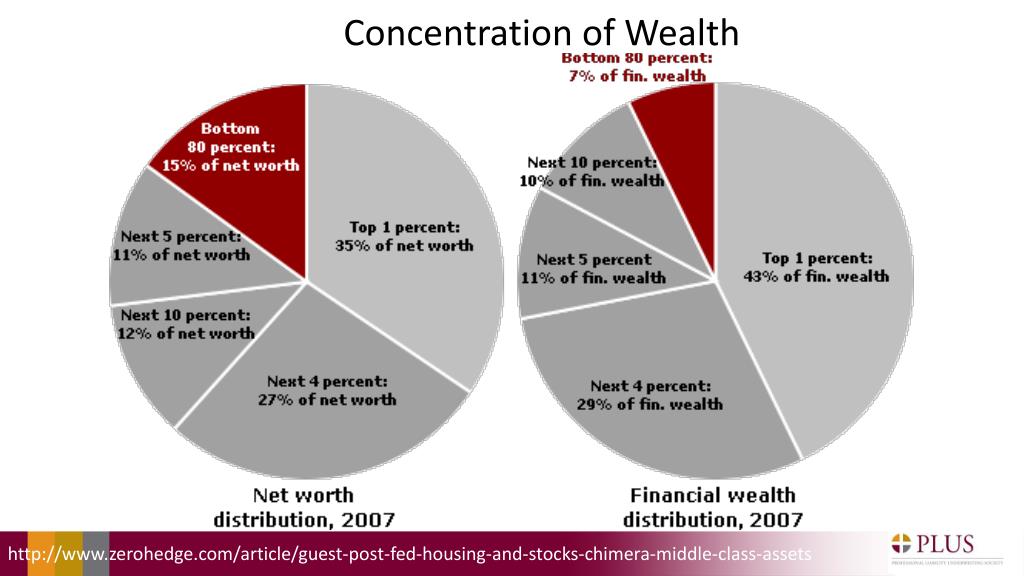
Conclusion
The middle-class net worth 2025 will tell a story of resilience, but also of necessary evolution. It won’t be about hitting a single target; it will be about building buffers against an unpredictable future. For households that succeed, the payoff will be financial security that extends beyond retirement—into healthcare, education, and unexpected crises. The data suggests that the middle class is not disappearing, but transforming. The question for 2025 is whether that transformation will be led by policy, innovation, or individual action. The answer will determine whether the middle-class net worth remains a measure of stability—or becomes a relic of a more predictable past.Comprehensive FAQs
Q: How does inflation affect the middle-class net worth 2025?
The impact is twofold: inflation erodes the purchasing power of existing savings, while higher living costs can reduce the ability to save. By 2025, households may see their net worth grow in nominal terms but stagnate—or even decline—when adjusted for inflation. Strategies like TIPS (Treasury Inflation-Protected Securities) or real estate can help mitigate this risk.
Q: Will the middle-class net worth 2025 be higher in rural areas than cities?
Likely yes. Rural and suburban areas often offer lower housing costs, which directly boost home equity—a key component of middle-class net worth. Urban centers, particularly coastal cities, may see slower growth due to high expenses and stagnant wage growth. However, tech hubs could be exceptions if remote work trends continue.
Q: How important are side hustles to the middle-class net worth 2025?
Side hustles will be increasingly critical, especially for younger middle-class earners. The gig economy and freelance work can supplement primary incomes, allowing for higher savings rates or investments. By 2025, households with diversified income streams may see their net worth grow 10% to 20% faster than those reliant on single jobs.
Q: Can the middle-class net worth 2025 recover from a recession?
Recovery is possible but depends on the severity of the downturn. Historically, middle-class net worth has rebounded within 5–7 years post-recession, driven by asset appreciation and wage growth. However, if unemployment spikes or debt levels rise sharply, the middle-class net worth 2025 could remain depressed for a longer period.
Q: What’s the biggest threat to middle-class net worth in 2025?
The biggest threats are structural: wage stagnation, healthcare costs, and student debt. Unlike past recessions, where middle-class wealth was primarily tied to housing, today’s risks are more diffuse—spanning education, healthcare, and the gig economy. Without policy intervention or personal adaptation, these factors could suppress net worth growth for a generation.
